For the past two years, the most important issue for New Zealanders has been inflation.
It’s easy to see why. The consumer price index has increased by more than 17% since inflation exploded out of the Reserve Bank’s target range two years and five months ago.
Households have faced an even larger increase to their cost of living than that headline figure would suggest, since it excludes mortgage repayments.
Statistics New Zealand’s living-costs price indexes, which does include interest payments, shows the cost of living has increased more than 19% for the average household.
It’s important to note that wages have risen as well but only about 16%, which means people are still out of pocket. Plus, people likely feel they earned a pay rise and should be better off.
This is the number one reason the Coalition Government was elected. Not because of Treaty issues, ‘woke’ United Nations agreements, Māori words on street signs, or whatever else.
Prime Minister Christopher Luxon knows this and wants to show the public that he is deadly serious about halting the increasing cost of living.
And so, the first legislative action of his government will be to remove the part of the Reserve Bank’s mandate that tasks it with targeting maximum sustainable employment.
This is largely a symbolic move, as it won’t result in lower inflation, but lots of things governments do are about signalling some sort of virtue. It doesn’t make them worthless.
Few economists think simplifying the mandate would have any impact on monetary policy during this cycle, but many support the change anyway.
Bevan Graham, an economist at Salt Funds, said returning the central bank to a sole focus of maintaining price stability was a “welcome development” for two reasons.
First, the dual objectives could clash in some extreme circumstances. It would not be clear what the bank should do if inflation and unemployment were both high, for example.
This is an unlikely scenario, as employment levels and inflation are closely correlated, but one can always dream up a hypothetical economic shock that would cause it to happen.
“The second and more important reason is that central banks lack the tools and direct influence needed to affect employment outcomes,” Graham said.
“Employment is influenced by a complex interplay of factors, including fiscal policies, labour market dynamics, and broader structural issues”.
Outcomes in the labour market will always be important for the Reserve Bank, but it only controls interest rates and the money supply — tools best suited to maintaining price stability.
“The reality is there are a multitude of other government agencies that should be taking responsibility for labour market outcomes,” he said.
Know who to blame
It would also shift responsibility for employment onto the Government and force them to confront policy settings that could be contributing to bad outcomes for workers.
The Reserve Bank itself suggested arranging its objectives in order of importance, so that it could have clarity on how to act if they did come into conflict.
So, changing the central bank’s mandate does minimal harm and sends a strong signal that the National-led Government wants inflation under control — an easy win for Luxon.
The more difficult test will come at the Half Year Economic and Fiscal Update, before Christmas, and at the Government’s Budget in May.
Here Luxon and his Finance Minister, Nicola Willis, have to make good on their promise to not add to inflation pressure while still cutting taxes and improving outcomes in public services.
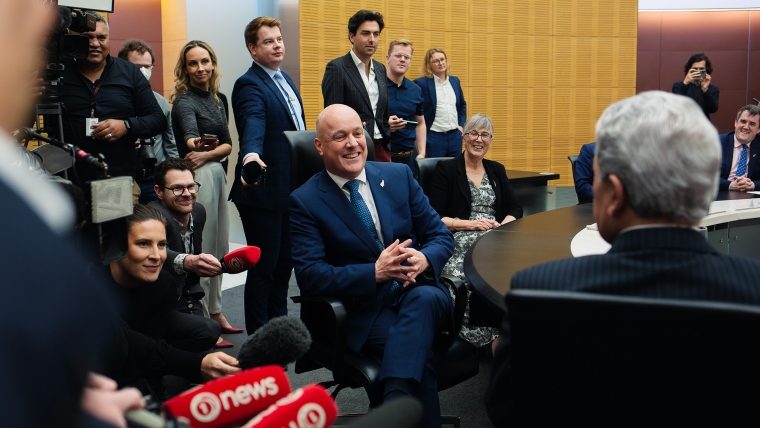
The Prime Minister talked a good game at his first Post Cabinet press conference on Monday, saying he was determined to get fiscal and monetary policy working together.
“[Governor Orr] can only go so far if we don't have our fiscal situation sorted and under control. That's why we need to go through government spending with a very big focus on that,” he said.
On Wednesday, the Reserve Bank warned the Pre-Election Economic and Fiscal Update added more pressure to inflation than it had expected when looking at the Budget update.
The implicit message to the new Government was that if it wants to help avert another Official Cash Rate increase, it will need to deliver a much tighter set of books than that — a tough job.
D.O.A?
One final thought: National’s coalition agreement with the Act Party promised to seek advice on several other changes to the Reserve Bank’s mandate.
Such as making the Governor the sole policymaker, setting time targets for achieving the inflation target, and removing the Treasury observer from the Monetary Policy Committee.
The first two changes go against international best practice, so officials are likely to advise against them, while the final one has mixed opinions.
Since the Government is pressing ahead with legislation to change the mandate before seeking any of this advice, you have to wonder if those other changes are dead on arrival.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.