
Adrian Orr, Governor of the Reserve Bank of New Zealand (RBNZ), says the central bank is effectively targeting core inflation and it is falling slower than the headline measure.
At the Waikato University’s annual economics forum, Orr spoke about the challenges of distinguishing between ‘transitory’ inflation and ‘persistent’ or ‘core’ inflation.
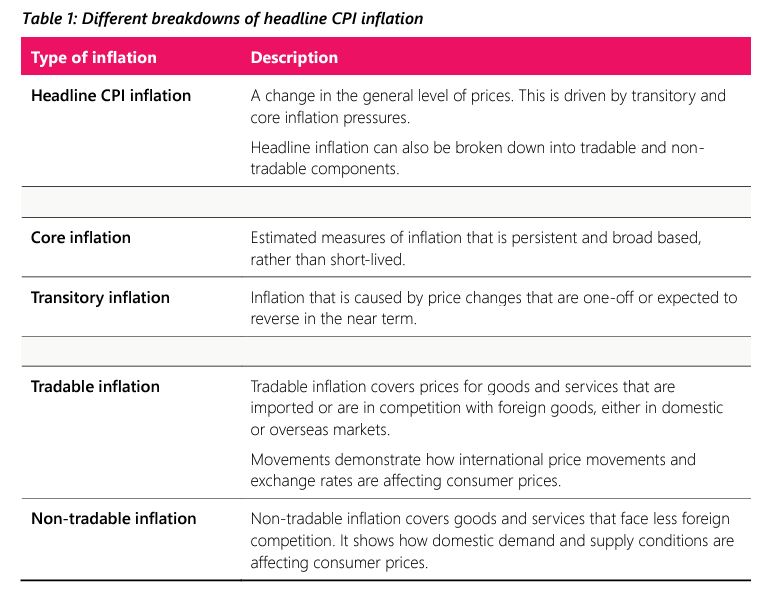
Transitory inflation is usually caused by unexpected relative price shocks which tend to dissipate over time. Core inflation is what is left in the system when the transitory shocks have worked their way out of the economy.
“So, we observe headline, but we are targeting, in a large sense, core inflation,” Orr said.
His speech notes phrased it differently: “Monetary policy leans against these more persistent inflationary pressures to ensure that headline inflation is expected to return to target over the medium term”.
The RBNZ Governor said measures of core inflation helped the Monetary Policy Committee identify how much of headline inflation was persistent and where pressure was coming from.
Headline inflation had fallen to 4.7% by the end of last year—from a peak of 7.3% in 2022—but core and non-tradable inflation have been much more stubborn.
Non-tradable inflation has fallen less than one percentage point from its peak of 6.8%, and other core inflation measures have also only just begun to react.
“While these declines in core inflation are moving us in the right direction, tackling the tail end of these persistent inflation pressures in the domestic economy remains key to achieving 2% inflation,” Orr said.
The monetary policy committee begins its February meeting next Monday and announces the result of its review on the 28th.
Orr said the proximity of this meeting meant he couldn’t talk about his views on how interest rates and other policies should be set.
However, he spoke several times about the Reserve Bank’s focus on core inflation and its intolerance of anything that threatened the return to the 2% target.
The central bank’s “appetite to look through” transitory price shocks was “significantly reduced” during a period of high inflation and inflation expectations.
“Central banks around the world have been trying to explain, ad nauseam, to the public that while inflation is coming down, we are not there yet, and the last few yards may be very difficult because we really need to re-anchor that 2% inflation expectation”.
Again, these lines were not specifically included in the speech notes.
Elsewhere in the speech, Orr spoke in support of the flexible inflation target focused on the 2% midpoint and reflected on how core inflation was underestimated during the pandemic.
In the speech Orr went into further detail on core inflation, describing it as representing pricing pressures likely to persist once temporary shocks have unwound.
"Core inflation is driven by things like capacity constraints – the balance between supply and demand – as well as labour market dynamics and wage inflation. They reflect general, rather than relative, price movement in the economy. Expectations of future inflation are also a key driver of core inflation," he said.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.