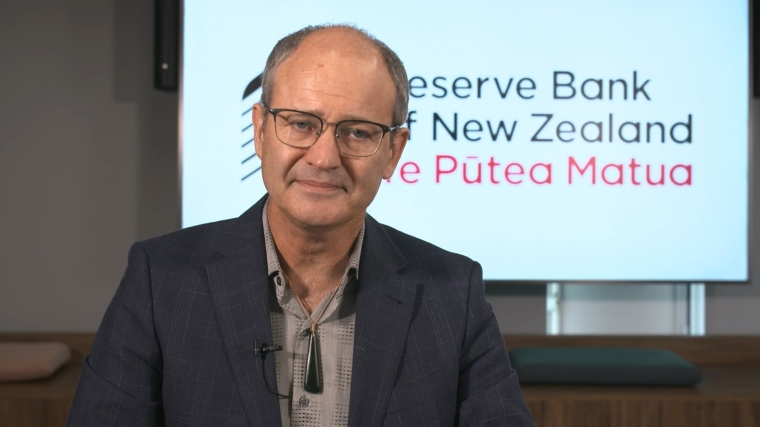
Reserve Bank chief economist Paul Conway says economists have failed to make a strong case for what New Zealand could look like with a more productive economy.
Productivity growth has averaged just 0.2% over the past decade, lagging behind other countries despite a global slowdown.
For some of those years, Conway was director of economic research at the now-defunct Productivity Commission and told RNZ he felt partly to blame for the lack of progress.
“That's been a vexing question for me, and I feel a little responsible. I think the economics community in New Zealand hasn't really sort of put forward a coherent vision of what a high productivity, high wage economy would look like,” he said.
Policy changes to improve competition, infrastructure, and capital markets would help, but much of the work needs to happen within private businesses. Firms need to invest in new technology, develop digital exports, and adopt better tools instead of simply hiring more workers.
Conway said the data suggests businesses didn’t seem sufficiently incentivised to lift productivity, despite frequent talk about it in Wellington policy circles.
“It's not solely the responsibility of the government and the public sector to fix this thing. Apart from state sector productivity, which is a huge issue in itself, lifting productivity is largely up to the private sector.”
He gave three key reasons for New Zealand’s weak productivity, all of which “flows back to our economic geography, the fact of being a small economy that's a long way from anywhere else”.
First, New Zealand is not well connected to the rest of the world. While it is often called a “small, open economy”, it has low export intensity relative to its peers, and many Kiwi businesses are not “outward looking”.
Second, the economy is labour-intensive and capital-shallow, meaning investment is spread thinly across the population. Many large firms are cooperatives or partly government-owned, which can also constrain investment.
Third, businesses tend not to invest in “knowledge based capital” such as staff education, organisational improvements, managerial capability, or research and development of new products or processes.
None of this is likely to change quickly, although the Government has introduced a tax incentive for business capital investment, which may support productivity growth.
Conway said the Reserve Bank expects it will boost investment, though likely not until uncertainty over Donald Trump’s trade policies subsides.
“In these interesting, somewhat troubled times globally, it is pretty natural for businesses to stand back,” he said.
“A short spike in uncertainty doesn't have much effect on the economy, but if you get a spike and it hangs on up there, it has a more negative effect. And that's very much where we are currently.”
White gold
Westpac NZ’s economics team used a series of recent customer presentations in Auckland, Wellington, and Hamilton to survey attendees on their views of the economy.
Respondents in Auckland and Wellington were “subdued”, while those in Hamilton were more upbeat—likely because its economy is more closely tied to the buoyant dairy sector.
Fonterra has announced its highest ever opening milk price forecast, projecting it will pay farmers between $8 and $11 per kilo of milk solids.
Conway said there is currently a wide gap between provincial and metropolitan economies, but it should start to close as lower interest rates take greater effect later this year.
Westpac NZ also asked clients about Investment Boost—a 20% tax rebate on capital assets—and found that firms already planning to invest were likely to bring spending forward.
“In Hamilton we can see the potential for increased on-farm investment this year. That makes sense given returns are very strong in the primary sector right now,” they said.
However, a large share of firms still didn’t expect to raise investment, as conditions remained tough.
Cameron Mitchell, head of geopolitical risk at ANZ Group, told the NZ Herald that businesses needed to become more comfortable investing during periods of global risk.
“I think it's less about dealing with the level of uncertainty and maybe tolerating the level of uncertainty, because I think we are at the end of a decades long pretty stable geopolitical order. Things are going to get less predictable,” he said.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.