
Dairy giant Fonterra has made a late, late cut to its milk price forecast with just days to run in the current season - as well as having a go at its first forecast for the season that will start in June 2023. Additionally, an $800 million capital return is being brought forward.
And Fonterra also says it has lifted its forecast "normalised" earnings to 65-80 cents per share from 55-75 cents per share and says it remains on track "for a strong full year dividend".
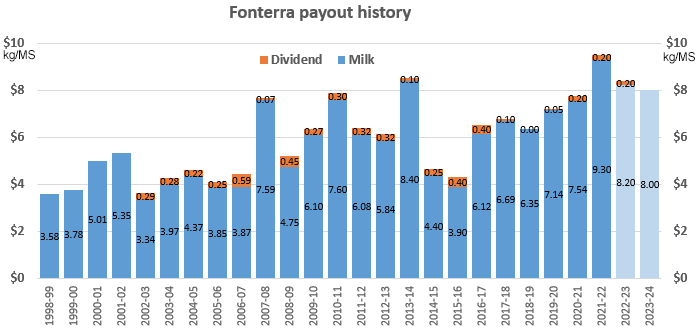
The Fonterra co-operative is now forecasting an implied price for its supplier/shareholder farmers of $8.20 per kilogram of milk solids for the season that is about to end, down from $8.30.
This is the third cut that's been made to the forecast since the start of the year and means that the implied price to farmers is actually now some $1.30 lower than the very high forecast made earlier in the season.
At $8.20, the price would still be the third-best in Fonterra's history, albeit well down on the record $9.30 paid last year.
The downgrades in forecast prices from Fonterra have come amid a backdrop of falling dairy prices globally.
As for the new season that's about to start, Fonterra's first forecast implies a price to farmers of $8 per kilogram of milk solids.
The term 'implied' is used here because for several years now Fonterra has expressed its forecasts as a range - and the implied figure is the midpoint of that range.
The new forecast range for the season that's about to end is $8.10 - $8.30 per kgMS.
As is typical at the start of a season, Fonterra's forecast range for the season that starts next month is a wide one - $7.25 to $8.75 per kgMS, with a midpoint of $8.00 per kgMS.
Last year Fonterra announced it had sold its Soprole business in Chile and was planning to return capital.
Now it is bringing forward that capital return. It says the payment date of the proposed return of around 50 cents per share and unit, will be moved from October 2023 to August 2023.
The co-operative says implementation of the capital return, remains subject to a Scheme of Arrangement being voted on by shareholders, and approval by the High Court.
Fonterra chief executive Miles Hurrell says while the forecast farmgate milk price for this season has been impacted by reduced demand, particularly from China, the co-op remains on track for a strong full year dividend.
"Global Dairy Trade prices have not recovered to the levels required to hold the previous [milk price forecast] midpoint for this season," Hurrell said.
He said the opening forecast price for next season "reflects an expectation that China’s demand for whole milk powder will lift over the medium-term".
"We expect demand to gradually strengthen over the course of FY24 as China’s economy continues to recover from Covid-19.
"However, the timing and extent of this remains uncertain, with China’s in-market whole milk powder stocks estimated to be above normal levels following increased domestic production. This is reflected in our wide opening forecast range for the season."
He said he recognised the pressure farmers are under and Fonterra has designed a new Advance Rate guideline to get cash to farmers earlier in the season.
"Our strong balance sheet allows us to make these changes and we will be using this new Advance Rate guideline going forward, starting with the season about to commence.
Meanwhile, Fonterra has reported a profit after tax of $1,326 million, equivalent to 81 cents per share, for the third quarter of the 2023 financial year. This is up $854 million on the same period last year and includes the gain on sale from Soprole of $260 million.
"Excluding the net gain from divestments, our normalised profit after tax improved on last year, up $606 million to $1,078 million, equivalent to 65 cents per share," Hurrell said.
"This is due to strong performance in our Ingredients channel, with continued higher margins in our cheese and protein portfolio, particularly casein and caseinate.
"These favourable price relatives have continued longer than expected, and we’re also seeing improved performance coming through in our Foodservice and Consumer channels, in particular in Global Markets.
"As a result, we have lifted our FY23 full year forecast normalised earnings to 65-80 cents per share from 55-75 cents per share and remain on track for a strong full year dividend.
"Total Group normalised operating expenses are up in part due to the impact of impairments reported in our FY23 Interim Results in March, as well as ongoing inflationary pressures," Hurrell said.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.