
BNZ economists are forecasting that economic growth in New Zealand will stall completely next year and "the danger is that the wheels well and truly fall off".
And they say the house price falls that have started will get worse.
In the BNZ's latest Economy Watch publication, the bank's head of research Stephen Toplis says the chances of the New Zealand economy moving into recession are "rising by the day".
"New Zealand’s economic 'imbalances' continue to be exposed at a time when the global economy is increasingly coming under duress," he says.
"The policy measures taken to 'fix' these issues are getting more and more aggressive.
"The chance of a soft landing is fading."
Toplis says the fundamental issue the country faces is that the economy has suffered a series of massive supply shocks. Domestically, the biggest impact has been felt via the labour market. Those suffering with Covid and\or isolating have left businesses short-staffed and needing to employ swathes of temporary staff.
"This is costly and, eventually shows up in selling prices. As if this wasn’t bad enough, closed borders imposed an additional constraint on the supply of labour. And don’t forget labour was already in short supply pre-Covid. Consequently, not only have businesses been forced to take on more labour to cover shortages but they have also had to compete, via rising salaries, for the diminished pool of labour which remains available to draw on."
The labour market has, therefore provided "a major general inflationary pulse" for the economy.
"But labour supply constraints have not been limited to New Zealand. Many of the same issues are being faced across the planet meaning the cost of imported goods is also rising."
And, in New Zealand’s case, the freezing of international supply chains has further reduced the capacity of the economy to produce goods and inflated prices as an auction market for goods in short supply develops, Toplis says.
"As if all this wasn’t terrible enough: the Russians decided to invade Ukraine, and the Chinese decided to impose one of the most severe lockdowns seen on the planet. The former added to supply chain issues and resulted in massive upward pressure on energy prices, food, fertiliser and some base metals costs, amongst other things. The latter simply dropped demand further.
"To cap things off, more recently, the New Zealand dollar has fallen sharply pushing up tradables goods prices even further."
Toplis says in terms of a response to this, the Reserve Bank is faced with doing the majority of the heavy lifting.
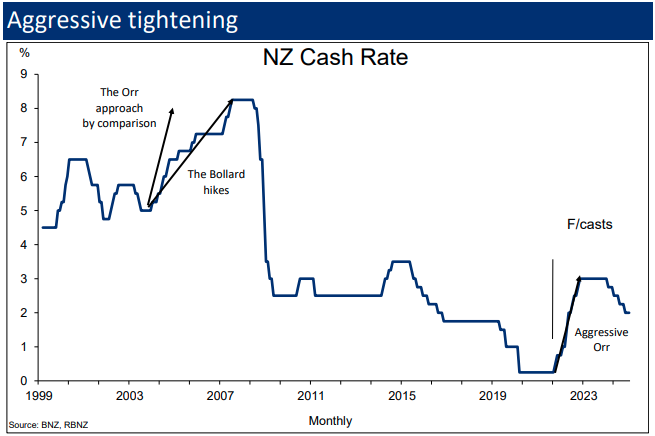
"But with inflation and the unemployment rate so far from their respective targets, and supply unlikely to lift markedly in the near term, the only available option is to crush demand to meet the new levels of supply.
"From the RBNZ’s perspective, this means getting CPI inflation down from an expected annual peak of around 7.0% in the June quarter of 2022 back to near 2.0% and seeing the unemployment rate rise from its current low of 3.2% to something of the order of 4.5%. Realistically there are only three ways that this can play out:
- There is a sudden positive supply response both domestically and internationally;
- The economy goes through a relatively protracted period of low growth;
- The economy goes into recession.
"We accept that supply conditions will start to improve. Already, fewer people are isolating because of Covid, border controls are being reduced and global supply chains are starting to ease. But there is a very long way to go.
"Our central forecast, currently, is that New Zealand’s growth stalls completely in 2023. The danger is that the wheels well and truly fall off."
Toplis is expecting the RBNZ to hike the Official Cash rate by a further 50 basis points in the next rate review on May 25, (bringing the OCR up to 2.0%).
And he believes there will be a further a series of rate increases until such time that the OCR reaches somewhere between 3.00% and 3.50%.
"This will represent the steepest increase in the cash rate since the Reserve Bank began inflation targeting, and its magnitude will come close to matching the [then RBNZ Governor Alan] Bollard era tightening cycle which ultimately ended in the 2008/2009 recession, albeit that it wasn’t just interest rates that generated that recession."
On the currently falling house prices, Toplis says, "that is most definitely going to get worse".
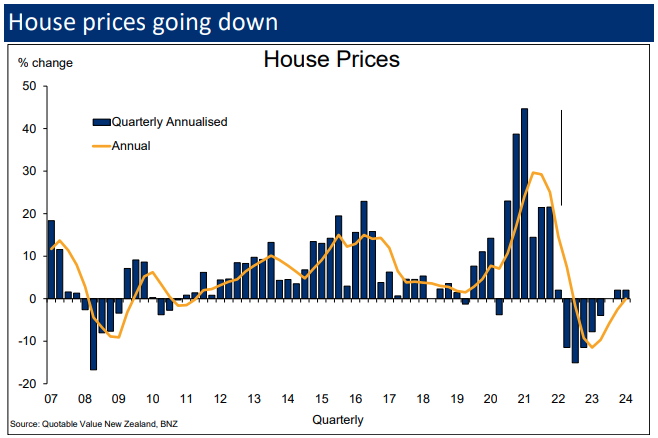
"The REINZ’s Stratified House Price Index is already down 4.2% from its peak. And the consensus view is that prices will eventually correct between 10 and 15%. The risk is that they go even further than this. In 2008 the peak to trough house price decline was 10.9%.
"Falling house prices constrain household spending via the wealth effect. Spending on big ticket and discretionary items normally take the biggest hit. This at a time when increased spending by New Zealanders offshore will also constrain domestic spending."
Toplis says whichever way you look at it, "the planets are aligning in such a way that a recession seems difficult to avoid".
"We should note, that when we talk the possibility of recession, we are referring to some time in 2023 when the full impact of rate increases and falling asset prices hits home."
Toplis notes that when/if the recession does eventually arrive, there are a number of factors, this time around, that should moderate the pain that might be felt. In short:
- There is such a strong excess demand for labour in New Zealand currently that the first stage in any economic softening will simply ameliorate the excesses rather than drive the unemployment rate higher.
- Hopefully, an increased supply of offshore labour, albeit modest, will mean that some of the increase in the unemployment rate is more to do with an inability to absorb supply rather than wholesale layoffs.
- The peak in the unemployment rate should be lower than in previous recessions.
- The government’s coffers are in decent nick so extra fiscal spending can come to the rescue if things begin to look dire.
- While there will be fallout from falling house prices, such declines will help make housing more affordable.
- The banking sector is well capitalised so the risk of a financial meltdown is very low.
- New Zealand will benefit from a pick up in tourism as international travel accelerates.
- The emergence from all that Covid-19 has thrown at us will provide some tail wind to the economy.
"There is, of course, the chance a recession does not eventuate but we think, given the way the world is evolving, households and businesses would do best adopting a prepare for the worst, hope for the best strategy.
"Whatever the outcome, we can say with some certainty that growth can only be moderate at best. If demand constraints don’t put a cap on the expansion then supply constraints definitely will."
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.