
The pricing intentions of Kiwi businesses "went the wrong way" in the latest monthly ANZ Business Outlook Survey.
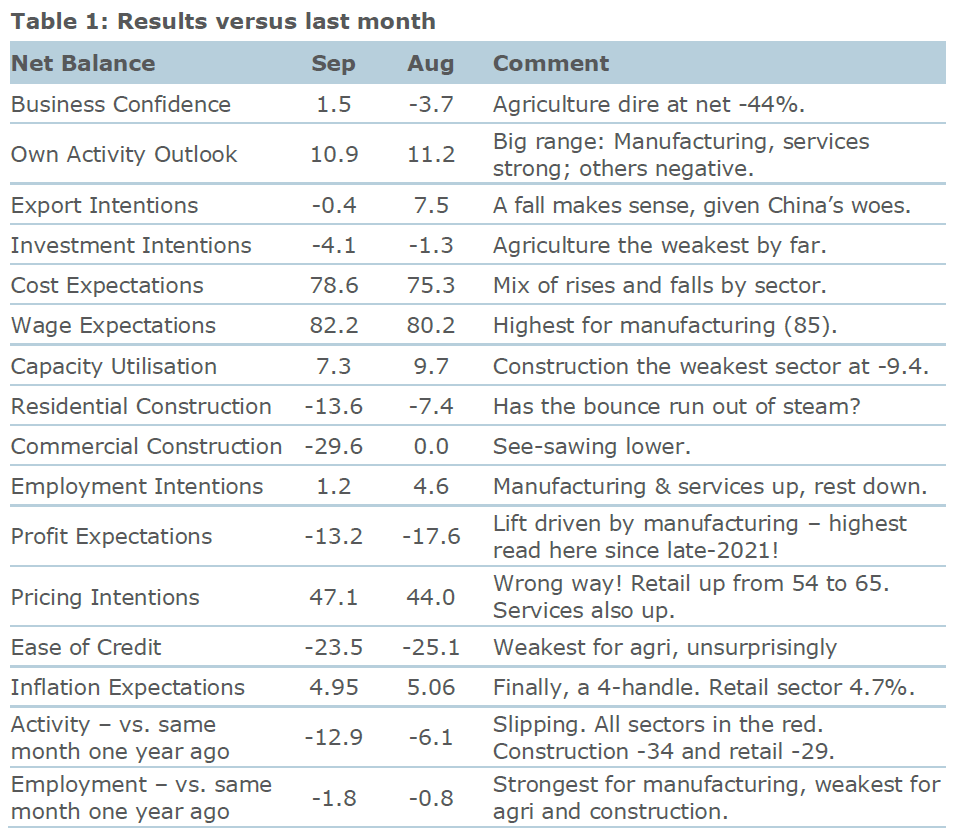
While overall 'headline' business confidence rose 6 points to a +2 reading in September, expected own activity was flat at +11 - and many activity indicators slipped a little, ANZ chief economist Sharon Zollner said.
"The New Zealand economy is certainly patchy, and the rebound in activity indicators – that’s been evident since the start of the year – may be running out of steam," she said.
"Inflation pressures are gradually waning in the big picture, but not rapidly nor in a straight line, and the jury remains out on whether it’s occurring fast enough to bring core inflation pressures down in a timely fashion.
"Cost and wage expectations remain very elevated, as do inflation expectations. Pricing intentions, one of the best inflation indicators in the survey, went the wrong way in the month, and both the exchange rate and oil prices have the potential to interrupt or halt downward progress."
Zollner said the outlook for the construction sector remains key for the inflation outlook.
"A meaningful decline in construction costs is part of the plan for getting inflation down. The proportion of construction sector firms expecting higher costs jumped to the highest in four months. The turnaround in the housing market is one to watch in this regard."
Zollner said the ANZ economists continue to expect that the Reserve Bank will conclude it has more work to do to be confident that inflation is on its way back to the target band, with a 25 basis point hike to the Official Cash rate - which would take it from the current 5.5% to 5.75% - expected in November.
BNZ head of research Stephen Toplis said there were "disconcerting signs" in the latest survey that inflation is not falling as fast as the RBNZ might like.
"Disconcerting this may be but not altogether surprising given the ongoing increases in input costs that the business sector is facing. Top of the list, in this regard, are surging oil prices," he said.
"Are these inflationary signs worrying enough to have the RBNZ suggest it might be raising interest rates again some time soon? We think not. And, anyway, with mortgage rates continuing to drift higher, monetary conditions are edging tighter anyway."
In the survey detail, Zollner said export, investment and employment intentions, and construction intentions, both residential and commercial, all eased.
"However, the falls were small, and the overall survey is best described as ‘mixed’. Also, economy-wide profit expectations lifted. Less helpfully, so too did cost expectations and pricing intentions, but only a smidgen, and inflation expectations eased slightly and recorded the first sub- 5% read since December 2021."
A net 65% of firms in the retail sector expect to lift their prices in the next three months, up from 54% in August, Zollner said.
This may be related to the fact that the retail sector now considers the lower level of the exchange rate to be a significant problem.
"The RBNZ prefers to look through tradable inflation and focus on the domestic inflation that it can influence to a much greater extent, but its ability to do so is contingent on inflation expectations being well behaved. It’s a case of ‘so far so good, but a long way to go’ in that regard."
Reported past wage increases(versus a year earlier) edged lower at 5.5%, Zollner said.
"On the other hand, expectations for wage settlements over the next 12 months ticked up from 3.7% to 4.0%, increasing for every sector except retail, which was flat," she said.
"The downward trend in expected wage growth is looking like it could potentially be stalling at this point, but it would be a mistake to read too much into one month’s data."
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.