

Here are the key things you need to know before you leave work today (or if you work from home, before you shutdown your laptop).
MORTGAGE RATE CHANGES
TSB has cut its 1, 2 and 3 year fixed rates. All rates are here.
TERM DEPOSIT/SAVINGS RATE CHANGES
Heartland Bank has trimmed TD rates for almost all terns to 18 months. All updated term deposit rates less than 1 year are here, for 1-5 years, they are here.
'SERVICE WITH A SLUMP'
The latest survey of the service sector is not good. Activity dropped sharply and slumped to levels last seen in June 2024 at the start of the recession. BNZ says there are 'clear warnings the New Zealand economy has hit a brick wall'.
LANDLORD INCOME GROWTH VANISHES
Residential real estate investors are seeing no rental growth for residential rents as they flatline. Tenants have plenty of properties to choose from keeping, a lid on rents.
PRESSURE ON GROCERY PRICES LOW & STABLE
The pace of supplier cost increases to Foodstuffs supermarkets remained steady in May, with the Infometrics-Foodstuffs New Zealand Grocery Supplier Cost Index showing an average +2.0% increase in what suppliers charged in May, compared to a year earlier. This is the third month it has been at this level. In May 2024 they were rising at a +2.9% rate.
PAID PARENTAL LEAVE
New parents can expect more support to take time away from work to care for their children from 1 July, with an increase to the maximum weekly rate of paid parental leave up from $754.87 to $788.66 per week (+4.5%). The minimum parental leave payment rate for self-employed parents will increase this year from $231.50 to $235 gross per week (+1.5%) to reflect the minimum wage increase on 1 April this year. Eligible parents can receive payments for up to 26 weeks.
NZX50 TURNS UP
As at 3pm, the overall NZX50 index is firmer far today helped by a chunky takeover bid. It is up +0.5% from Friday, up +0.6% for the past week. It is down -3.5% since the start of the year although up +7.9% from this time last year. Tourism Holdings surges on the takeover approach with other gains from The Warehouse, Kiwi Property and Contact. These are balanced by declines from Vulcan Steel, a2 Milk, Sky TV and Serko.
TWO-TRACK BUSINESS LENDING
Based in RBNZ Dashboard data, we have looked at the weakening bank appetite to lend for business purposes and find that after the scrum got screwed by Basel III, the desire cooled; and post pandemic two major banks quietly pulled back much further on supporting the business sector.
TURNING TOWARD INDONESIA
The Government has signed a new halal cooperation arrangement with Indonesia which is expected to create new opportunities for the red meat and dairy exporters. Indonesia is an important growth market, currently worth over $1.1 billion in exports last year. With a population of 280 million and a large middle-class Indonesia is a market getting added attention.
'REPEATED & SERIOUS FAILURES'
In Australia, ASIC today announced an Inquiry into ASX group, focusing on governance, capability and risk management frameworks and practices across the listed group.
THE DISPARITY EXTENDS
Chinese electricity production was only up +0.5% in May from the same month a year ago, maintaining the weak gains that started in November 2024. This is hard to square with their data claim that industrial production was up +5.8% on the same basis.
BETTER THAN EXPECTED RECOVERY
China also reported that its May retail sales rose a very healthy +6.4% from a year ago, well above the +5.0% expected and the +5.1% gain in April. It is a 15 month high. At face value this is a surprisingly strong gain.
STILL STRUGGLING
In their housing markets, China reported that new house prices fell -3.5% and the least year-on-year fall in a year. Month on month they says more gains are now showing. Prices for resales were down more year-on-year, and there are now major cities where they are rising.
SWAP RATES MAY FIRM SLIGHTLY
Wholesale swap rates are likely a touch higher today, and more at the longer end. Keep an eye on our chart below which will record the final positions closer to 5pm. Notice it isn't falling. The 90 day bank bill rate was down -1 bp at 3.30% on Friday. The Australian 10 year bond yield is up +8 bps at 4.24%. The China 10 year bond rate is down -4 bps at 1.64%. The NZ Government 10 year bond rate is up +8 bps at 4.64% and was up +5 bps at 4.59% in the earlier RBNZ fix today. The UST 10yr yield is now up +1 bp from this morning to 4.42%.
EQUITIES MIXED
The NZX50 is up +0.6% so far today on some local support. The ASX200 is unchanged so far in afternoon trade. Tokyo is up +0.9% in early Monday trade. Hong Kong is down -0.1% at its open while Shanghai is up +0.1%. Singapore has opened down -0.4%. Wall Street sentiment has turned positive and the S&P500 futures suggests it may open tomorrow up +1.1%.
OIL HOLDS HIGH
The oil price is up another +US$1 from this morning at just under US$74/bbl in the US, and just under US$75/bbl for the international Brent price.
CARBON PRICE HOLDS
The carbon price is up +25c at NZ$57/NZU on very few trades. The next official carbon auction is on Wednesday, June 18, with a $68 floor price. So it will fail. See our daily chart tracker of the NZU price for carbon, courtesy of emsTradepoint.
GOLD HOLDS HIGH
In early Asian trade, gold is up +US$5/oz from this morning at US$3435/oz and almost at the record high reached on April 22.
NZD STILL HANGING IN THERE
The Kiwi dollar is unchanged from this morning at 60.2 USc. Against the Aussie we are up +20 bps at just on 92.9 AUc. Against the euro we are up +10 bps at 52.2 euro cents. This all means the TWI-5 is now at 67.9 and little-changed.
BITCOIN STABLE
The bitcoin price is now at US$105,780 and virtually unchanged from where we were this morning. Volatility has been low at just over +/-0.7%.
Daily exchange rates
Select chart tabs
Daily swap rates
Select chart tabs
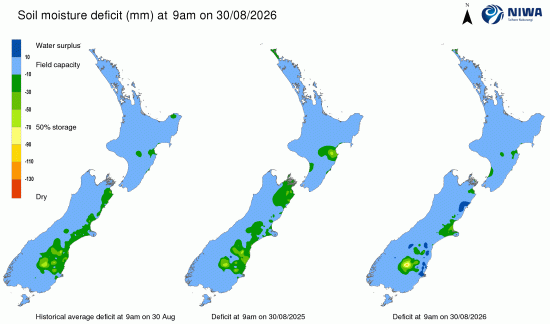
This soil moisture chart is animated here.
Keep abreast of upcoming events by 8ollowing our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.