
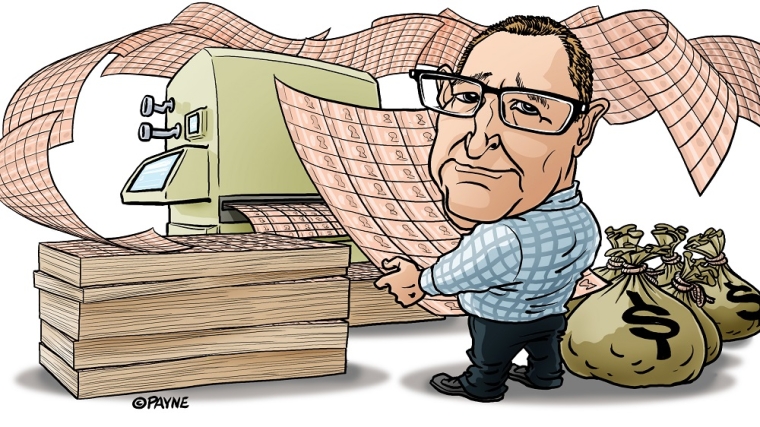
There will be little change but plenty to discuss when the Reserve Bank releases its latest monetary policy review on Wednesday (September 23).
At its previous review on August 12 the RBNZ did a significant amount of heavy lifting; raising the size of its QE (money printing) programme to $100 billion and more clearly signposting a move next year into negative interest rates. The August review was accompanied by a full Monetary Policy Statement. The central bank has shown a preference for making major policy changes during an MPS review - so that the reasons for the moves can be fully explained and outlined.
So, with so much done in the previous review, that leaves the statement on Wednesday as more than likely a 'placeholder', a reiteration of the key messages and general direction. Although, having said that, it is fair to say that under this Governor, Adrian 'shock and' Orr, the RBNZ has tended to err on the side of adventure with its movements and statements.
Of great interest for the markets will be whether there's any apparent evolution in this statement on the thinking over the negative interest rates. On August 12 Orr said the bank's Monetary Policy Committee had expressed a preference for considering a package of a negative Official Cash Rate (OCR) and a ‘Funding for Lending Programme’ (FLP) in addition to the current Large Scale Asset Purchase (LSAP) programme (QE). The Committee had instructed staff to prepare advice on the design of a package for deployment if deemed necessary, taking account of the operational readiness of the financial system.
The RBNZ smashed the OCR down to a new record low of just 0.25% (from 1%) in March as the Covid crisis hit in earnest. At the time the central bank pledged to keep the OCR at 0.25% for 12 months - IE till next March. But with the RBNZ having consistently since not ruling out negative rates, and with the August statement saying so implicitly that the RBNZ was now preparing for negative rates, the markets have been abuzz with speculation that the dropping of the OCR will happen earlier.
ASB senior economist Mike Jones, in a preview of this week's RBNZ review, said key for market watchers will be whether the RBNZ sticks to its forward guidance that the OCR will be left where it is until March next year.
"The guidance was reiterated again in August: 'the Official Cash Rate (OCR) is being held at 0.25% in accordance with the guidance issued on 16 March'. We expect that this line will broadly be retained, Jones said.
Markets are toying with the idea
"But the risk, if any, is that the guidance could be softened a little. Markets are already toying with the idea. Pricing is now consistent with a better-than-even chance of the OCR being reduced to zero by February (18 bps of cuts priced). Any softening in the Bank’s forward guidance would see markets move to front-load OCR cuts even further," he said.
Jones said the RBNZ was now busy consulting, investigating, and designing alternative monetary policy tools.
"Banks have been instructed to be ready for a negative OCR by the end of the year. Should all of this work turn up a package of tools that is both effective and operationally ready, and there is no material improvement in the economic outlook, there is a chance the Bank moves on additional policy easing before March of next year. In other words, we think the market is right to price a chance of earlier easing.
"Adding to the potential for an earlier move is the fact that the OCR announcement dates have shifted, with the next scheduled OCR announcement after the February MPS (February 24) not coming until April 14. In recent communications the RBNZ has explicitly linked the prospect of a negative OCR with a Funding for Lending Programme (FLP) which would see the RBNZ directly fund banks at the prevailing OCR rate. We remain of the view that a FLP scheme should be put in place earlier than March. The timely success of such a scheme partly rests on banks having a long enough lead time to factor such a programme into their funding plans."
'Slightly awkward'
ANZ chief economist Sharon Zollner takes a somewhat different view on the debate. She notes that the 12 month timeframe the RBNZ gave itself on the OCR is "slightly awkward" as the commitment was made at an emergency MPC meeting between official review times.
"The [12 month] deadline falls between a Monetary Policy Statement on 24 February, and a Monetary Policy Review in mid-April," she said.
"The market has therefore started pondering whether 'close enough' might be 'good enough', putting February in play, despite the RBNZ’s frequent reiteration of its guidance.
"In a macroeconomic sense, a few weeks is neither here nor there. However, in a strategic sense, it matters. The RBNZ will be concerned that breaching their word, no matter how trivially, would undermine the power of forward guidance going forward. As the recovery evolves, convincing the market that they won’t raise the OCR for a period come hell or higher inflation will be important for keeping long-term interest rates low. The RBNZ has taken a 'least regrets' approach to policymaking in recent times – we believe they will conclude that they would regret damaging their credibility more than they’d regret a few weeks of delay."
'Adamant in their need...'
But offering another perspective again are the Kiwibank economists, who said the RBNZ seem "adamant in their need to go negative", even if they made an early and effective use of the FLP.
"We believe the RBNZ has seen enough to warrant taking such a risk. Although we disagree, the RBNZ are likely to take the cash rate negative next year," they said.
The Kiwibank economists believe that if a central bank is to execute a negative interest rate strategy "it must be done with some bluster".
"A 75 bp cut [of the OCR] to -0.5% in February is expected, and more likely than April (or May), in our view."
Westpac chief economist Dominick Stephens said he expected that the RBNZ would simply state that design work on a package of negative interest rates and FLP is ongoing.
'There are tools...'
"The RBNZ will reiterate that if the economic situation warrants it, there are tools with which it could ease monetary policy. But there will be no signal that these tools are about to be deployed. Back in March the RBNZ committed to keeping the OCR unchanged at 0.25% for a year – we firmly expect the RBNZ to issue a reminder of that commitment...".
Stephens noted that the RBNZ's new MPC structure for making monetary policy decisions has been in place for a year and a half now, "and some clear patterns have emerged".
"The MPC has a predilection for making big bold changes to monetary policy, less frequently. The gradual approach is not favoured. When the need for a change in monetary policy has been identified, the MPC has tended to frontload the entire change into a single large move (this contrasts to previous RBNZ Governors, who tended to move part way and signal there was more to come). Given that a big bold change was made at the August MPS, it seems less likely that the MPC will make another change now."
Stephens said another pattern is that the MPC has never changed monetary policy at a review without a Monetary Policy Statement.
"Monetary policy has been altered at four out of six Monetary Policy Statements decided by the MPC, and there were two unscheduled changes during the most dramatic days of the Covid-19 epidemic. But of the four OCR Reviews or [Monetary Policy Reviews], one was cancelled and the other three have featured no change in monetary policy. This makes a change in monetary policy next week seem even more unlikely.
'No need to loosen'
"Finally, the recent period of stronger [economic] data means the RBNZ won’t see any need to loosen monetary policy further at this stage. In normal times, a period of stronger data could prompt a tightening of monetary policy, or at least a change in communications. But these are not normal times. The risks to the outlook are huge, swamping the significance of the recent stronger data. Also, the RBNZ is operating a 'least regrets' strategy – it is happy to take the risk of inflation and employment overshooting target, but wants to do everything possible to avoid major undershoots on either target. That means it will happily bank the news of stronger data rather than reacting to it."
ANZ's Zollner said this week's RBNZ policy review "is something of a placeholder", but the RBNZ might hope to put a little downward pressure on the long end of the interest rate yield curve via a dovish tone and a reminder that it now has the ability to take a more tactical approach to its weekly bond purchases.
"For the short end [of the curve], any weakening of the commitment to keep the OCR unchanged until March would certainly cause a flurry of excitement, but this is not our expectation."
The Kiwibank economists say their preference would be to 'unwrap' the RBNZ's 'package' of negative interest rates and the FLP - the funding for lending programme.
"We recommend unpackaging the deal, and going with what works without (major) consequences. Focus on the FLP now, and consider [negative rates] later. We have been banging the drum on a bank FLP as the next best tool in the shed. The good thing about the FLP, is the timing. The RBNZ has committed to doing nothing with the OCR until March 2021. The FLP could be started in November, to get the ball rolling. And if FLP is not enough..."
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.