
Here are the key things you need to know before you leave work today.
MORTGAGE RATE CHANGES
No changes to report today.
TERM DEPOSIT RATE CHANGES
BNZ has cut their RapidSave account so the most you can get in this incentive saver is now +0.4%. The Police Credit Union also cut TD rates today.
STILL VERY NEGATIVE, JUST LESS SO
Business confidence is still very negative, but at least it got noticeable less negative in September - and slightly less negative that in a preliminary survey. The same is true for how firms think about their own situation. Oddly, farmers and construction firm owners are the most positive about their own situation, but thing their own industries are in dire shape. One of those views is clearly quite wrong. Business inflation expectations are changing much, but more firms now say they will raise prices soon.
TRENDING DOWN
Residential building activity trending down now. The number of new dwelling consents issued in August is the third consecutive month it has declined. And that is being driven essentially by the Auckland apartment market which is down very sharply. But also house consents declined in all regions except Gisborne, Hawke’s Bay, and Taranaki. The saving grace is the market for attached housing (townhouses) with strong rises that are building on earlier gains.
TRENDING UP
The value of non-residential consents rise almost +20% from August 2019 with $659 mln in building consents last month. Factory buildings contributed the most to growth, closely followed by warehouses. This strong growth was concentrated in Auckland, and it accounted for all the non-res consent growth in the region.
MASSIVE INWARD PARKING
Household deposits rose +$15.8 bln in the year to August according to the latest RBNZ data. That is a record annual gain - and come despite banks offering derisory incentives to hold money with them. And almost all of this rise has come in the March-to-August period. 'Safety' in at-call accounts is the key driver with money in term deposits declining -$13.3 bln in the same time. So in essence, money flowing into at-call accounts in those six months has been a massive +$26 bln. More here.
IRD'S (FREE?) MONEY PREFERRED
Business lending growth was negative for the first time in nine years, other RBNZ bank debt data shows. In fact, in the five months from the start of April, financial sector lending to businesses has fallen +$5.5 bln. But that won't account for the popular uptake of the IRD-administered SME cashflow loan scheme which now stands at $1.533 bln, up from nothing in April.
WHAT CRISIS?
Meanwhile, the growth in housing debt is trucking on in a 'normal' manner, up +6.5% in the year to April, and marginally on the high side of what we have had over the past 5 months and almost the same as in August 2019. Also see this.
UDC REJOINS FINANCIAL SERVICES FEDERATION
UDC Finance, recently bought from ANZ by Japan's Shinsei Bank, is rejoining the Financial Services Federation. The forerunner of the lobby group for non-bank financial service providers was established in 1965 by UDC's general manager Otto Heymann.
GLOBAL DAIRY TRADE RISING
It is still early in the season, but Fonterra is reporting that their milk flows are up a strong +3.3% compared to last year, with 100 mln kgs/MS collected in August alone. They are also noticing exports from the US (+22%) and EU (+18%) are up strongly too, while imports by China (+18%), Latin America (+14%) and other Asia (+20%) are up strongly too.
GOLDEN WEEK STARTS
And a reminder for those of you who have business in China. Their Golden Week starts tomorrow and runs through to Wednesday next week. Most Government offices will be closed. And a truly enormous internal migration will get underway with 400 mln highway trips, 15 mln domestic flights, and hundreds of millions of train trips. But despite that they will be 20% less than in 2019 due to residual official travel restrictions still in place. (H/T ChinaSkinny)
DITTO IN AUSTRALIA
Residential building consent approvals were also out in Australia for August today and they were little-changed from August 2019. But that was an unusually low benchmark. Still house consents were up strongly (+12%), undercut by a big dive in apartment consents (-18%).
EATING THEIR LUNCH
New data released today by APRA shows how fast the banks are losing credit card business there (presumably to the upstart BNPL sector). In March 2019 banks had just a bit more than $40 bln in credit card 'credit'. In August 2020 that has fallen to $29.4 bln, 81% of which is held by the big four banks. It is not often you see big banks taking a shellacking from upstarts.
GOLD PRICE HIGHER
The gold price is trading at US$1895/oz today in Asian markets and up another +US$11 from this time yesterday. It is similar to the US$1897 at the New York close and much higher than London's US$1884 close last night. Silver is showing better gains.
EQUITIES UPDATE
On Wall Street, the S&P500 ended their session down -0.5% and retreating from some of yesterday's gain. The ASX200 is down -1.1% in late morning trade and the NZX50 Capital Index is down -0.2% in late afternoon trade. Shanghai opened down -%, Hong Kong is down -%. And Tokyo is down -0.3% in early trade.
SWAP & BOND RATES RISE
We don’t have the final data for today yet and if it is significant we will update it here. The 90 day bank bill rate is unchanged at 0.31%. The Australian Govt ten year benchmark rate is up +2 bps at 0.86%. The China Govt ten year bond is little-changed at 3.14%. Meanwhile, the New Zealand Govt ten year is up an unusual +6 bps at 0.52% and substantially higher than the earlier RBNZ-recorded fix of 0.46%. And the NZGB five year is still negative but less so at -0.02% pa. The US Govt ten year is up from this morning at 0.66%.
NZD FIRMER
The Kiwi dollar is much firmer this afternoon, now at 66.1 USc and up +½c since this time yesterday. Against the Aussie we are a little softer for a third day at 92.5 AUc. Against the euro we are at little-changed at 56.3 euro cents. That all means our TWI-5 is at up 69.5.
BITCOIN VOLATILE
Bitcoin is volatile today, falling earlier to US$10,641 but since jumping to US$10,823. That makes it +1.1% higher than this time yesterday.
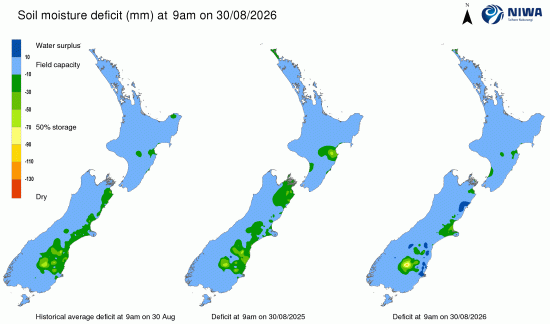
This soil moisture chart is animated here.
The easiest place to stay up with event risk today is by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.