
The latest ANZ Business Outlook Survey (for May) shows the New Zealand economy is struggling to keep up with demand - and cost and inflation pressures continue to build.
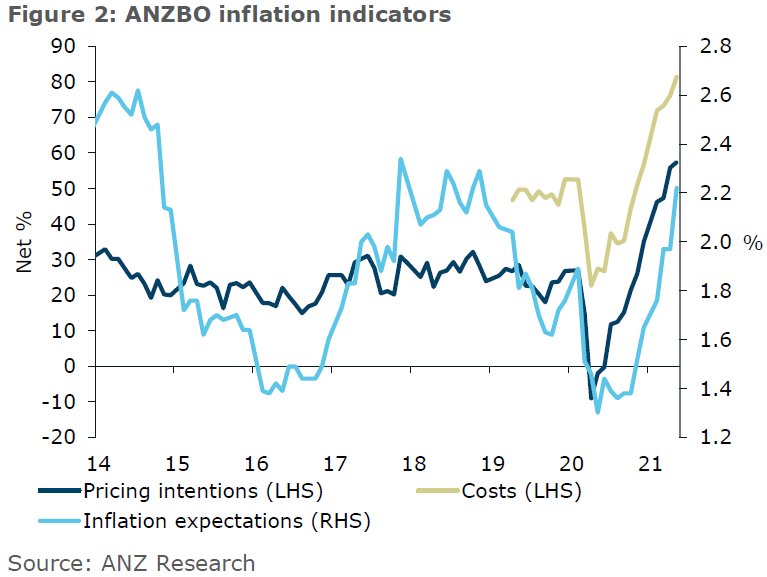
ANZ chief economist Sharon Zollner said inflation pressures continue to lift. The survey found cost expectations rose 5 points in the month to a net 81.3% of respondents reporting higher costs. A net 57.4% of respondents intend to raise their prices (prelim: 57.6%). General inflation expectations rose to 2.22%.
“Across the economy, cost expectations and pricing intentions stand out for being extremely high relative to history. Profitability remains relatively squeezed, hit by cost increases, and export intentions also remain lower than normal," she said.
Inflationary pressures "are not receding" but expectations remain close to the [Reserve Bank’s] target range midpoint of 2%.
"Expected costs are in the 90s for manufacturing, construction and agriculture, and not far off it for retail. The aggregate is being held down by services, where ‘only’ a net 72% of firms expect higher costs," Zollner said.
“Freight disruptions remain problematic.
"Compared to six months ago, a clear theme is that things have gotten worse, and the sectors that had initially been shielded from inward freight disruptions (particularly services) are now feeling it more."
Zollner said the New Zealand economy is struggling to keep up with demand. Cost and inflation pressures continue to build. Firms are having trouble sourcing inputs to production.
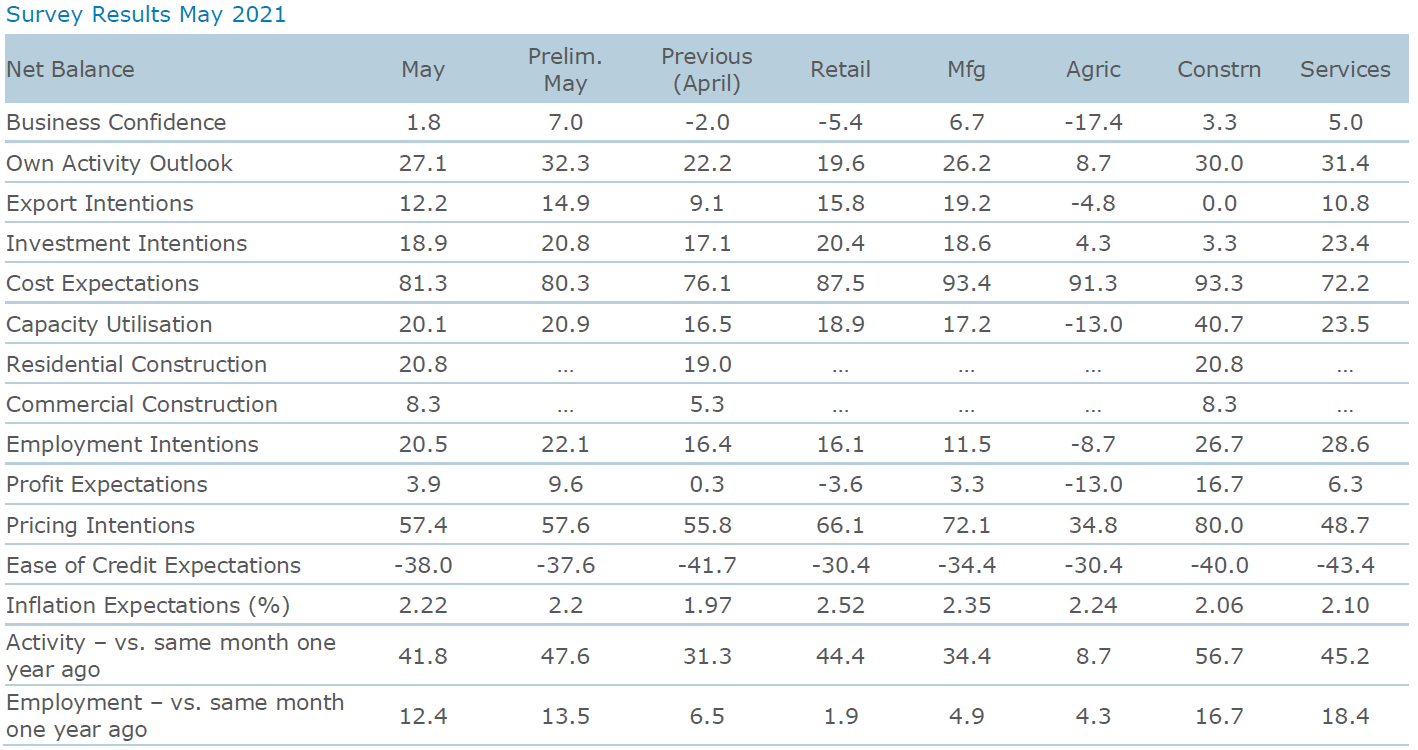
Compared to ANZ's preliminary May read, headline business confidence was 5 points lower at +2%, while firms’ own activity was also 5 points lower at +27%. Both are still higher than April.
“Business sentiment and activity indicators were lower in the late-month May sample, but all indicators for the month as a whole were still higher than in April.
“The bulk of the later responses were received the morning of Budget day. The details of the Budget were not known at that time, but it’s possible that uncertainty may have affected the numbers.
“We wouldn’t read too much into the drop in activity indicators in the second half of the month just yet, as it may have been influenced by Budget uncertainty. We won’t have to wait long to get a fresh read, with the preliminary June data due to be released on 9 June.”
Turning to the detail, compared to the month of April:
- Business confidence rose 4 points to net 1.8% (prelim: 7.0%).
- Firms’ own activity outlook rose 5 points to 27.1% (prelim: 32.3%).
- Investment intentions rose 2 points to 18.9% (prelim: 20.8%).
- Employment intentions lifted 4 points to 20.5% (prelim: 22.1%).
- Capacity utilisation rose 3 points to 20.1% (prelim: 16.5%).
- Inflation pressures continue to lift. Cost expectations rose 5 points to a net 81.3% of respondents reporting higher costs (prelim: 80.3%). A net 57.4% of respondents intend to raise their prices (prelim: 57.6%). General inflation expectations rose to 2.22% (prelim: 2.17%).
- Profit expectations rose 4 points to 3.9% (prelim: 9.6%).
- Export intentions rose 3 points to +12.2% (prelim: +14.9%).
- A net 38% of firms expect credit to be harder to get (prelim: -37.6%).
- Residential construction intentions rose 2 points to 20.8%. Commercial construction intentions rose 3 points to net 8.3%.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.