

By Roger J Kerr
The OCR is reviewed again by the RBNZ this Thursday and again there will be no change.
The moneymarkets have progressively moved the timing of the next OCR increase from March/April to July/September since the downbeat December MPS statement from the RBNZ and the negative September 2010 quarter’s GDP result just before Xmas.
Mr Bollard has clearly stated that the RBNZ will not be increasing official interest rates until they see firm evidence of a sustained pick-up in economic activity this year.
He will also know that that this approach runs a high risk of another monetary policy management mistake being made this year, due to the extreme lag in receiving GDP figures from Statistics NZ (i.e. March 2011 quarter’s data coming out in late June 2011).
By the time the RBNZ see proof of +3% GDP growth in 2011, the inflationary pressures will already be well advanced and they will be forced to increases official interest rates faster and in larger steps than what otherwise would be the case.
The art of monetary policy management is to pre-empt stronger growth (thus higher inflation risks) with pre-emptive adjustments to monetary conditions, as they take 12 to 18 months to have impact. The sad reality is that the RBNZ now have very little confidence in the accuracy of their own GDP growth forecasts, having been so far way from reality with their 2010 growth forecasts.
They are now waiting for hard evidence of stronger growth in 2011 before lifting the OCR.
They will find themselves well behind the 8-ball in this respect and will be forced to catch up in a hurry in the second half of the year. The risk and damage to the economy from this anticipated monetary policy mis-judgement will be via resultant exchange rate movements, not market interest rate movements.
Lifting the OCR from 3% to 5% later this year will only bring official interest rates in line with where the actual market price for borrowing and investing money (interest rates) has been for 12 months already - that is, 5%.
The banks’ combined cost of funds will not change due to the OCR increasing, their funding costs are already established at 5% to 6% and will remain there through this year. The OCR increases this year will have no impact on the domestic economy through investor/borrow/consumer behavioural changes, as their market interest rates will not change much.
The only thing a fast and furious OCR lift from June/July onwards will do is to attract speculative buyers of Kiwi dollars in the FX markets as the “NZ monetary tightening” headlines hit the global newswires. So the Kiwi dollar appreciates on its own accord in the second half of the year and the clobbered exporters wonder why the RBNZ allowed this monetary policy sloppiness to occur.
The RBNZ’s problem and predicament goes back to early 2009 when they slashed the OCR to 2.50% and then introduced the Core Funding Ratio regulation on the banks. The RBNZ should never have allowed the OCR to get so far below true market interest rate levels.
Yet again, the export sector is likely to pay the price for this monetary policy boo-boo.
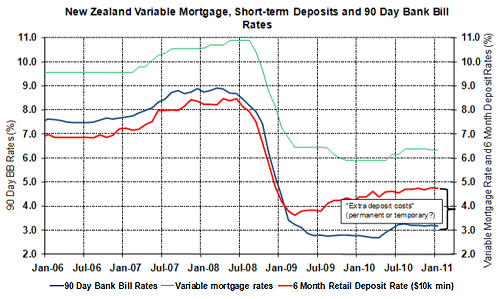
The blue lined (see chart below) 90-day wholesale interest rates (which track the official OCR rate) will increase in the second half of 2011. However the banks’ cost of funds (red-lined retail deposit rates) will not change too much as a result.
--------------------
* Roger J Kerr runs Asia Pacific Risk Management. He specialises in fixed interest securities and is a commentator on economics and markets. More commentary and useful information on fixed interest investing can be found at rogeradvice.com
No chart with that title exists.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.