
 By Roger J Kerr
With the NZD/USD exchange rate pushing 0.8500 again the debate has recommenced as to whether the NZ dollar is moving from a “risk and commodity” driven currency to a “safe haven” currency and attracting new buyers as a consequence.
The Kiwi dollar’s close correlation with the AUD has meant a rising currency value when global investors are in “risk on” mode and buying shares and commodities aggressively.
The appetite to buy “risk, growth and commodity based” currencies, such as the Kiwi dollar, increases when investors are in a bullish mood. The AUD (thus Kiwi alongside it) is also viewed as a proxy currency to buy when global investors cannot buy less free-floating Chinese/Asian currencies in speculative trades when they want to go “long Asia” on positive economic news for the region.
As has been the case over recent years, the AUD and NZD appreciated last Friday when strong Chinese GDP growth data was released. I believe the global “risk-on” and “growth/commodity” factor for the Kiwi dollar stills holds, however I am not so sure that we are also becoming a permanent safe haven currency that attracts global funds when other markets start falling apart.
To become a true safe haven currency like the Swiss France and Japanese Yen, the Kiwi would have to be appreciating when global share markets are tumbling and international investors are in “risk-off” mode. It is very difficult to see this happening.
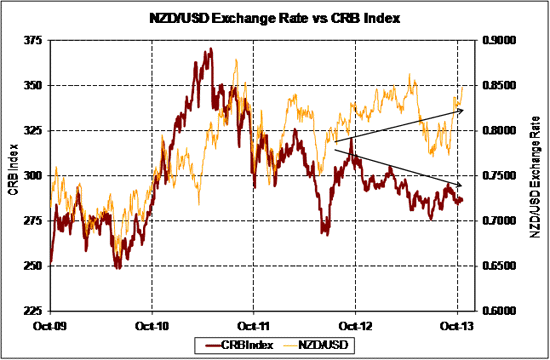
What has been interesting about the recent NZD/USD gains from 0.8100 to 0.8500 is that the appreciation has occurred when global commodity prices (the CRB Index) have not increased at all.
The CRB Index has been static around 286 as oil prices have retreated on reduced Syrian tensions and metal prices have moved sideways as China has plenty of inventories stored up.
The historical NZD/USD correlation to the CRB Index is a strong one and the recent divergence does not appear too permanent to me. On the view that commodity prices are not about to shoot higher, the Kiwi is overdue for a downward correction.
The higher NZD/USD rate has certainly been due to a weaker USD against all currencies following the tapering postponement from the Fed Reserve a month ago (USD money printing continuing at the same rate) and the generally unsatisfactory resolution to the US fiscal fiasco in recent weeks. I expect to see the FX markets to now return to focussing on US economic data results as determining USD direction after the US monetary and fiscal negative events of recent weeks.
The USD Index has dropped to 79.6 and the EUR/USD rate is near to $1.3700 which suggests the US economy is doing poorly and Euroland is an economic powerhouse. Nothing could be further from reality and positive US jobs data this week should reverse the weaker USD direction and pull the NZD/USD rate lower.
Local USD exporters who operate continuous and rolling 24 month currency hedging horizons have been well protected against this unexpected NZD surge to 0.8500. USD exporters should be using their hedged to convert all receipts at this time and be patient to target the 0.8100 area before replacing any of that hedging.
-----------------------------------------------------------
To subscribe to our daily Currency Rate Sheet email, enter your email address here.
No chart with that title exists.
Roger J Kerr is a partner at PwC. He specialises in fixed interest securities and is a commentator on economics and markets. More commentary and useful information on fixed interest investing can be found at rogeradvice.com
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.