By David Hargreaves
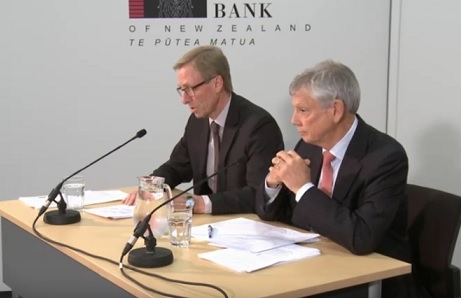
There's a bit of both good news and bad news in Finance Minister Steven Joyce's appointment of Grant Spencer as Acting Reserve Bank Governor for six months beginning later this year.
It is an adroit move that neatly sidesteps potential complications caused by the current Governor Graeme Wheeler's term expiring just three days after the September 23 election.
The way is now clear for the Reserve Bank board to take out a clean piece of paper after the election and start scribbling down potential names for a new Governor. The preferred choice can then be presented to the incoming Finance Minister for their approval. And then later, the Minister can sit down with the new appointee and nut out a new Policy Targets Agreement.
That's all good.
Inertia risk
Less satisfactory is the around 14-month period the RBNZ faces being headed up by people who know they won't be there for long. In my view there will be a risk of severe inertia within the central bank, notwithstanding that the day-to-day running will be in capable hands. But new initiatives come from people new to a job and people who know they are going to be there for a while - not generally from those marking time, no matter how professionally they might go about that.
Whether by design or accident, I think this hiatus at the bank does give this Government, followed by whoever forms the next Government, some time to have a good look at the RBNZ, how it's structured, how it operates and what form the PTA takes.
The RBNZ's governing legislation is the Reserve Bank of New Zealand Act 1989. There's a bit of a clue to a problem in that title. Yes, the date. Quite a long time ago. The Act has done us proud, I think, but a fairly substantial review and overhaul is now overdue.
And then there's the interwoven issue of the Policy Targets Agreement.
Here's the relevant blurb from the RBNZ's website:
The Reserve Bank Act requires that price stability be defined in a specific and public contract, negotiated between the government and the Reserve Bank. This is called the Policy Targets Agreement (PTA). The current PTA, signed in September 2012, defines price stability as annual increases in the Consumers Price Index (CPI) of between 1 and 3 percent on average over the medium term, with a focus on keeping future average inflation near the 2 percent target midpoint.
That's deliciously uncomplicated. But does pure inflation targeting as the key instrument of monetary policy still 'work' in the way it worked so well in the past? It is certainly an issue that should be getting high-level consideration. Of course, if the Government changes late this year, Labour's previously indicated it wants the PTA in future to include employment.
The way in which RBNZ interest rate decisions are made is another point of contention.
Officially, movements of the Official Cash Rate are made by the Governor. Wheeler has attempted to communicate (probably without real success) the idea that he makes the decisions very much collaboratively as part of a governing committee.
I think, however, a lot of people would welcome an official move to something more like the US Federal Reserve's committee structure, making it very publicly clear that these decisions are not being made by one person.
Twin roles cause confusion
The other thing that I very much believe needs clarifying is the Reserve Bank's twin functions of on the one hand monetary policy and the other Financial Stability. The latter role has become much more significant since the 2008 Global Financial crisis.
The two roles now cause considerable confusion - witness the number of times journalists who should know better asking financial stability questions at RBNZ monetary policy briefings and then asking questions about the dollar (a monetary policy issue) at financial stability briefings.
Aside from the confusion, the two roles have often seemed to get in each other's way more recently. For example, does the RBNZ cut interest rates (monetary policy) to get the value of the dollar down, while at the same time risking the housing market (financial stability) taking off again?
It's a conflict of interest that I think would benefit from at least some effort at a more formal demarcation of the roles. I know the RBNZ would probably strongly resist any formal, structural separation of its two roles - such as by creation of a new body to manage financial stability. We are however, well past the time when the issue should at least be properly examined.
So, those are just a few things I think the Government or Governments could be looking at over the next year. It's an ideal opportunity.
An accessible Governor
And then just finally - on the next fulltime Governor. We need someone comfortable in public speaking and who can relate easily on the general public's level. Years ago I thought Don Brash was always pretty good at that. The Governor has to be visible and accessible and able to communicate confidence.
I recall very, very many years ago attending what I might loosely term a social function, with several colleagues from the old Evening Post newspaper in Wellington. The slightly full-of-ourselves financial journalists gathered in one end of the room talking pretentiously and loudly about the economy. Alcohol was being consumed.
I became aware of an interloper; a burly young man in black T-shirt and jeans, heavy duty footwear (possibly DMs), looking like he had just come out of the front row of a scrum.
The young man silently observed our (ill-informed) analysis of the economy while standing at the edge of our group and then, to my surprise, began to proffer a view. Eloquently and without pretension he proceeded to give a dissertation that, without any intent on his part to be unkind, completely wiped the floor with our limp arguments.
The guy was as sharp as a tack and what he didn't know about economics hadn't been written. I had just met the now chief executive of the NZ Super Fund. For what it's worth, I think Adrian Orr would be a great choice as Governor.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.