
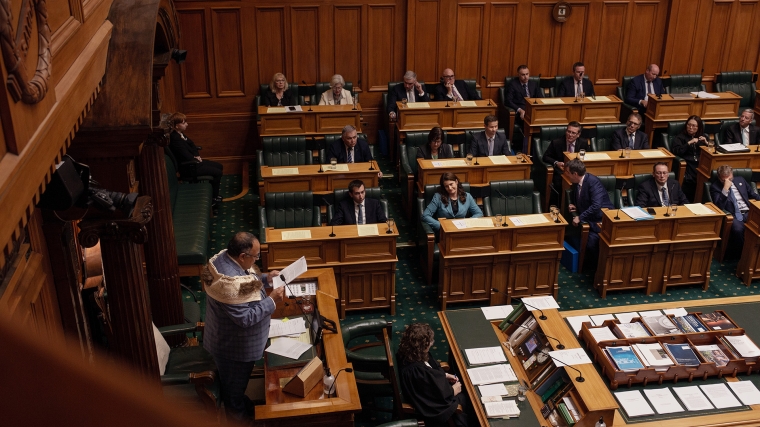
The coalition government has passed a bill removing the maximum sustainable employment objective from the legislation governing the Reserve Bank (RBNZ).
The RBNZ will now legally pursue one main economic objective: “achieving and maintaining stability in the general level of prices over the medium term”.
It will retain its financial stability objective and other central bank functions, but the economic objective of “supporting maximum sustainable employment” has been removed from the Act.
This vote reverses a change made by Labour in 2019, alongside other Reserve Bank reforms.
Finance Minister Nicola Willis, who introduced the bill, said removing the dual mandate was a “highly symbolic and important act” that would help to fix the cost of living crisis.
She also seemed to suggest the dual mandate was responsible for the recent bout of inflation.
“When the dual mandate was added in 2019 it undid success in the past and, as we've seen, inflation in recent years has been consistently well above the Reserve Bank's target…”
There is no evidence the RBNZ’s employment objective contributed to inflation, which was triggered by a supply shock that occurred during the covid-19 pandemic.
However, the Treasury advised that removing the employment mandate could improve public perception of the bank and therefore inflation expectations.
Chlöe Swarbrick, a Green Party MP, said the bill was “virtue signalling” since it would make “absolutely no difference whatsoever” to how the RBNZ set its monetary policy.
Grant Robertson, Labour’s finance spokesperson, said it was an “unnecessary, short-sighted bill” that would worsen the overall economic well being of New Zealanders.
Speaking after the vote, Willis told reporters she was “delighted” to have passed her first bill as Minister of Finance.
“I think this bill sends a very clear message about our government's war on inflation. And we're very pleased that the Reserve Bank now has a clear single mandate to bust inflation”.
She said it could be considered a successful law change if it helps to build confidence in the central bank’s focus on bringing down inflation.
Coalition politics
National’s coalition partner, New Zealand First, has previously been supportive of having the central bank pursue wider economic goals. The party voted in favour of Labour's reforms in 2018.
In 2012, party leader Winston Peters put forward a members bill which would have added export growth and employment to the RBNZ’s remit.
This would have fixed “fundamental flaws” in the Act, including the “myopic focus on price stability, to the exclusion of other critical economic indicators”.
NZ First, as part of the coalition government, voted in favour of the bill passed on Wednesday but did not give any speeches in support.
Willis told Parliament that returning to a single mandate would not require the Monetary Policy Committee to “discount the impacts of monetary policy on the real economy”.
The Act Party was highly supportive of limiting the RBNZ’s remit and wanted the coalition government to make further changes to its governance.
Some of Willis’ comments in Parliament during the debate did not sound promising for other suggestions included in the coalition agreement between National and Act.
One of these was to set a specific time limit for the RBNZ to get inflation back on target. However, Willis committed to retaining the flexible target during the debate.
“I want to assure the member, Chlöe Swarbrick, that we will retain the flexible inflation targeting regime under which the response of the Reserve Bank to inflation is tempered by considering the impact on other factors in the real economy,” she said.
Elsewhere in the debate, Willis said: “Flexible inflation targeting, whereby the Monetary Policy Committee has regard to the impact of monetary policy on the broader economy when determining how quickly to return inflation to target has been central to New Zealand's successful inflation targeting regime for many years”.
The finance minister also said she would publish a revised remit and charter for the RBNZ, which reflected the change in legislation and retained the flexible target.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.