Beef+Lamb NZ's mid-season report on the red meat and wool sectors is a detailed assessment and puts figures to what most farmers already know. While stock prices have fallen, they are still above the five-year average but with high inflation farm profitability is looking at falling by around 30%.
Of the three main meat products covered (lamb, mutton and beef) mutton has taken the heaviest hit with a drop in returns of -23%. This is likely largely due to the elevated prices that have been achieved previously due to demand from China where mutton got some favour as a substitute for the pork shortage due to African swine fever. Pig numbers have returned to pre-ASF levels and unfortunately mutton has not been able to diversify its sales as well as lamb and beef have. The result is the annual average mutton price for the 2022-23 season is forecast at 430 cents per kg, down -23% on 2021-22, and -11 per cent below the five-year average.
Lamb which has been able to move to a wider spread of markets has been able to ‘cherry pick’ and as a result although still down -12% on the previous year at 760 cents per kg for 2022-23, but is +2% above the five-year average. Beef has out-performed sheep meat although still -6.1% below the previous season with estimated 2022-23 average annual price is 611 cents per kg for P steer/heifer (270-295kg), 405 cents per kg for M cow (170-195kg), and 602 cents per kg for M bull (270-295kg).
All these projections are predicated on the Kiwi dollar being at 63 US cents. Currently it is at 61.5 US cents and has been tripping along at around the 63 US cent mark average since December 2022 (give or take a cent). At this level New Zealand exports are seen to be competitive against international competition.
Lamb demand whilst still strong(ish) and is expected, along with all meats, to strengthen in the second half of the season is perhaps a little disappointing given the decrease in numbers. Sheep numbers in general are down -2.5% in June compared to the same time in the previous year (25.15 million). A bit more surprising given the swing to cattle that has been taking place in the last decade is the number of beef cattle at 30 June 2022 is estimated at 3.84 million, down -3.1% on the previous June. Beef cattle numbers have ranged between 3.72 and 3.97 million for the past five years.
Perhaps the increase in forestry areas is starting to impact on all livestock class numbers?
The number of dairy cattle at 30 June 2022 is also estimated to have decreased -4.3% to 5.92 million. Wool, worth a minor mention, shows that shearing costs outweigh returns (except for the finer and Merino flocks) and there is little light to see any great turn around here. Wool is making up about 5% of total farm returns.
The fall in prices however, is only one side of the coin and it is the lift in costs that will be of greater concern to farmers as this is more difficult to control. Fertiliser, lime, and seeds expenditure have shown increases +6.1% on the previous year and despite farmers reducing these inputs they still make up around 19% of the total farm expense bill. Over all the largest increases are forecasted for interest, fertiliser, fuel, shearing and wages. No surprises there.
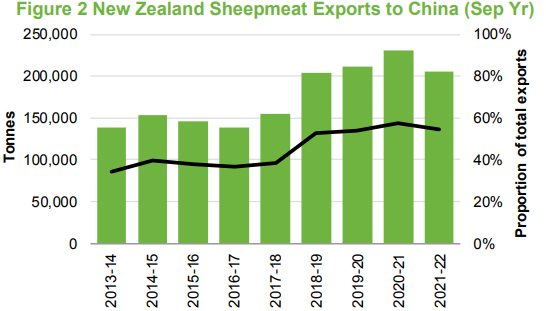
Despite some flattening off in proportion of total exports, largely as a result of Covid -19 lock-down policies, China is still and likely to remain the dominant destination of sheep meat. Total sheep meat consumption in China has lifted around +2.3% in the past decade because of these factors. Despite this growth, sheep meat remains a small, niche market, making up only 4% of total consumption.
Source: Beef + Lamb New Zealand Economic Service, New Zealand Customs
While New Zealand numbers of lamb are likely to continue to decline, in Australia largely due to wetter seasons (as opposed to droughts) production is being seen to lift. The Australian sheep flock is estimated to expand to 79 mln head, its highest level since 2007. Lamb slaughter is forecast to reach 22.6 million in 2023, a +2.7% increase on the previous year. The average carcass weight is also forecast to increase in 2023.
Internationally, sheep meat production is forecasted to grow at +1.6% while demand increase at +1.5% annually. The growth in production, apart from Australia, is being seen to occur in lesser developed countries and regions and therefore not a great supply threat to New Zealand producers.
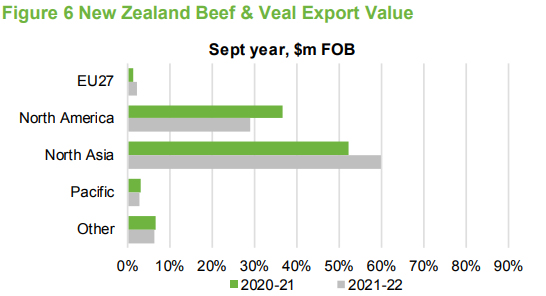
One of the conditions that may aid increased returns for beef and especially from China is a recent outbreak of “Mad Cow Disease” (BSE) in the Brazilian herd. For New Zealand beef exports China has been outperforming the US in term of value and volume in recent years and this is seen likely to continue.
Source: Beef + Lamb New Zealand Economic Service, New Zealand Customs
Demand for beef has not had the same drop off as has been experienced by sheep meat although there are more competitors in the market. China is (as always) the world’s largest importer of beef. Globally production is expected to fall -1% in 2023 and with the Ukraine war push up feed costs. Both issues should help New Zealand beef remain competitive.
Still to be factored into the forecasts are the impacts of adverse weather, the heavy rain events and disruption to farm management and more in the North Island and the prolonged dry period which has impacted on the Southland – Otago region. None of these are going to be positive.
The only good in aspect is that farmers have come out of good recent returns and looking ahead returns also look likely to be improving. The big things to watch for are the Kiwi dollar relativity, Russia and perhaps the Brazilian BSE outbreak.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.