It’s no secret that China is the main driver of global dairy prices; in fact they have a major impact upon the price of all traded food internationally. This should come as no surprise given it is the second largest population (as a country) and has a growing middle class.
In fact, at the moment it is the largest middle class, depending upon the criteria used to measure affluence. Some say within China say it is over 707m (50%) considered to be in the middle class. Perhaps a more realistic measure is that from 2002 -2018 the numbers joining the ‘middle class’ is said to have averaged 27% per year to have gone from 1% to 25% and climbing with an expectation that it will reach 40% of the total population by 2030. The graph below (from 2020 data so a bit speculative for the current time period) gives a good breakdown of where the money is.
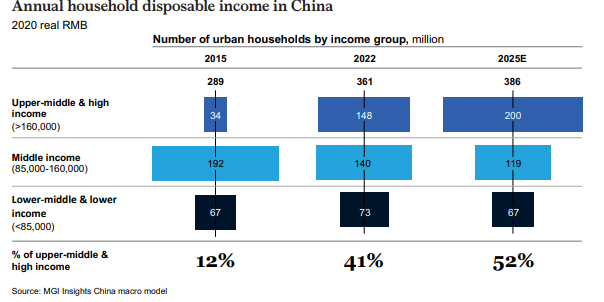
Never mind the numbers, it is clear that it is large and still has plenty of growth ahead. Despite the recent downturns including in China there is still growth there, lower than previously but it appears to be ahead of most OECD nations as a percent of GDP.
Food spending in particular is up 4.8% (in the first half 2023) over the same time last year and up 15.8% over 2021. The numbers below relating to infant formula are a little more circumspect and the reduction of “local brands” while up on 2019 is down for the first half of 2023 is a little surprising given the drive to ‘buy local’ occurring in China.
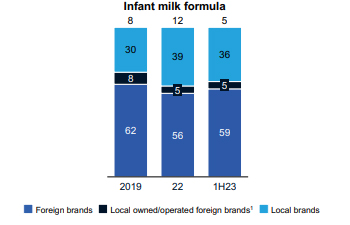
It may just be that the snapshot is too small a period to get an accurate trend. Reports do say that Chinese consumers are becoming more frugal in spending and practising “smart shopping” I.e. going for the best value.
One area that could be of concern now and going into the future is the Chinese demographic make-up. We know that the population is starting to fall driven by reduced births and the graph below also shows that it is being compounded by the ‘over representation’ of males around the age of when couples are having children.
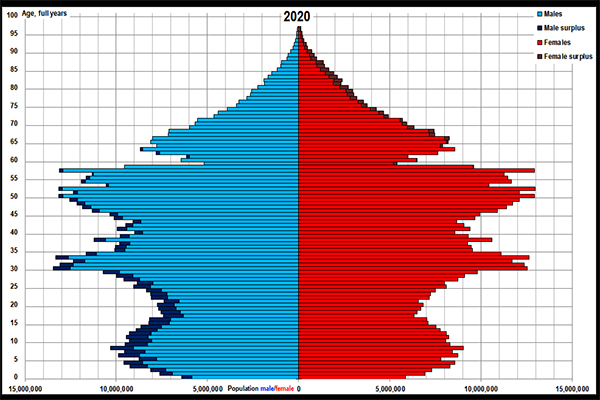
Source: Wikipedia
This out of balance make-up looks like it may continue for another decade or so yet. Looking at this data it would start to make you wonder if relying on infant formula as the future income earner for New Zealand dairy is the correct product mix.
The other area to watch in China is its own domestic dairy production. We know that it is increasing and that consumers are now having more confidence in purchasing it.
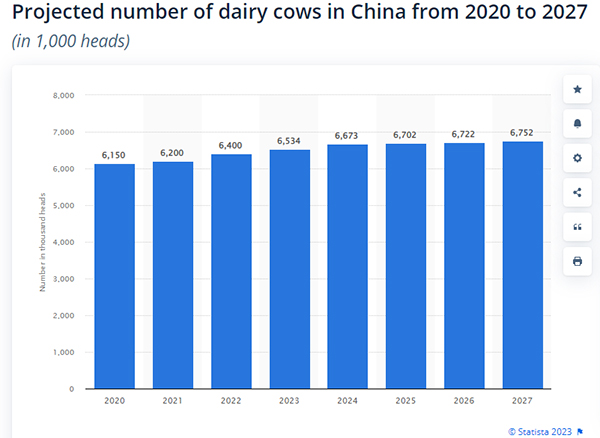
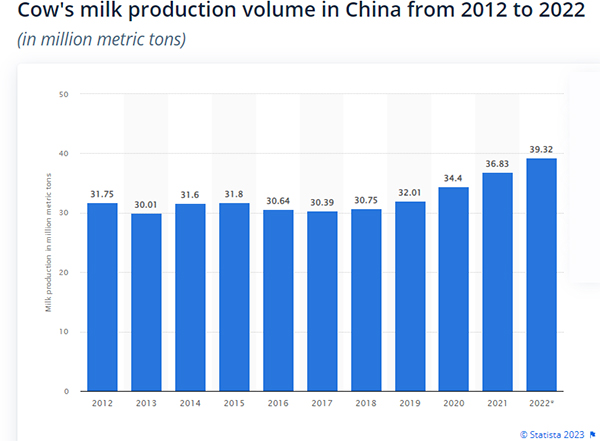
Along with the additional cow numbers, production per cow is also lifting and despite being flat(ish) for a number of years is now starting to climb, judging by the gross figures, as production is increasing at a faster rate than cow numbers. In the years 2020 to 2022 cow numbers increased 4%, while milk increased over 14%. Even allowing for some lag time a substantial jump.
In 2021 Reuters reported “Spurred on by near record highs for raw milk prices and government subsidies, just over 200 new Chinese dairy farm projects were announced last year, according to consultancy Beijing Orient Dairy. Its analysis shows that 60% of the new projects have set their sights on 10,000-plus cows and in total the plans call for some 2.5 million cows - roughly half of China's current milking herd - to be added in the coming years”.
Looking at the projected cow numbers above it doesn’t yet appear that these numbers are being captured. Reuters have also said that (only) 70% of China’s milk demand is being met by imports. They felt this was still a wide gap and as the AHDB graph below shows a healthy upward trend. Although the 2023 numbers are not included and with them along side 2022 it may not look so healthy.
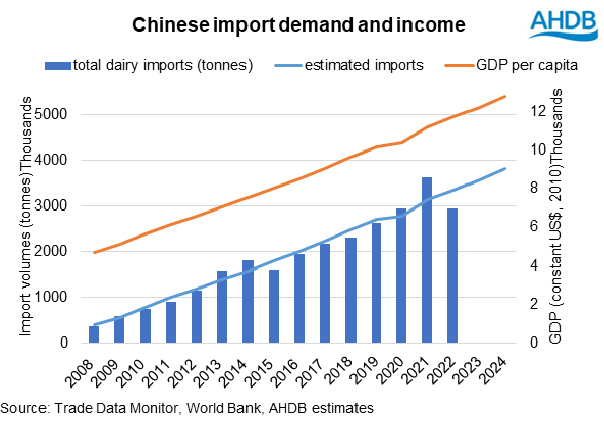
Looking at these numbers and projections, it does appear that there will be a medium-term uplift in prices, mainly because world production is flat (see below).
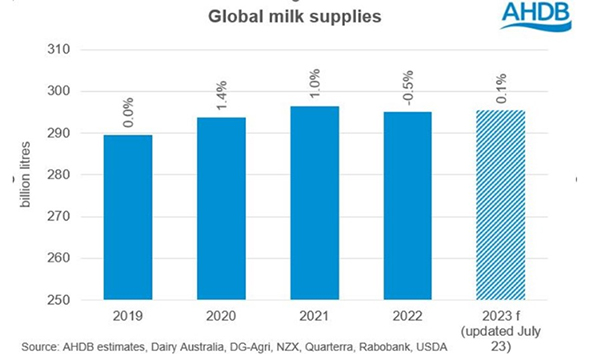
But with China the only country to be really increasing their volumes, although last year in the Dairy Exporter there was a report of milk dumping occurring due to over-supply domestically. This is one of a number of mixed messages coming out about Chinese demand as earlier this year a report showed a steady increase in consumer consumption.
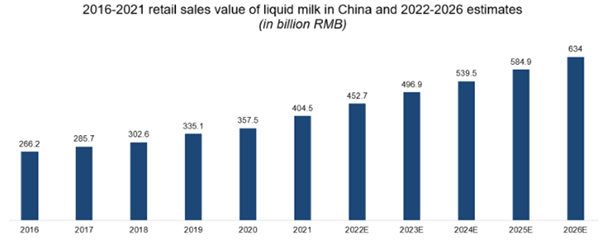
So this is why “medium term” things should be positive. Beyond that I believe questions need to be asked, “what is the future for dairy?”.
China is already the world 3rd largest producer and they have shown they can manage quality control to the point where they satisfy their domestic consumers. So, it may only be a matter of time before they start exporting, certainly their rate of imports must be likely to reduce.
Probably one big question will be around their costs of production. New Zealand should have an advantage there growing grass, but with a possible $8.40 per kg MS cost for many even that has to be questioned.
Northern hemisphere countries should reduce first with higher costs but with governments propping up food production, even that is questionable. So, dairy beyond 2030 may look quite different to today. Just don’t ask me what that will be.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.