By Allan Barber*
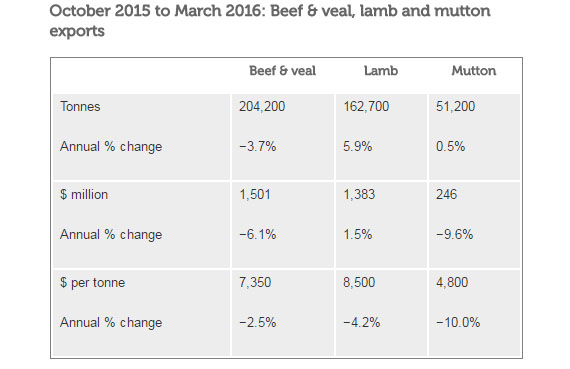
B+LNZ’s Economic Service has analysed meat exports for the first six months of the 2015/16 season and the figures show what might have been anticipated.
The weaker NZ dollar did not decline enough to compensate for lower beef shipments and a fall in the overseas market prices for both beef and sheepmeat.
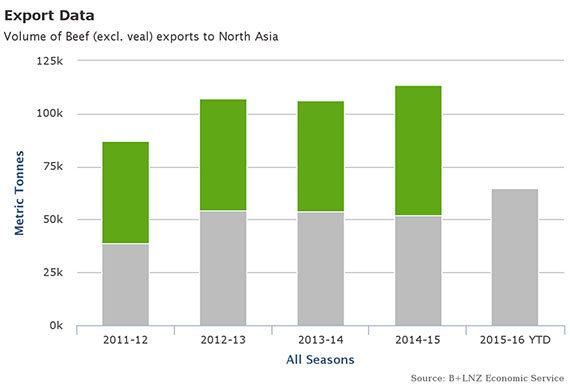
Beef shipments were down 3.7% while the value fell 6.1%, although the entire drop happened in the second quarter; chilled beef exports were well ahead of the first quarter twelve months earlier with sales to North Asia showing a 55% increase. Exports to China and Taiwan were responsible for a 24% increase to North Asia for the six month period as a whole.
The overall decline was almost entirely due to lower tonnage and value of frozen beef exports, particularly to North America.
Lamb export tonnage rose by 5.9% because of the early processing season with sales to North Asia and Europe rising by 11% and 7.2% respectively, with the increase attributable to chilled lamb which represented 29% of total tonnage compared with 27% a year earlier. The average value of lamb fell by 4.2%, but this was cushioned by the weaker dollar by about 10%.
Mutton shipments were slightly ahead of the previous year, although the average value was down by 10%, with all regions showing a weaker trend. North Asian exports were well down, but this decline was offset by increased sales to Europe, South Asia and North America.
The total value of meat exports was 4.4% down on the previous year with the total tonnage marginally up, the difference being due to the fall in market prices cushioned by the weaker NZ dollar.
The outlook for the second six months does not look as favourable as the first half for several reasons: the volume of chilled lamb will be down considerably with no Christmas or Easter trade, prices have fallen across the board since the end of 2015, and the total lamb kill will be approximately 1 million down on last season in spite of the larger than usual pre Christmas processing volumes.
The word out of the far south suggests this will not be a vintage profit year for the processing and exporting sector, so for the time being at least the figures for the first six months may be about as good as it gets. A rise in global market demand and a further drop in the value of the NZ dollar will be necessary components of any improvement.
To subscribe to our weekly Rural email, enter your email address here.
Farms For Sale: the most up-to-date and comprehensive listing of working farms in New Zealand, here »
Here are some links for updated prices for
- lamb
- beef
- deer
- wool
M2 Bull
Select chart tabs
*Allan Barber is a commentator on agribusiness, especially the meat industry, and lives in the Matakana Wine Country. He is chairman of the Warkworth A&P Show Committee. You can contact him by email at allan@barberstrategic.co.nz or read his blog here ». This article first appeared in Farmers Weekly and is here with permission.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.