

Here are the key things you need to know before you leave work today.
MORTGAGE RATE CHANGES
None to report today.
TERM DEPOSIT RATE CHANGES
None here either. But BNZ raised the rates on some savings accounts, including Total Money.
DETERIORATION
In February 2020 (pre-pandemic) we had a +$551 mln trade surplus. In February 2021 it fell to +$205 mln in the month. But in February 2022 we turned to an unseasonal deficit of -$385 mln, a shift of almost -$600 mln in one year, and taking the twelve month deficit to -$8.4 bln a new all-time record 'high' (depth). That is -2.4% of all annual economic activity (GDP). This is not good but it is nowhere near the worst performance in the year to February 2006 when it hit -4.6% of GDP. The February 2022 performance is the worst in 13 years. The cost of food imports and pandemic protection supplies are being blamed for the deterioration.
BUILD-TO-RENT OK
The Government said that NZ does welcome foreign 'investment' in housing but only for in purpose-built rental housing. Agency LINZ has issued guidance clarifying that while foreigners can't buy existing houses, they can build rental housing - and become landlords. But they still can't deduct interest as a business cost.
SUPPLY DOWN, DEMAND UP
Fonterra is reporting that hot, dry weather in the first weeks of February across most of the country before being interrupted with drought breaking rain through the middle of February impacted feed availability in many regions. Milk collections were down -7% in the month compared to the same month a year ago, but recovered quickly in the second half of the month. All markets reported higher demand in the month.
SME COST PRESSURE
Xero warns rising wages are a pressure point for small businesses that will ultimately drive up the cost of operations and will likely contribute to inflation if not matched by increased productivity.
LONG PIPELINE
The latest building consent data shows there is a huge pipeline of work for construction sector despite the economic uncertainties. The total value of all building work consented last year was $6 bln higher than pre-Covid. Only part of that can be explained by inflation.
WHEN $1.2 BLN ISN'T ENOUGH
David Hargreaves analyses the latest Air New Zealand capital raising and finds it is a little light and they may need to find more money later. The $1.2 bln capital raise might be the largest of its kind in either New Zealand or Australia in 2022.
FARMER SENTIMENT DIVIDED
New Zealand’s primary producers remain divided on the prospects for the agricultural economy in the year ahead, with a growing range of farmer concerns weighing on farmer sentiment, despite strong prices and demand, according to the Rabobank Rural Confidence survey.
DEBT IMPULSE SLOWS
Mortgage debt rose less than +$1.5 bln in February from January to $334.1 bln (and of course a new all-time record high). 98.4% of it is with banks. But February's rise was the second smallest monthly rise since June 2020. The year-on-year rise is now 'only' +9.5% the 'slowest' percentage rise since February 2021. Full analysis here.
COMPANIES GET A RENEWED TASTE FOR DEBT
Bank lending to businesses is picking up pace however, growing +7.6% in a year and that is the fastest pace since October 2016 and matching the pace in July 2019. The growth was +$1.6 bln from January, the biggest monthly rise since October 2019 and taking business debt to banks to $125.4 bln and a new all-time record high.
FUNDS FLOW INTO GOVERMENT COFFERS
Household term deposit balances rose for the sixth consecutive month in February (S40) to $83.9 bln, and the highest level since March 2021. But overall household bank account balances are stable with a shift out of low or no-earning accounts starting to happen again. The total of all bank account balances rose almost +$3 bln to $421 bln in February from January, and are now back near the record all-time high first reached in December 2021. (More than half that overall improvement was because Government bank account balances rose sharply.)
NEW APPOINTMENTS TO RBNZ LEADERSHIP TEAM
The Reserve Bank has made four appointments which it says round off its leadership team. Scott McKinnon, who has been Acting Head of Supervision, becomes Director of Prudential Supervision. Angus McGregor becomes Director of Specialist Supervision and Support, Kate Le Quesne becomes Director of Prudential Policy. An appointment has also been made to the Director of Financial Stability Assessment & Strategy role, with an announcement to follow. The RBNZ says the newbies join Kerry Beaumont, Director of Enforcement and Resolution, to form the Financial Stability Group Leadership Team.
POOR MANGEMENT, EVEN IF THE TIMES WERE CHALLENGING
The Auditor General has faulted how the Government handled its bailout of the tourism industry. The Auditor-General’s Inquiry into the Strategic Tourism Assets Protection Programme raises concerns about aspects of the program’s criteria, assessment process, and transparency when making decisions.
CONTRACTING
China's official PMI's (factory, services) both sank into contraction in March. These were faster retreats than were expected. Spreading pandemic lockdowns are not helping.
GOLD FIRMS
In early Asian trading, gold is up +US$6 from this time yesterday at just over US$1928/oz.
EQUITIES MOSTLY LOWER
On Wall Street, the S&P500 ended its Wednesday session down -0.6% and giving up half of yesterday's gain. Tokyo has opened lower in Thursday morning trade but has clawed out a small +0.1% gain since. Hong Kong has started down -0.8% in early trade. Shanghai is down -0.3% in their opening trade. The ASX200 is up +0.4% in early Wednesday afternoon trade. But the NZX50 is down -0.2% in late trade, where the AirNZ capital raising has weighed heavily on the index, and (AIR, #33) is down -9.8% so far and today's worst performer. It doesn't help that F&P Healthcare is down -2.0% as well.
SWAPS SOFT
We don't have today's closing swap rates yet. They are likely to be soft following bond market signals. The 90 day bank bill rate is up +1 bp at 1.61%. The Australian Govt ten year benchmark bond rate is down -3 bps from this time yesterday at 2.79%. The China Govt 10yr is unchanged at 2.82%. And the New Zealand Govt 10 year bond rate is now lower at 3.26% (down -6 bps) and now under the earlier RBNZ fix for that 10yr rate at 3.27% (down -4 bps). The US Govt ten year is now at 2.34% and a -3 bps fall since this time yesterday. The UST 2-10 curve inversion threat remains but it hasn't happened yet.
NZ DOLLAR UNCHANGED
The Kiwi dollar is now at 69.7 USc and up slightly from this time yesterday. Against the Aussie we are firmer at 92.9 AUc. Against the euro we are a tad lower at 62.3 euro cents. That means the TWI-5 is now still at 74.7 and unchanged.
BITCOIN FIRMS
Bitcoin is up +1.1% today to US$47,297. Volatility in the past 24 hours has been modest at +/- 1.2%.
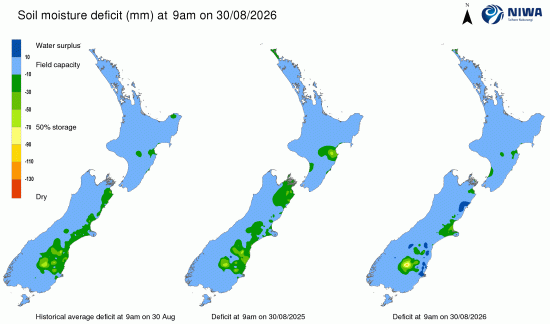
This soil moisture chart is animated here.
Keep ahead of upcoming events by following our Economic Calendar here ».
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.