
By Gareth Vaughan
Reserve Bank Governor Alan Bollard might be forgiven a sly smile if he looks at the latest residential mortgage analysis out from the central bank.
Figures released by the Reserve Bank yesterday afternoon show NZ$135.644 billion, or 80.74% of the country's total NZ$168.001 billion worth of home loans were either floating or fixed for a term of less than one year in April. This figure, which excludes NZ$501 million of unallocated mortgages, is a record high percentage since the central bank's series on floating and fixed-term home loans began in June 1998 ahead of 79.85% reached in March.
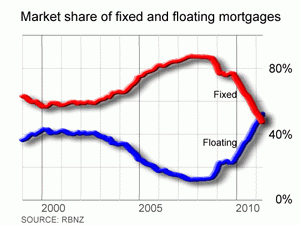
The percentage of all residential mortgages on floating, or variable, terms has also extended its record high, reaching 52.62% after popping up above 50% for the first time in March. This comes at a time when most banks are offering lower interest rates on floating loans than fixed-term ones and have been for some time. See all bank residential mortgage rates here.
The Reserve Bank's ability to control consumer spending and inflation through Official Cash Rate (OCR) moves is boosted by having more people on floating mortgages. Because the OCR's biggest influence is on short-term interest rates, a hike or cut in the OCR quickly flows through to floating interest rates.
A borrower on a floating mortgage is, for example, generally hit by a 25 basis point hike when the Reserve Bank lifts the OCR by the same amount. This means the borrower is forced to spend more on interest payments, giving them less discretionary money to spend elsewhere.
The OCR is currently at 2.5% with most economists not picking an increase until at least December. The Reserve Bank has said in the past this extra monetary policy power allows it to keep interest rates lower and avoid faster increases.
Of the country's total NZ$168.001 billion worth of residential mortgages (excluding the unallocated), NZ$88.397 billion was floating as of April and NZ$47.247 billion worth fixed but due to roll over within 12 months.
The low according to the central bank's data, in terms both of home loans floating and fixed but up for renewal within 12 months, was 37.5% in June 2007.
The April Reserve Bank data shows NZ$23.774 billion worth of home loans fixed for between one and two years, NZ$6.697 billion for between two and three years, NZ$1.348 billion for between three and four years, NZ$460 million for four to five years and NZ$77 million for more than five years.
'We're going to feel it really quickly'
The Reserve Bank's record 'potency' caught the attention of NZIER principal economist Shamubeel Eaqub.
“Over the next couple of years the Reserve Bank is going to get quite a bit of help from two things. Number one is the core funding ratio goes up again, so that will give them a bit more traction in terms of how much mortgage rates are," Eaqub said in a speech in Wellington on Wednesday afternoon.
"But also there’s been this massive increase in people going onto floating and short-term mortgages. We’re talking really massive here. Almost 80% of all mortgages by value are short-term – either floating or expiring in the next 12 months. When the Reserve Bank raises interest rates, we’re going to feel it really, really quickly," Eaqub said.
"This is a real turnaround from what we had in the 2006/07 period, when the Reserve Bank was trying to raise interest rates, but it just had no traction because most people were on fixed. This I think is going to be a very, very powerful driver," he said.
"Even though we’ve been talking about households starting to save more, the actual stock of debt hasn’t really come down – not much, debt growth has been very, very small, but it’s still been growing. So it’s going to be passed onto consumers very, very quickly and it will have an impact in terms of subduing demand.
"So we think the Reserve Bank doesn’t have to raise interest rates that much to have the kind of powerful impact to curb some of those inflation pressures that are building in the economy."
(Updates with NZIER comments)
This article was first published in our email for paid subscribers this morning. See here for more details and to subscribe.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.