This week’s Top 5 comes from ANZ economist Michael Callaghan.
As always, we welcome your additions in the comments below or via email to david.chaston@interest.co.nz.
And if you're interested in contributing the occasional Top 5 yourself, contact gareth.vaughan@interest.co.nz.
The RBNZ cut the OCR to 1.5% at the May Monetary Policy Statement, to support employment and get inflation back to 2% sustainably. There are a few channels through which the OCR cut have been effective in easing financial conditions, but more cuts are needed to support a pickup in growth, as we discuss in our ANZ Weekly Focus.
1. The NZD has depreciated.
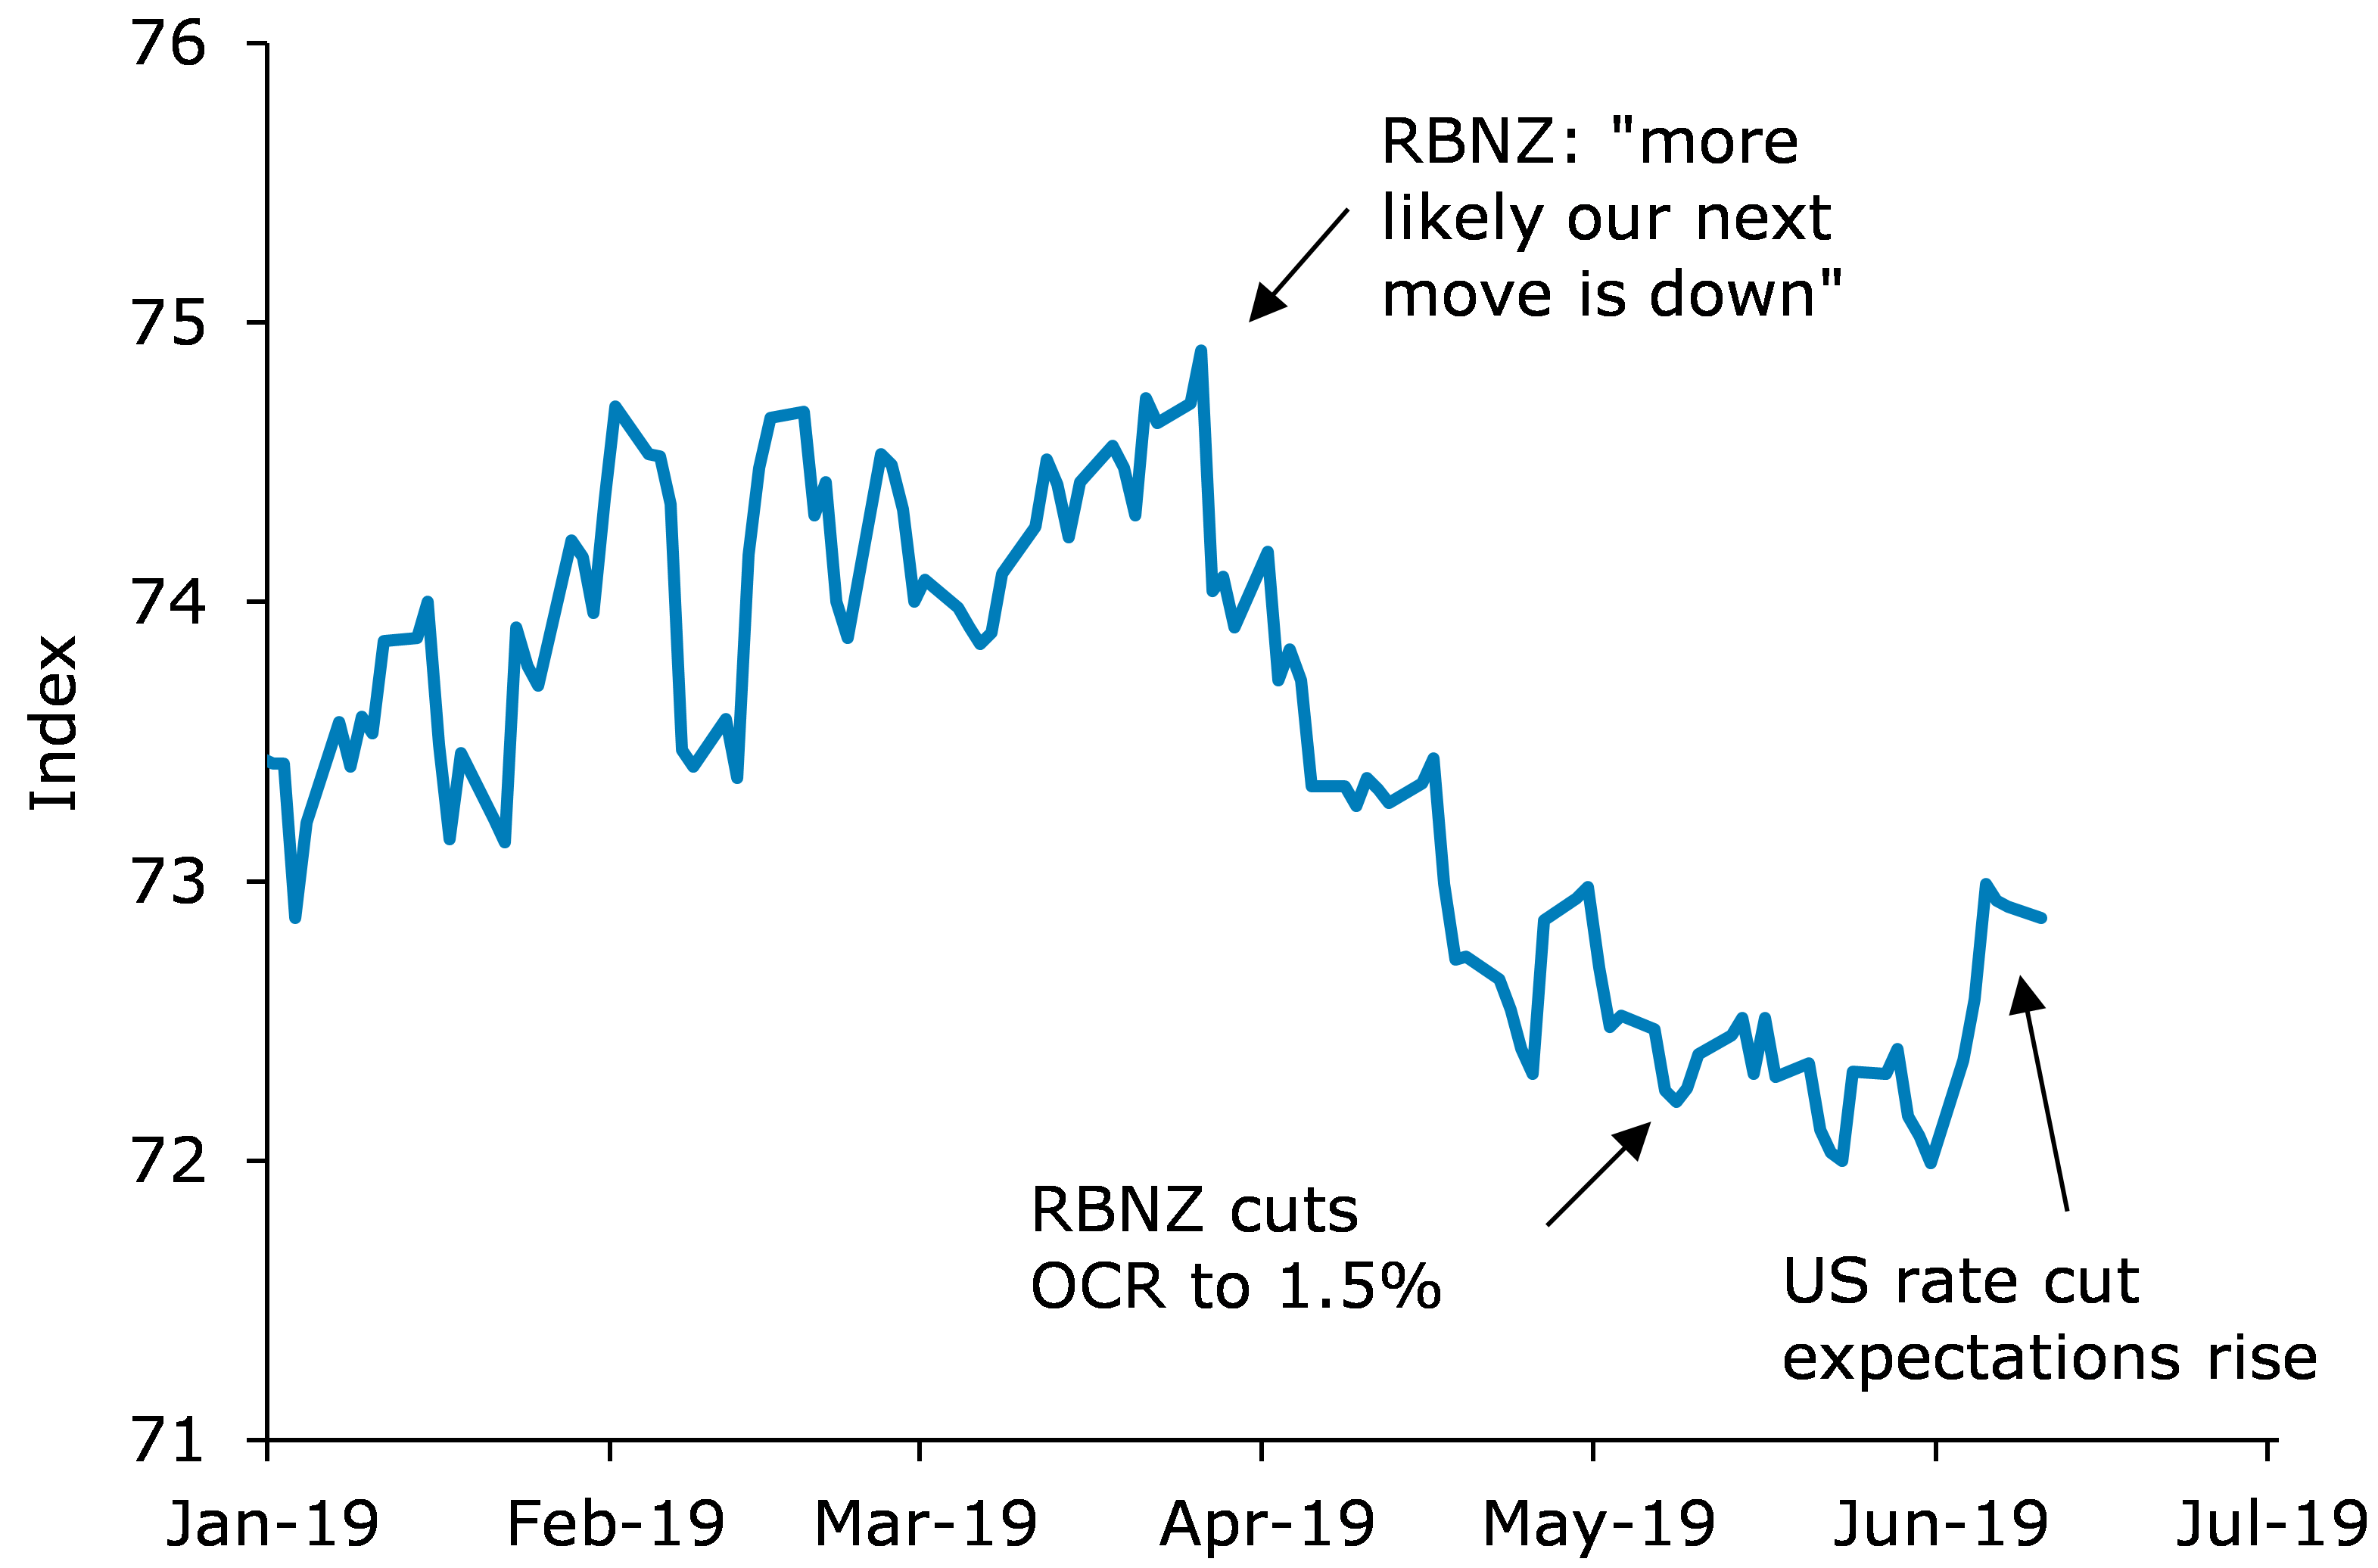
For a small open economy, the exchange rate is an important channel for monetary policy, and interest rate differentials matter for the NZD. Most of the recent fall in the NZD already occurred back at the March OCR Review, when the RBNZ signalled that a lower OCR would likely be needed (figure 1). The OCR cut in May helped to lock in this fall.
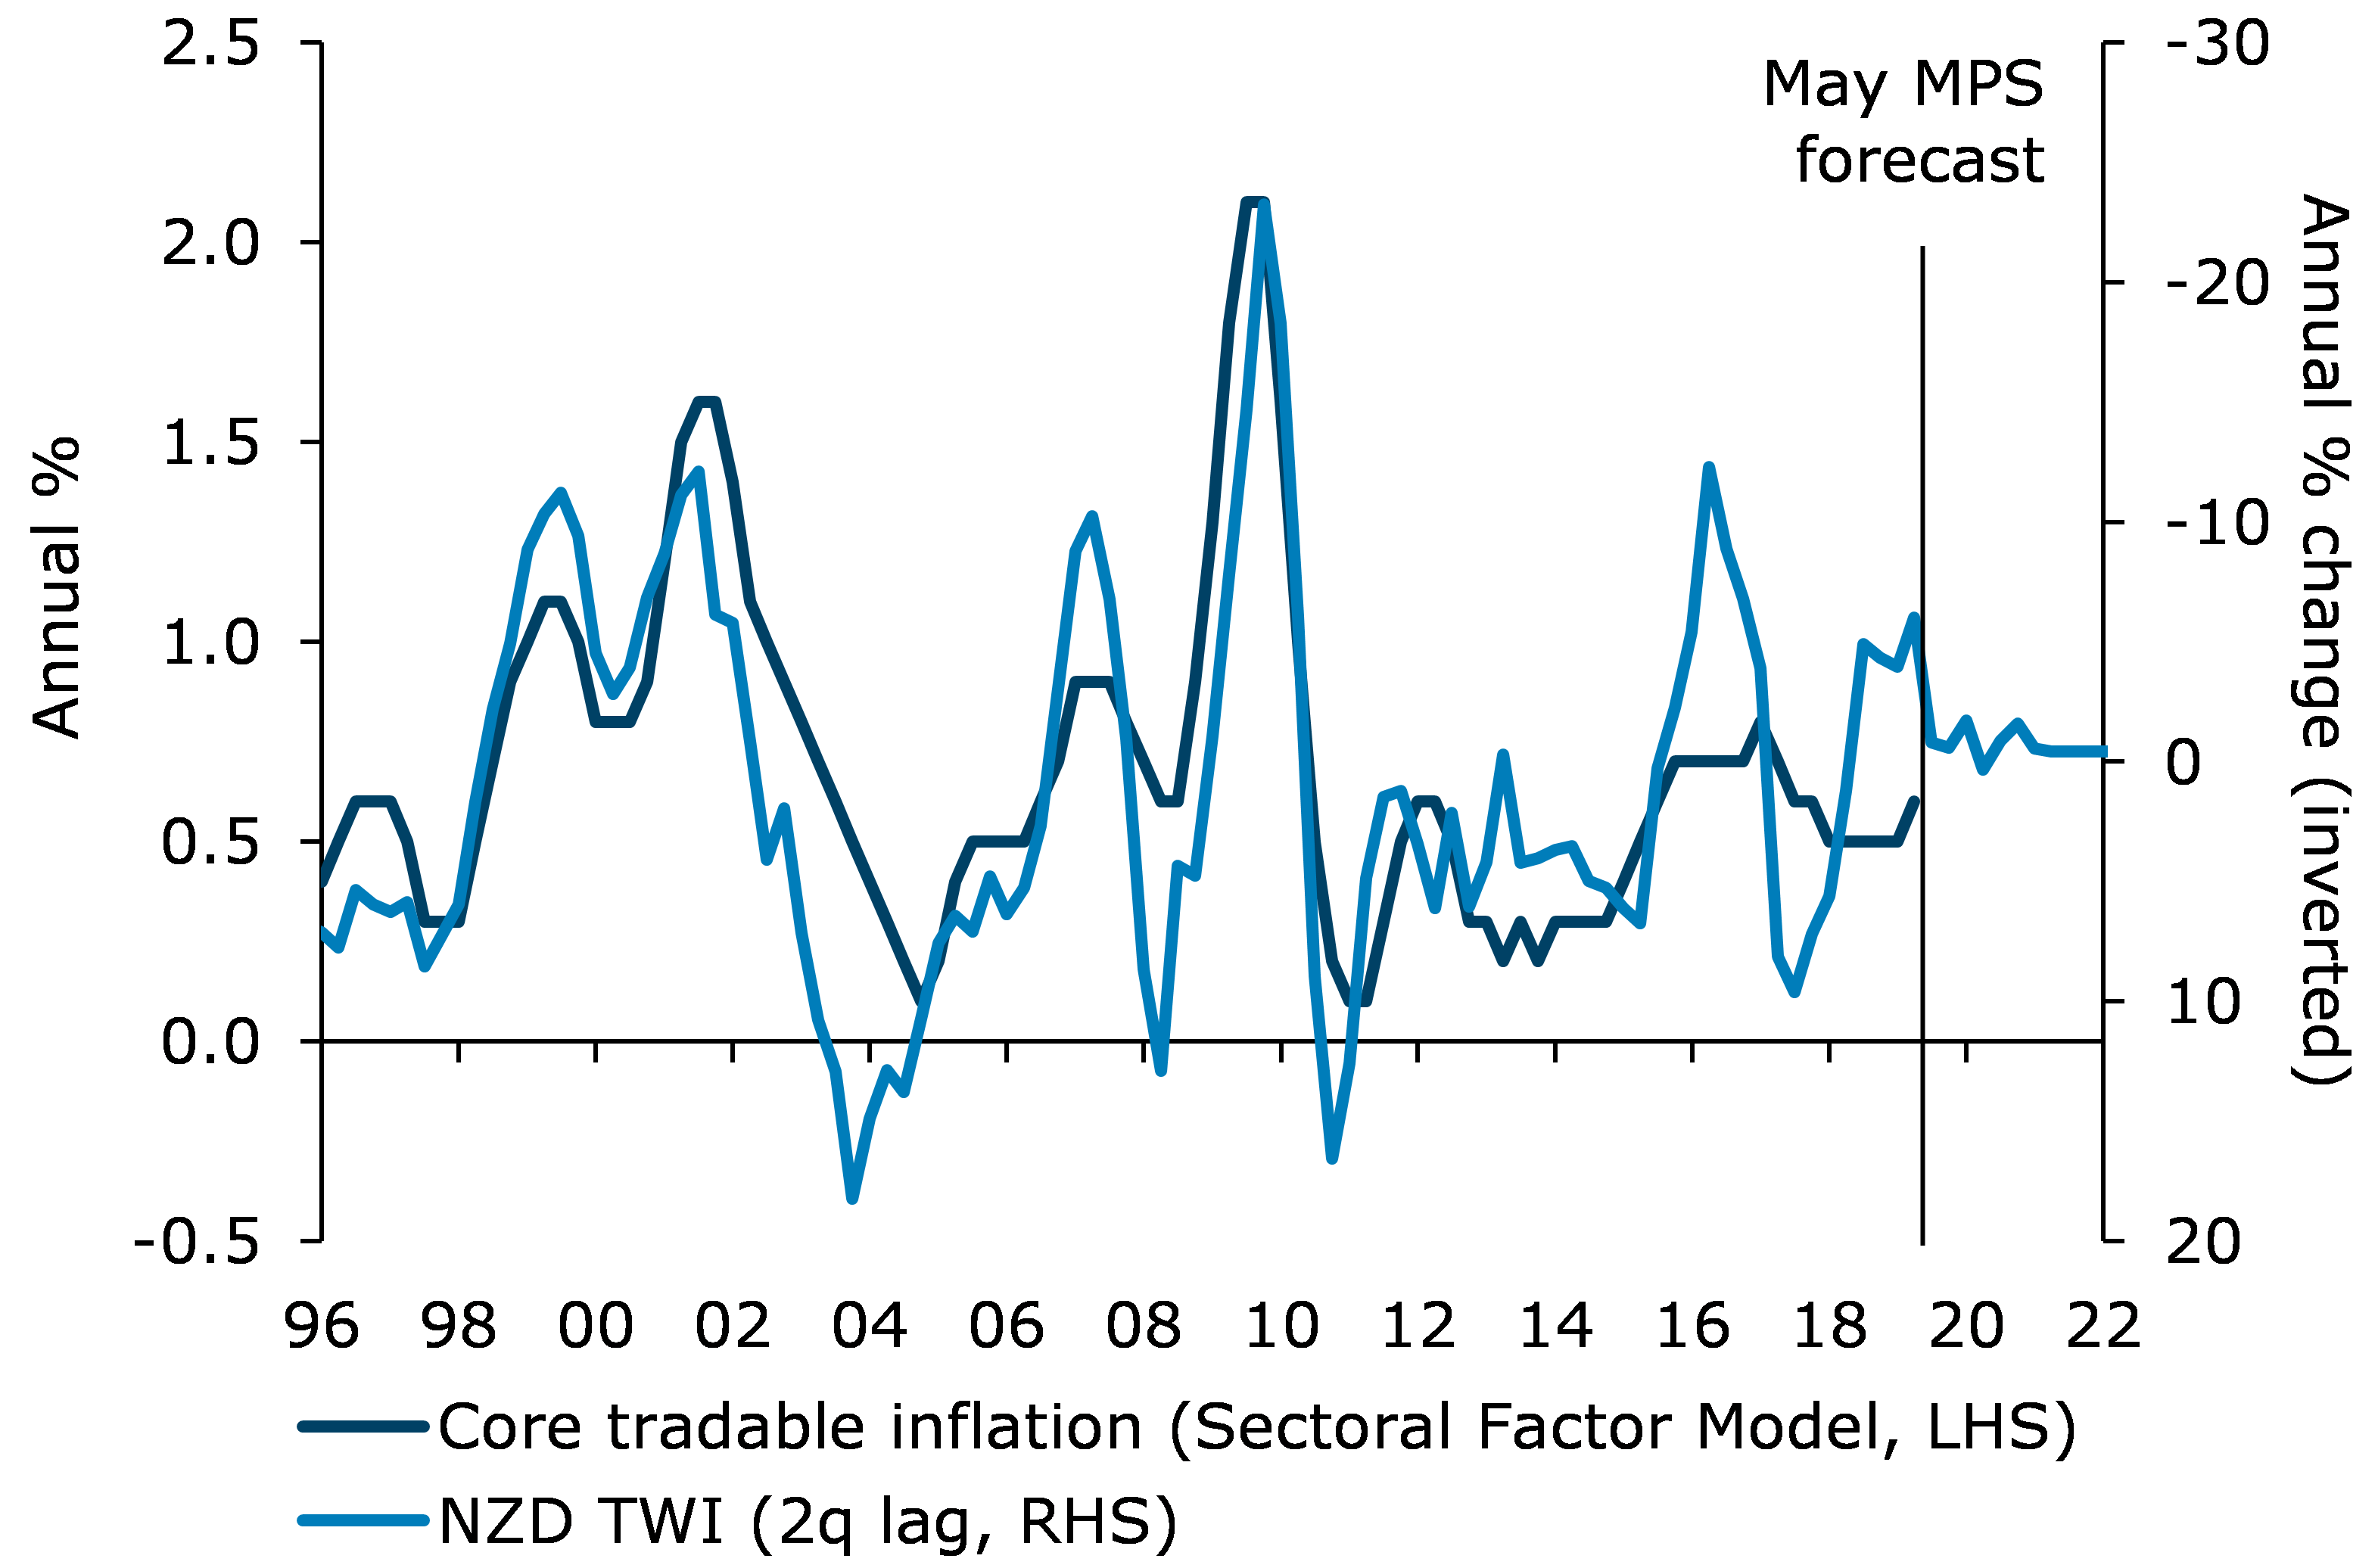
The lower NZD will boost exporters’ incomes and their spending in the economy. But with the global outlook fragile, we suspect the pass-through to the rest of the economy will be a little more muted than otherwise – deleveraging seems more likely than a spend-up. The fall in the NZD will also increase imported prices, which will encourage domestic spending, rather than imported spending, and will give inflation a boost (figure 2).
That said, with the exchange rate channel, the RBNZ is always up against other central banks’ policy stances. Increasing expectations for rate cuts from the US Federal Reserve has seen the NZD move higher again in recent weeks.
Figure 1. NZD trade weighted index
Source: Bloomberg, ANZ Research
Figure 2. NZD and tradable inflation
Source: RBNZ, ANZ Research
2. Mortgage rates have fallen over the past year.
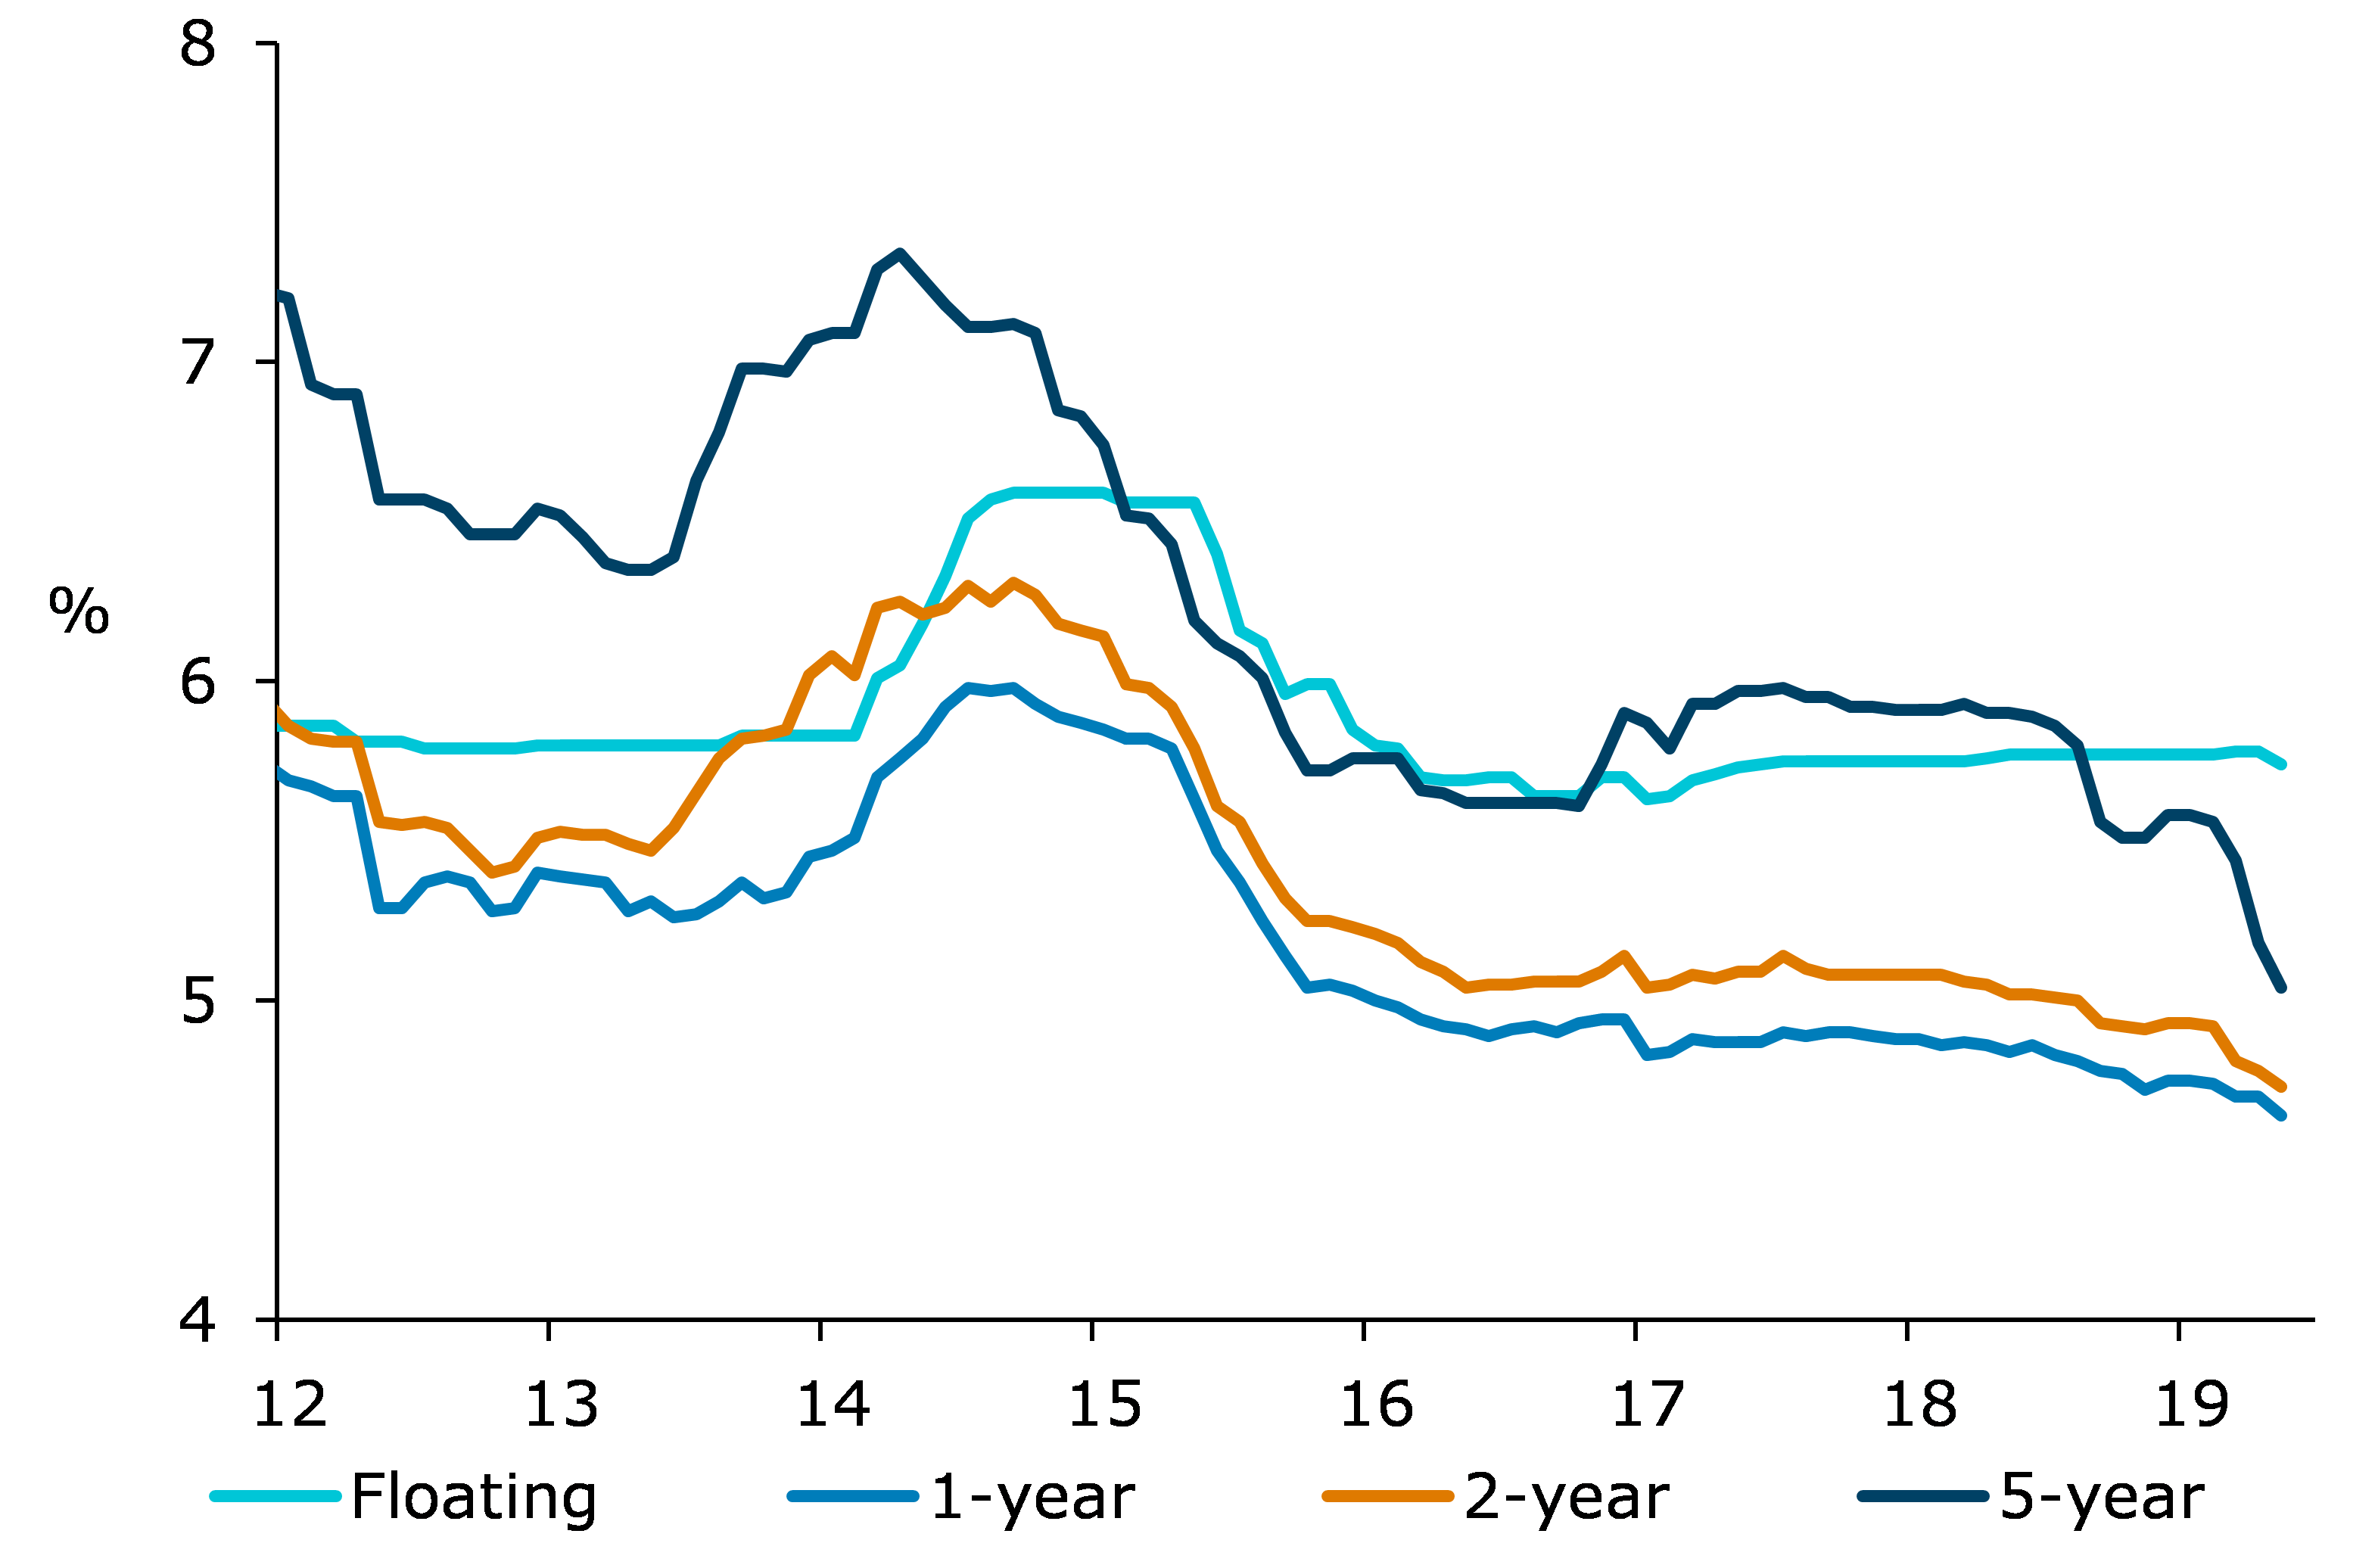
Mortgage rates have fallen, particularly for fixed terms, which about 80% of mortgages are on. Too much focus is often placed on the current OCR, but it is expectations about the future OCR and the future stance of the RBNZ that are important for moving these longer-term interest rates. At the end of May, the 5-year rate had fallen 54 bps and the 2-year rate had fallen 20 bps since the start of the year (figure 3).
We expect the fall in mortgage rates to help stabilise the housing market, rather than accelerate it. But as mortgage rate changes flow through, current mortgage holders will be left with more cash to spend elsewhere.
Figure 3. Mortgage rates
Source: RBNZ, ANZ Research
3. Pressure on business lending rates has reduced.
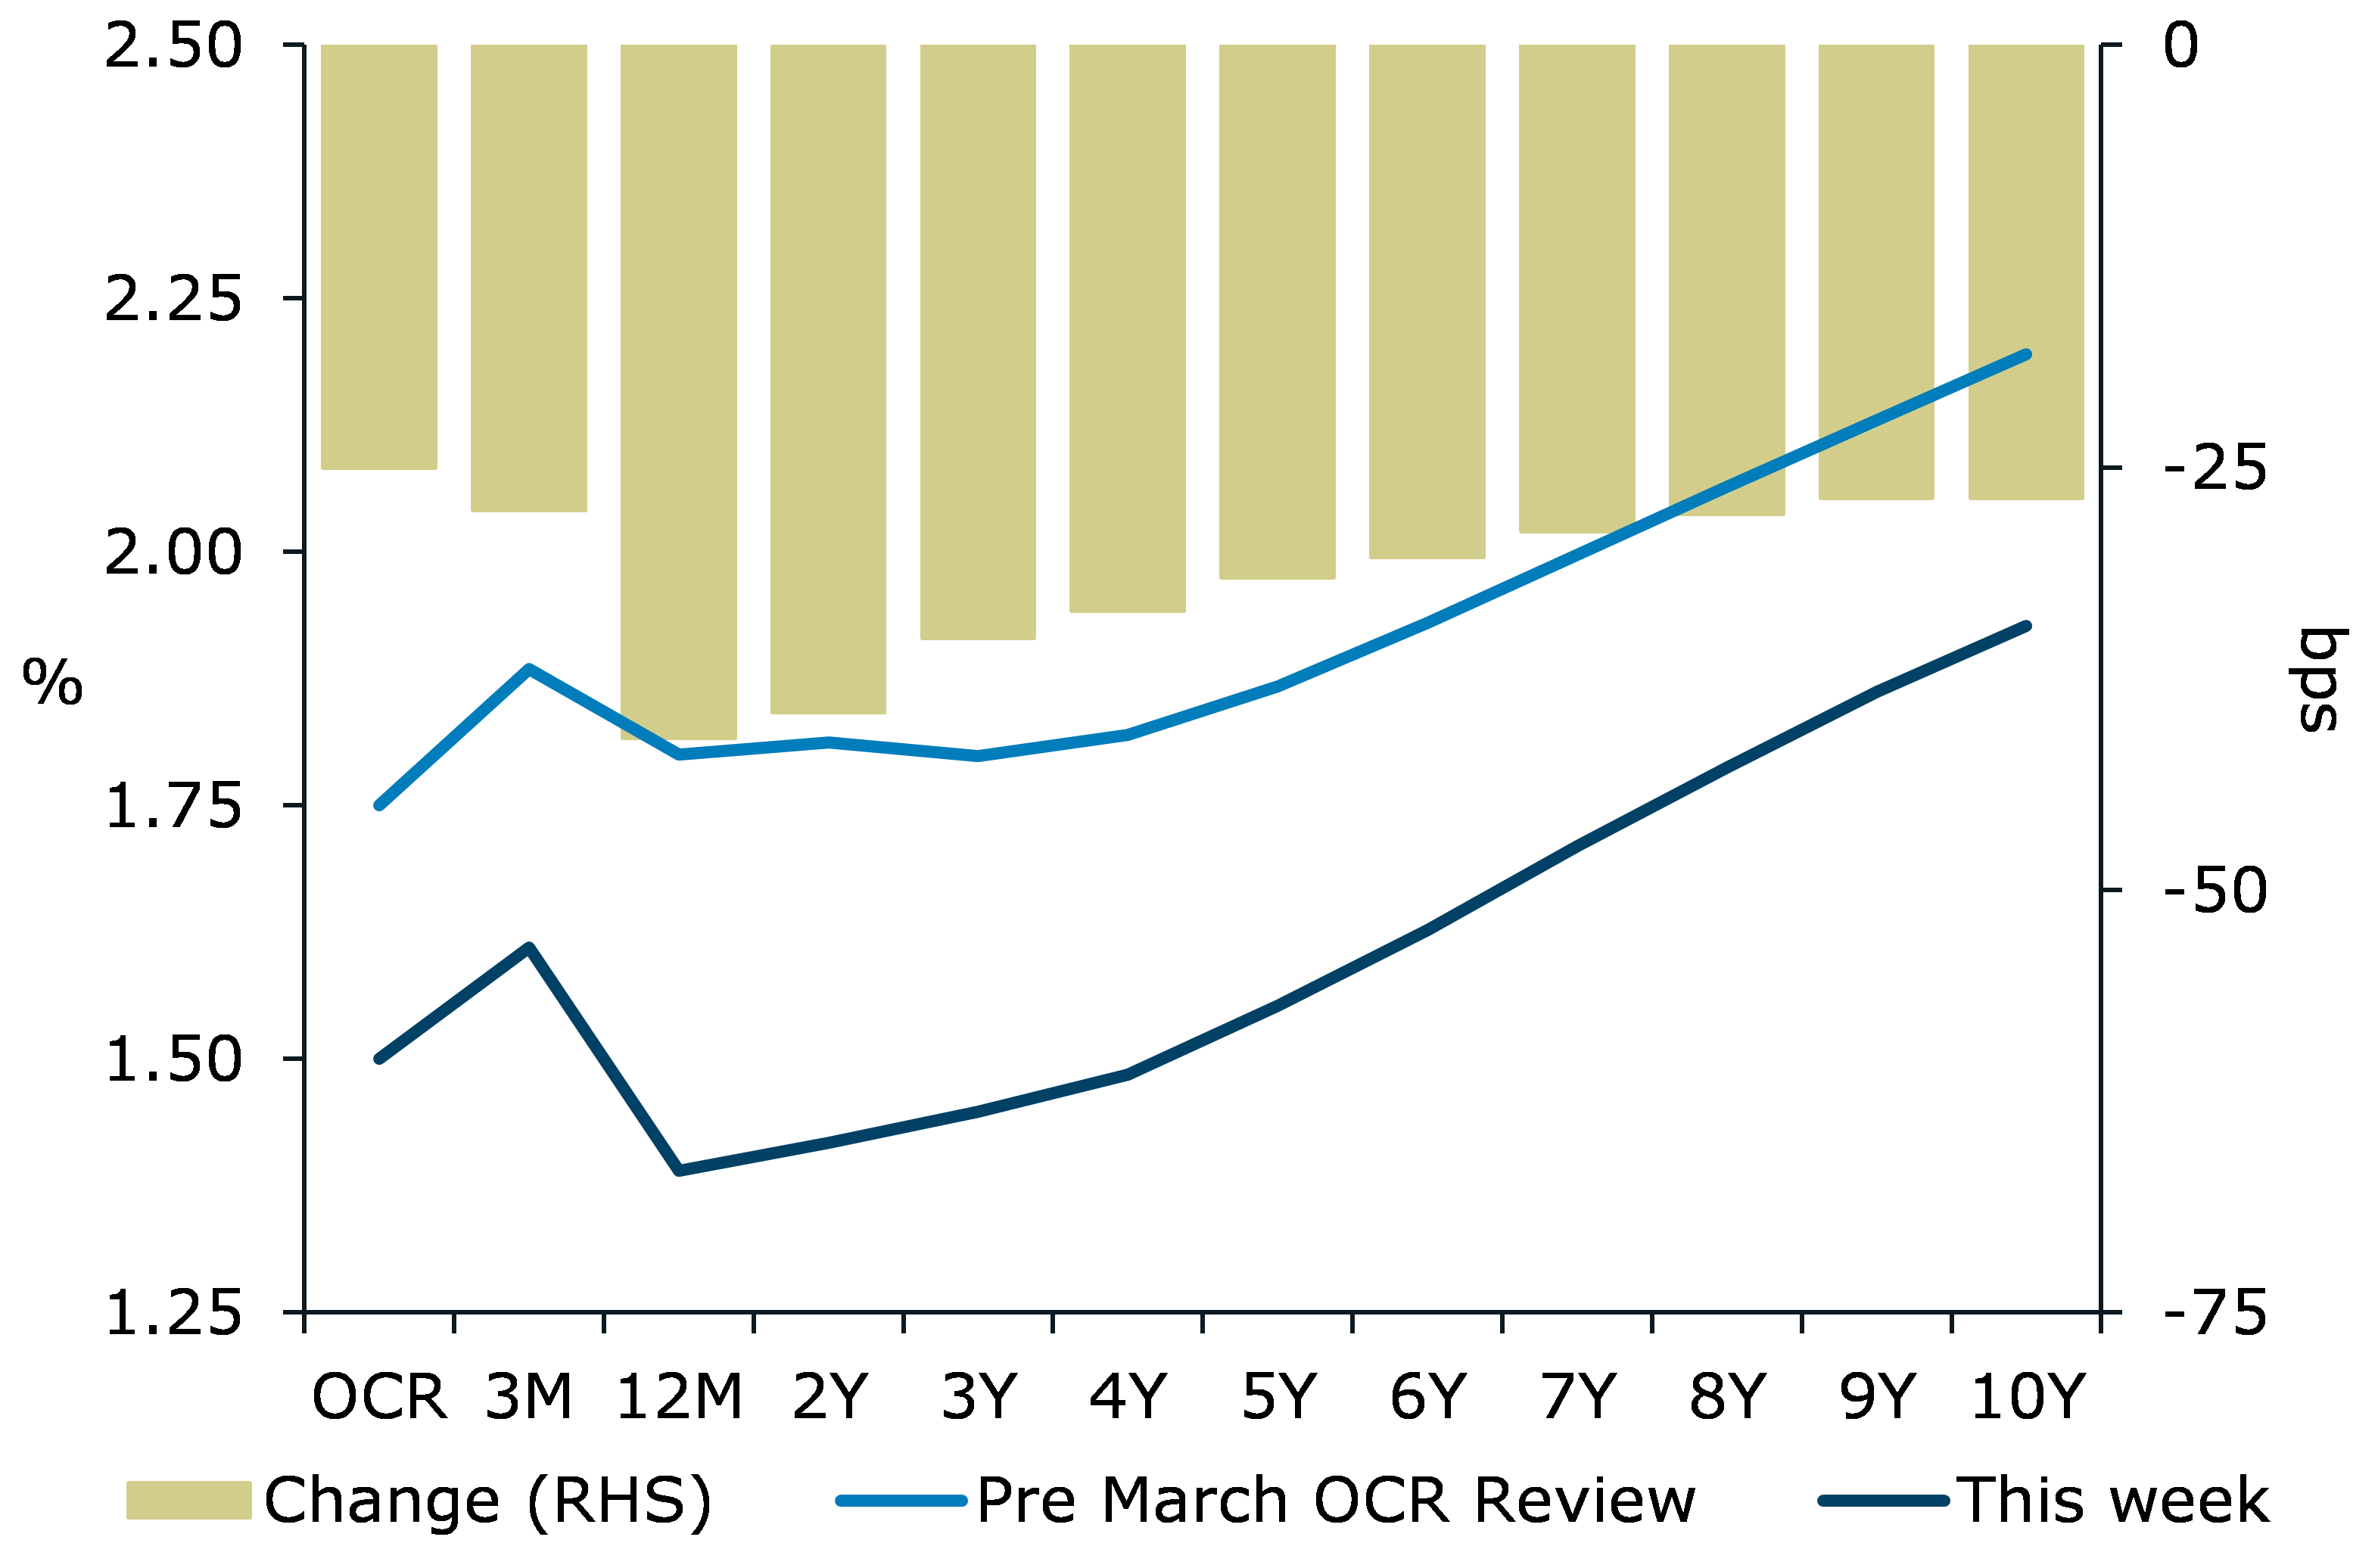
The drop in the OCR will, at the margin, relieve upward pressure on business lending rates. Interest rates in wholesale debt markets have also declined (figure 4), meaning that corporates can now issue debt more cheaply. Business surveys suggest that the investment and activity outlook remains gloomy, with declining profitability, labour shortages, regulatory concerns, and uncertainty holding back production. But with lower financing costs, investment projects are now a bit more attractive than they were. In addition, lower deposit rates increase the incentive for firms to spend and invest, rather than sit on cash.
Figure 4. NZ wholesale swap interest rate curve
Source: Bloomberg, ANZ Research
4. But we don’t think growth will pick up rapidly with the OCR at 1.5%.
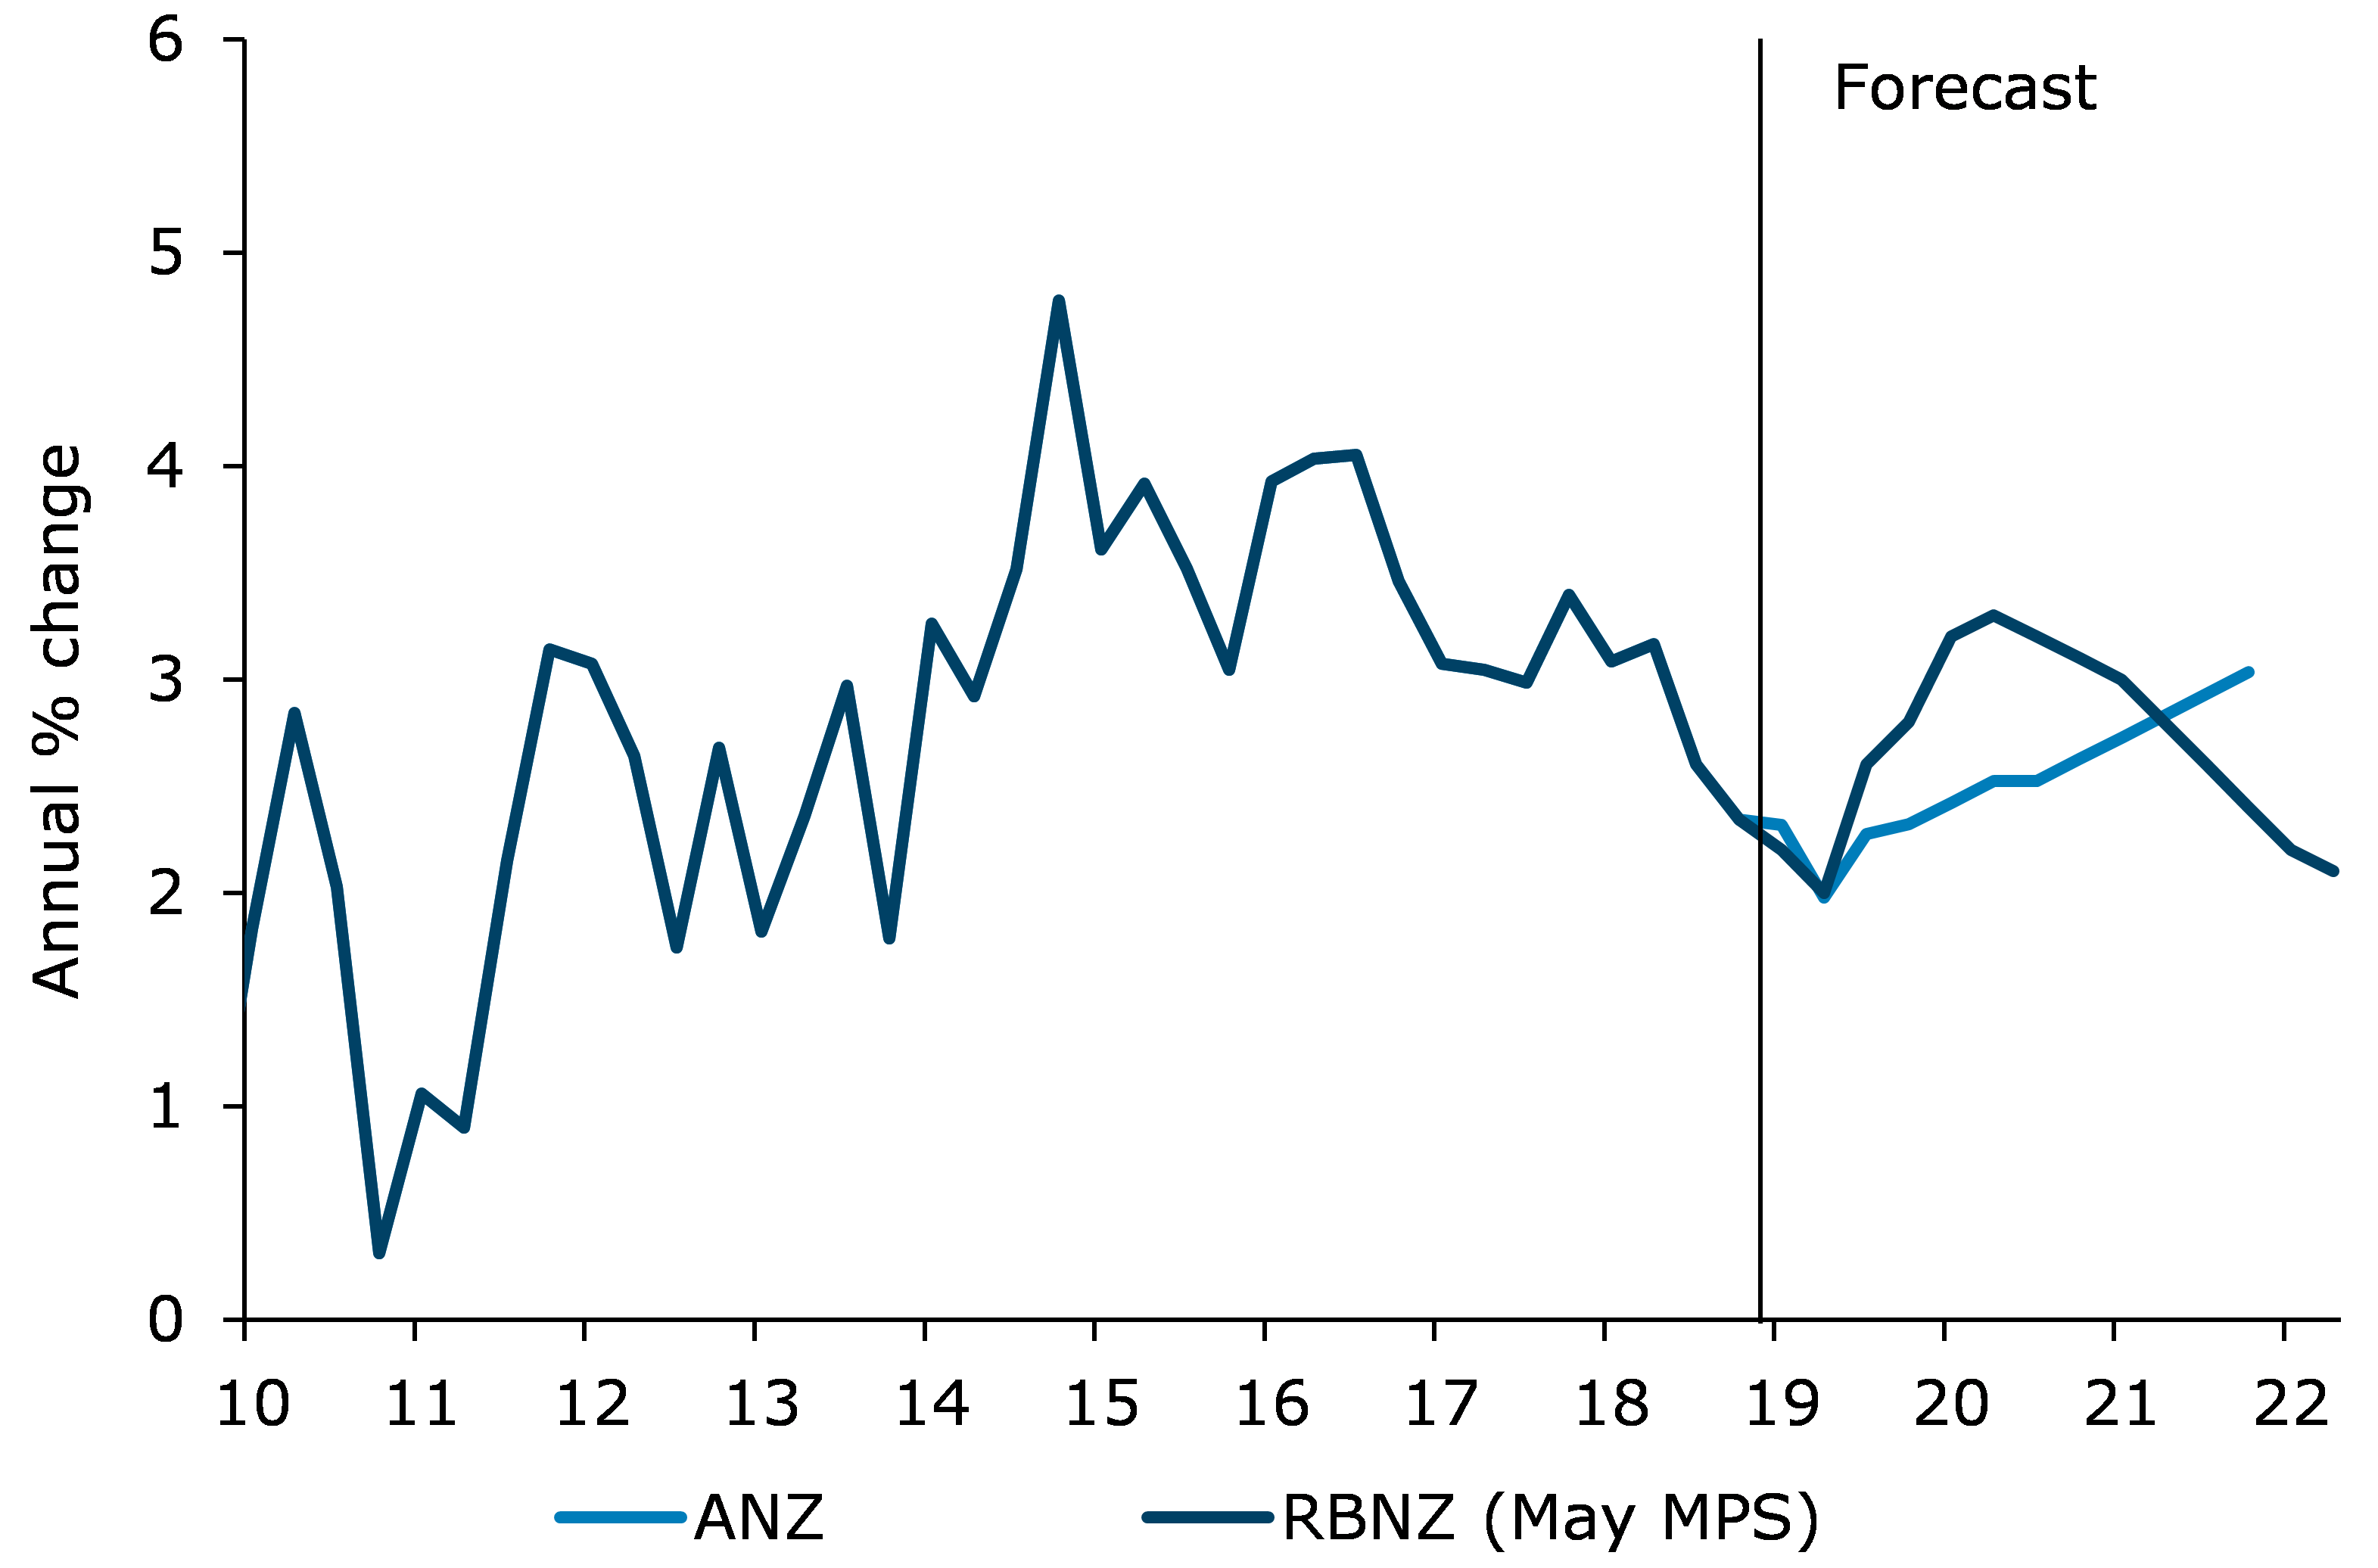
Our growth outlook and the RBNZ’s growth outlook rapidly diverge from mid-2019 (figure 5). While easier financial conditions are providing a tailwind to growth, other headwinds are evident. Growth in residential construction activity has slowed as margin pressures, shortages of labour, and usable land constraints bite. And now household spending is taking a hit, with consumption growth off its 2016 peaks. Amid the housing market slowdown and global growth risks, we think weaker business activity has a little longer to run.
Figure 5. GDP growth
Source: RBNZ, ANZ Research
5. So central bank policy rates are likely to fall further.
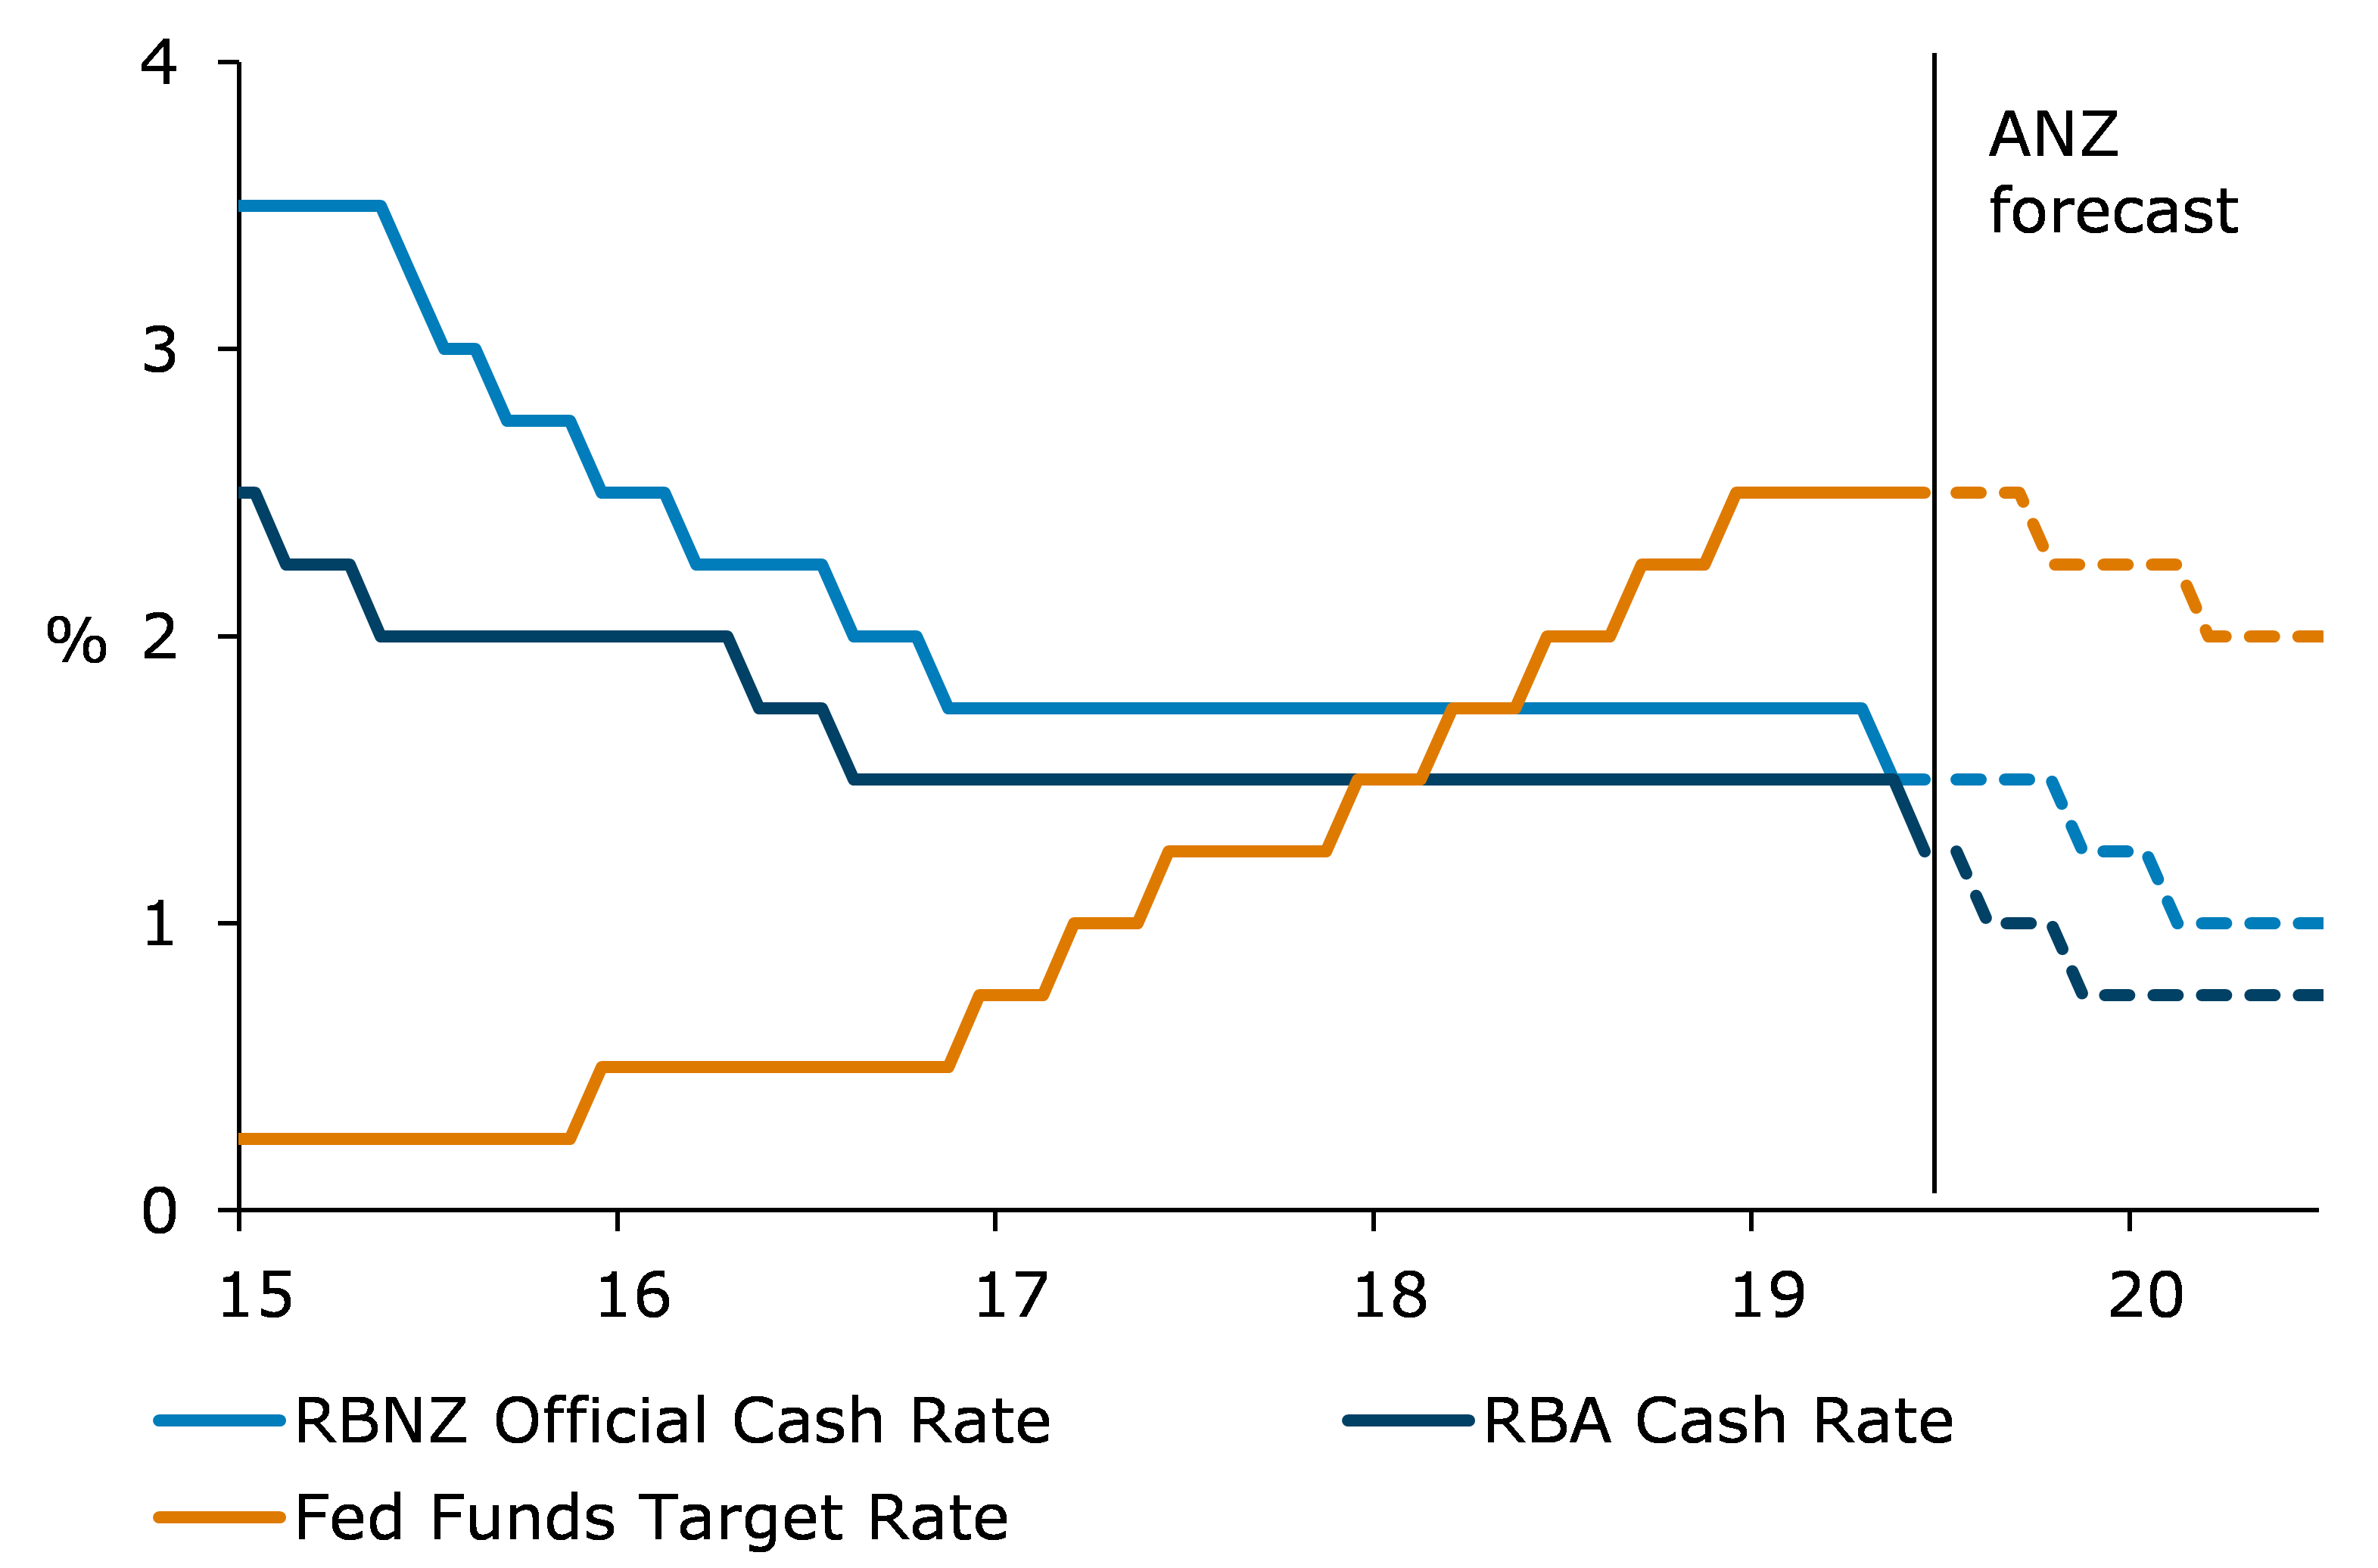
With domestic growth unlikely to accelerate sharply, we expect additional rate cuts by the RBNZ in November and February to take the OCR to 1% (figure 6). Further cuts in the OCR should help ease lending rates and the NZD further and see domestic growth gradually recover.
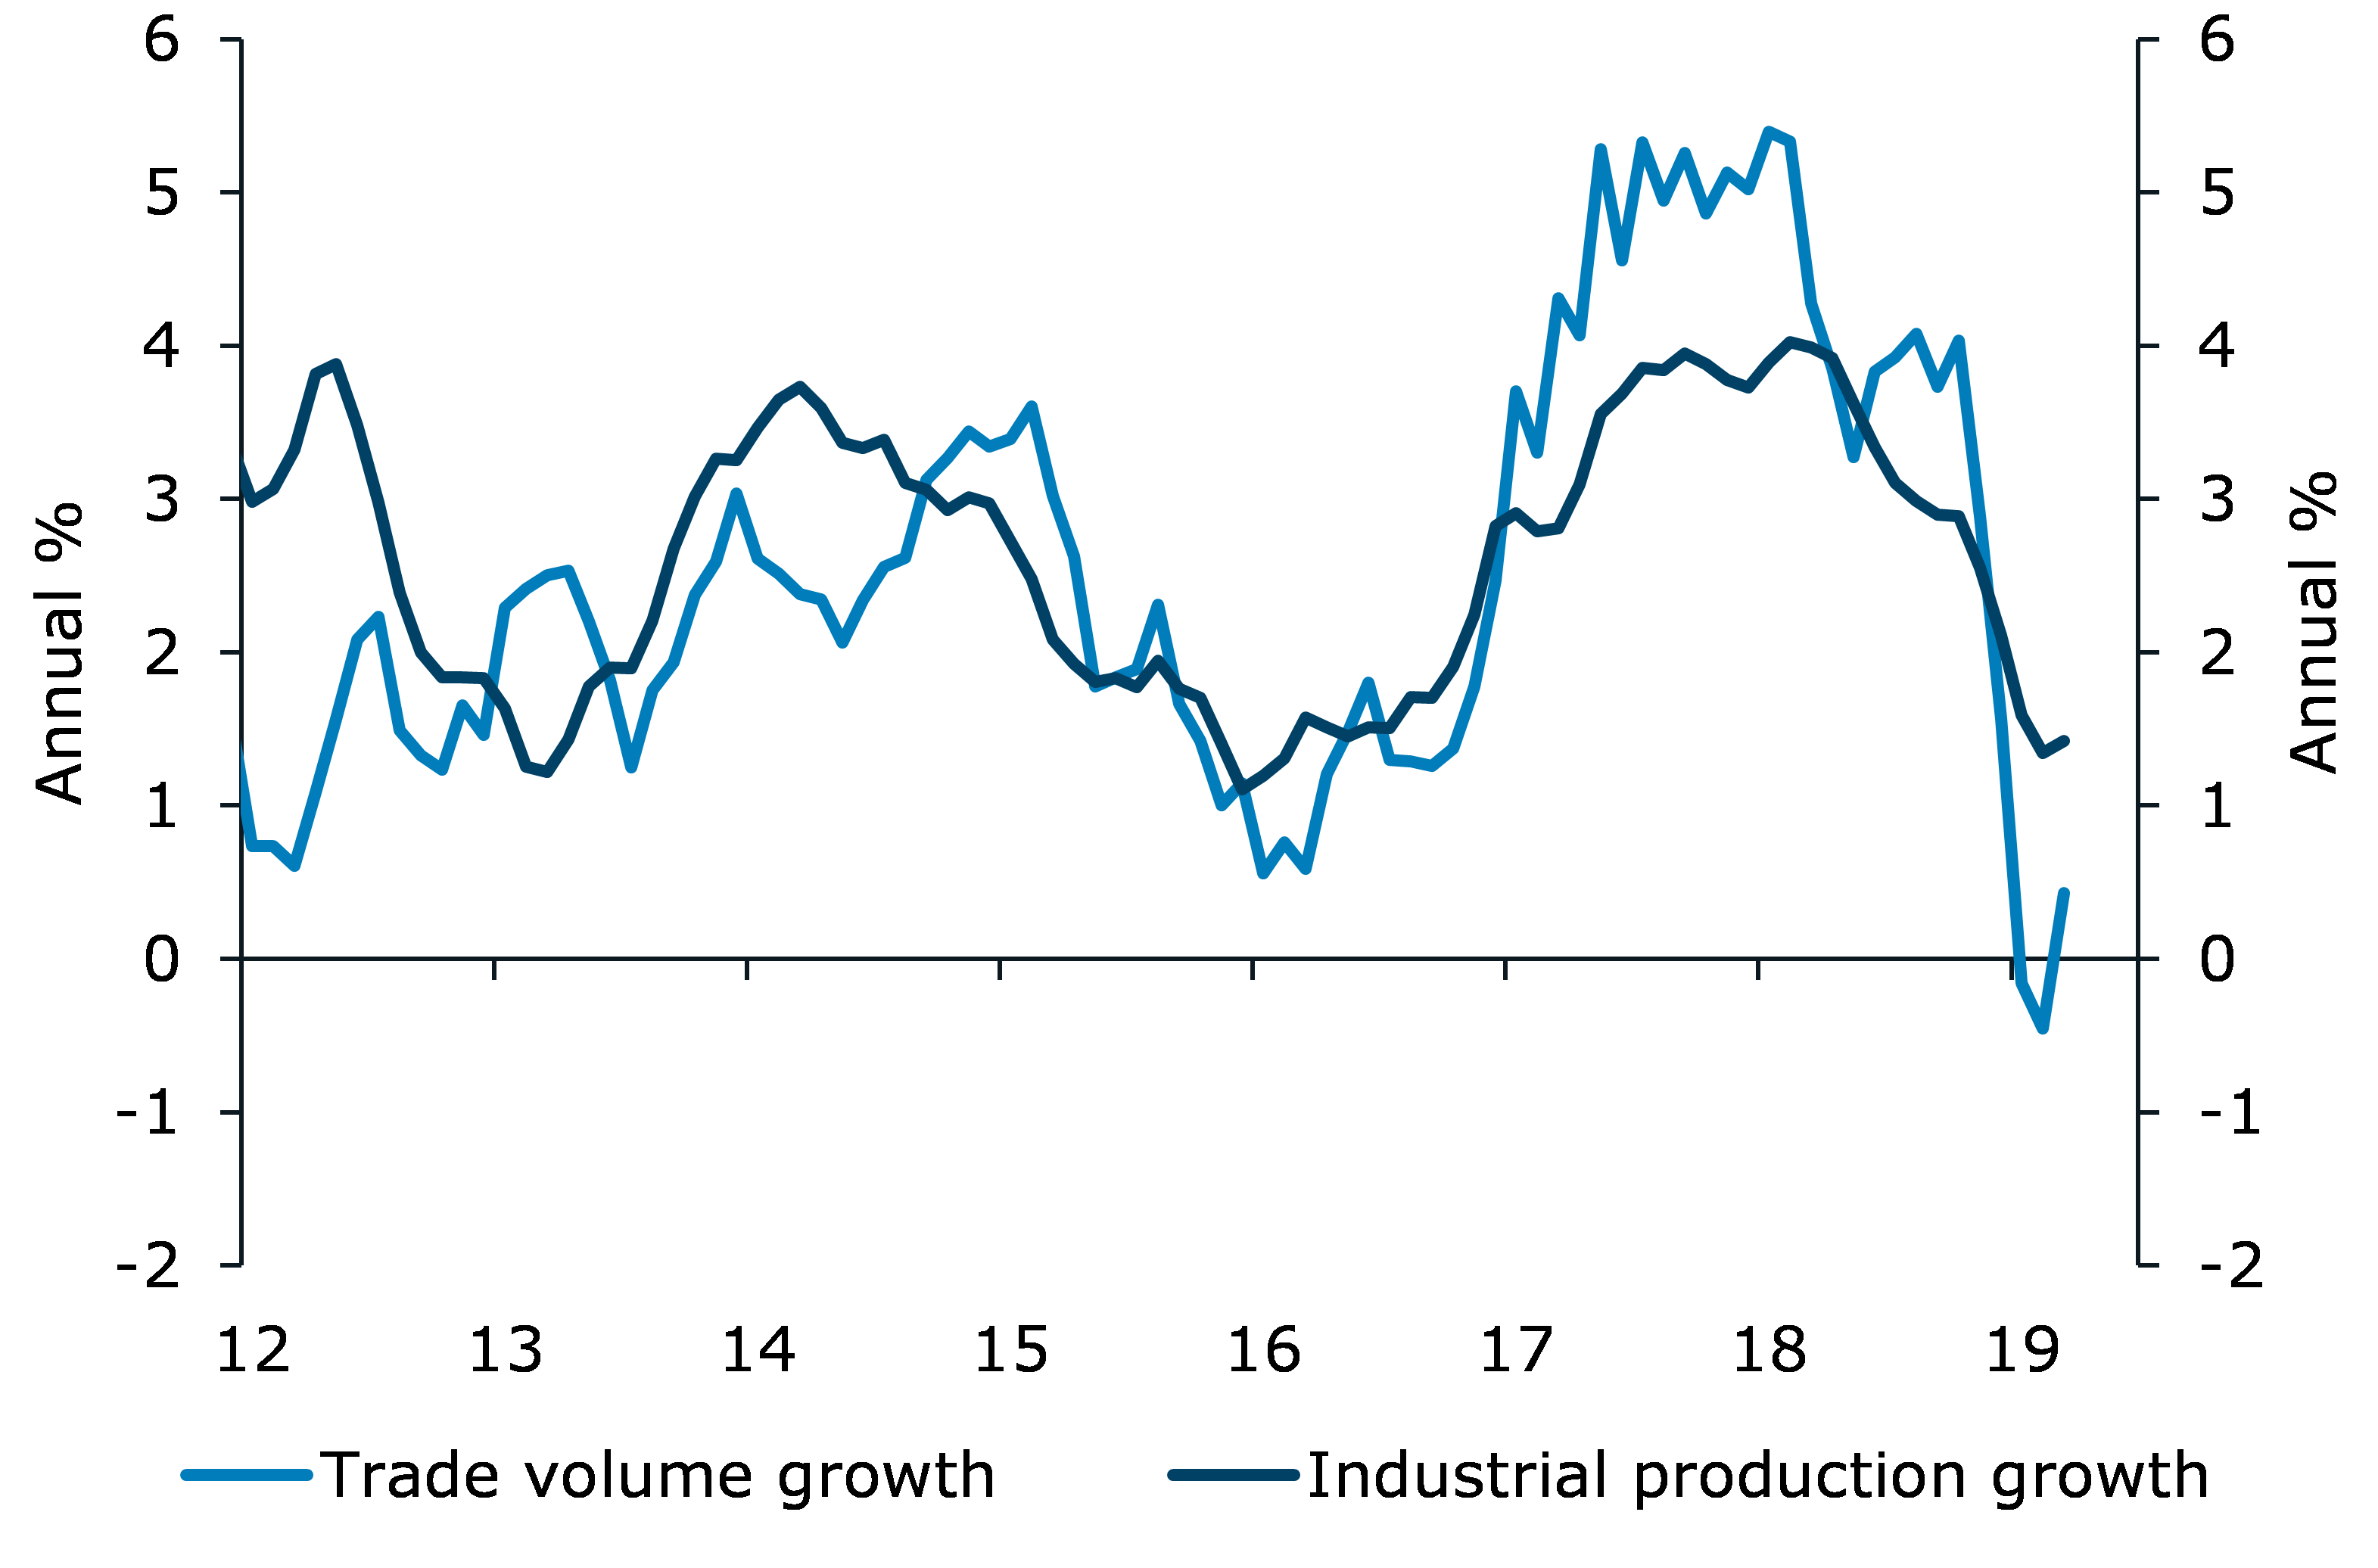
But New Zealand isn’t the only economy with weak inflation and slowing growth. Global risks are elevated, with global industrial production and trade growth slowing sharply over the past six months (figure 7). The RBA has begun a fresh easing cycle, and we now expect the Fed to follow suit.
But central banks globally have little room to move if a crisis hits. Domestically, the RBNZ has been exploring unconventional monetary policy, such as negative interest rates and quantitative easing. Regardless, the next crisis can’t be borne by monetary policy alone – fiscal policy needs to be ready to step up.
Figure 6. Central bank policy rates
Source: Bloomberg, RBNZ, ANZ Research
Figure 7. World industrial production and trade growth
Source: Bloomberg, ANZ Research
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.