
 By Roger J Kerr
The outlook for the New Zealand economy today is certainly not as gung-ho as it was at the start of 2014.
Back in January/February even the local economic forecasting group who had previously forecast six of the last two economic recessions were positive on the NZ economy!
Something was telling me back in February that the superlative economic conditions were too good to last and if the perma-bears were suddenly positive we just had to be close to a turning point.
However, I do not think any commentator foresaw the subsequent 40% plummet in international dairy prices as the factor that would slow the rock star economy down.
As we are now seeing in overseas import/export trade data and the Terms of Trade data, the combination of the higher Kiwi dollar and much lower dairy prices is reducing volumes and activity levels.
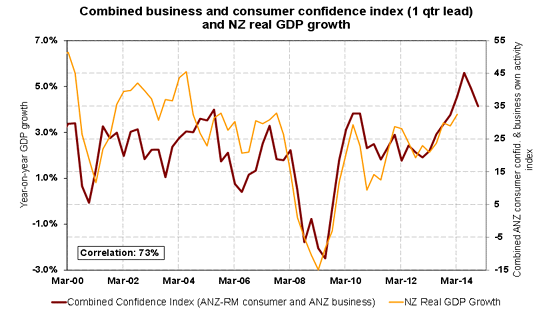
It is certainly no surprise that business confidence has come back off its record levels very rapidly indeed over recent months.
If it was not for the Christchurch rebuild to outlook for GDP growth would not be that flash.
The June quarter employment numbers were weaker than expected and job advert surveys point to a levelling off in the labour market over coming months.
Add in to the mix that the recently confirmed $6/kg milksolids payout forecast for 2014/2015 from Fonterra will need further significant falls in the Kiwi dollar or a dramatic recovery in Wholemilk Powder prices to be achievable and one can understand heartland spending/investment plans being hastily revised.
Economists are now revising down their June quarter GDP growth forecasts to +0.70% and below. Current trends in other key economic statistics support the view that we are past the peak in the strong GDP growth and thus future inflation risks have subsided.
However, further sharp falls in the NZ dollar to below 0.8000 will start to increase the price of imported consumer goods, something we have not experienced for a number of years.
It would certainly not pay to get complacent about future inflation threats. Current moneymarket pricing of interests rates out to three years forward seem to have temporarily forgotten this.
Borrowers therefore need to fix long and investors need to stay short right now.
While some sectors of the economy are experiencing a levelling off in activity levels, the tourism industry is booming on from my observation. Not even the high NZ dollar has slowed overseas tourist numbers and their spending levels.
Evidence of the tourism resurgence is seen from listed tourism company THL reporting increased profits last week, plus a few days spent in Queenstown with hoards of Aussies jamming the restaurants is sufficient anecdotal evidence for me.
Unlike some other industries who moaned a while back to all and sundry about how the high currency was hurting them, the tourism industry has just got on with it in the knowledge that you never create wealth selling on price alone.
-----------------------------------------------------------
To subscribe to our daily Currency Rate Sheet email, enter your email address here.
Daily swap rates
Select chart tabs
Roger J Kerr is a partner at PwC. He specialises in fixed interest securities and is a commentator on economics and markets. More commentary and useful information on fixed interest investing can be found at rogeradvice.com
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.