
The tide turns slowly when mortgage rates are reduced.
That's arguably why we aren't really seeing too much of a visible pickup in the economy yet. People appear to be pretty cautious and reluctant to get out spending again. Confidence may take time to return.
Some economists, particularly those with banks, are pushing quite aggressively for more and faster interest rate cuts.
But would that help?
Would more aggressive upfront interest rate cuts help the overall economy now, when the cuts that have already been made are probably not yet taking full effect?
A big question for me this year was always going to be just how quickly our economy could recover as interest rates started coming down. It was suggested that since the sharp recession we saw last year was essentially engineered by the Reserve Bank's tightening of monetary policy (through Official Cash Rate hikes) between 2021 and 2023 - that reversing those OCR hikes would see the economy recover more quickly than might 'normally' happen after a recession.
But such thinking probably leaves out the human factor. People lose confidence in the idea of spending and have to be cajoled back into it.
So, our economy is taking time to recover. But I think there are clear signs it is recovering and so it becomes valid to question how much more 'medicine' (through lower-still mortgage rates) the patient needs.
It's worth having a thorough look at where our mortgage rates have been and what's happening with them at the moment in order to understand the dynamics of the whole thing.
So far, the OCR has been cut from the cycle peak of 5.5%, reached in May 2023, to 3.5%, with the next review of it due on May 28.
The banks started reducing our mortgage rates substantially last year even before the RBNZ decided it was sufficiently on top of inflation to start reducing the OCR in August.
Let's have a look at some examples of mortgage rates:
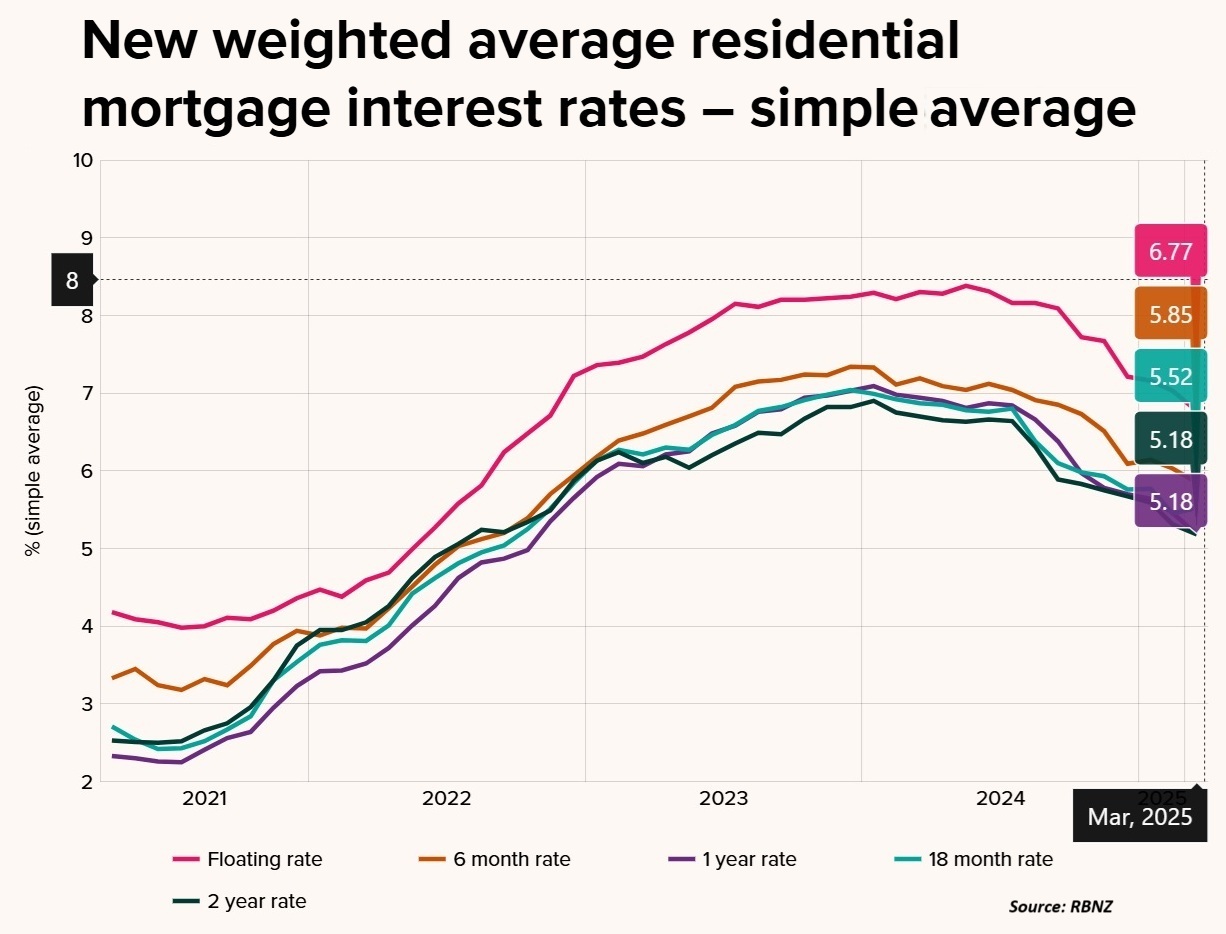
As of March 2025 one-year fixed mortgages became the most popular again among those owner-occupiers taking up new mortgage commitments in March. So, we’ll use one-year rates for example purposes in terms of looking at where rates have been and where they are now.
The RBNZ produces figures that show the weighted average interest rate of new mortgage commitments uplifted each month. So, this is a 'real average' of what's being paid.
The rates have been on quite a journey. The RBNZ figures show us that at the end of the cycle of very low interest rates before inflation went through the roof, the average weighted one-year mortgage rate bottomed out at 2.25% in July 2021.
But as the RBNZ cranked up the OCR in order to combat inflation that peaked at 7.3% in mid-2022, so, mortgage rates were forced higher quickly.
In January 2024 the average one-year weighted mortgage interest rate hit a peak of 7.09%.
However, by December 2024 the weighted one-year average was down to 5.70%.
And by March 2025 the figure, (latest available), was 5.18%.
The current popular advertised one-year rate of course is 4.99%. So good numbers of folk are signing up at that rate.
But that’s new mortgages.
The RBNZ collates the figures on what the banks' yields are on their mortgages to existing customers. And these figures demonstrate the lags we see between when rates are moved and when customers feel the impact of those moves.
These figures show that if we again look back to the pre-inflation surge mortgage rate figures, the low point for the yield across all mortgages was 2.83% in September 2021.
Breaking it down, the low point yield for fixed mortgages was 2.72% in September 2021, while for floating it was 3.62% in the same month.
Because of the lags between when rates were moved and when existing customers reset their rates, the yields for banks on the mortgages were still rising for some time after rates were 'officially' coming down.
In fact, the peak yield across all mortgages was 6.39%. And that wasn't hit till October 2024 - well after interest rates had been coming down. By December the yield across all mortgages was down to 6.29%, so, only a slow descent.
However, by March 2025, which is the latest date we have for figures, the yield was down to 6.00%. Very notably that was down from 6.18% in February - so, we are really starting to see some movement now. The ball is rolling. More and more people are feeling those lower rates.
And it is worth breaking down the figures a little further - to look at the yields on floating rates and the yields on fixed.
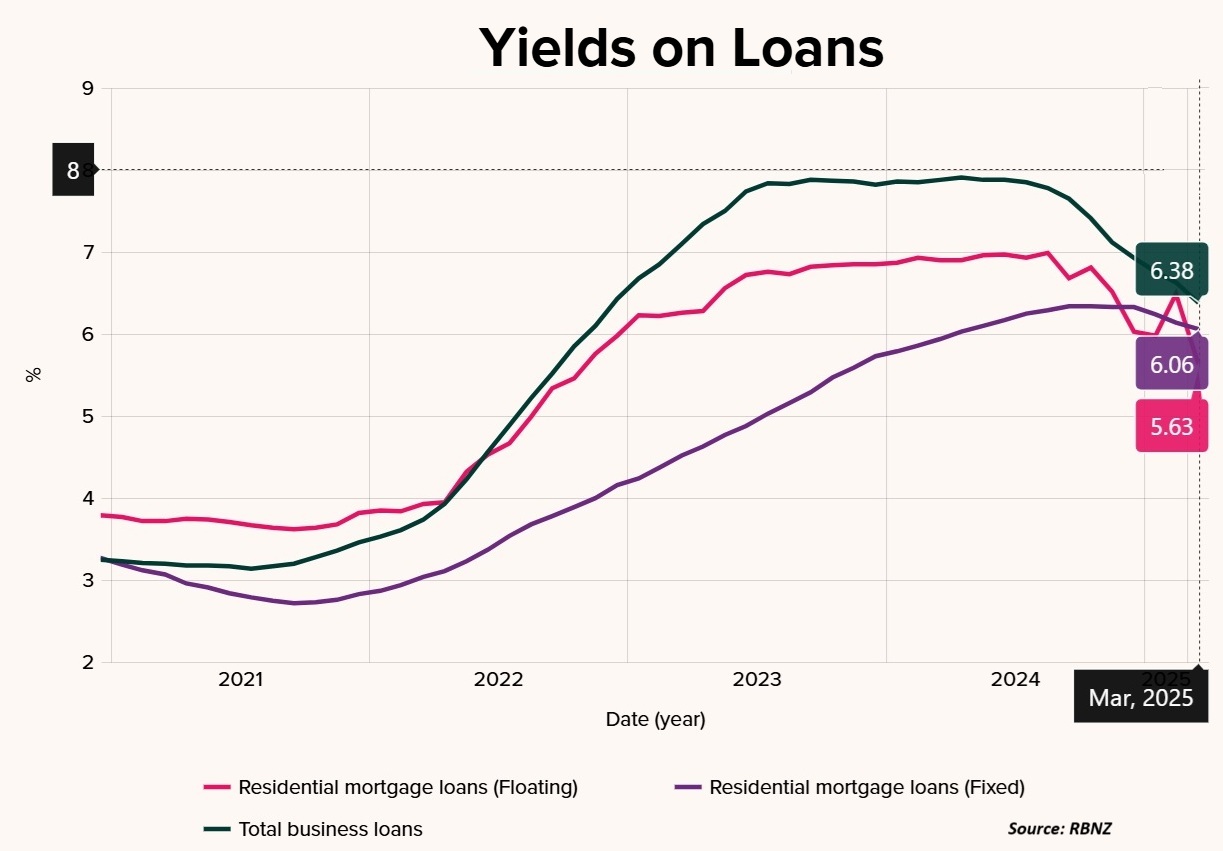
The peak yield on floating rates was 6.99% in August 2024. It was 6.03% by December 2024. And it was 5.63% by March 2025.
For fixed rate yields the peak was 6.34% in October 2024 and this one really did come down slowly. In December 2024 it was only down to 6.33%.
However, in March 2025 it was 6.06%, notably down from 6.14% in February and 6.24% in January. So, again things took time to get rolling. But they are rolling now.
And just for fullness of information, we'll throw in the yields on business loans (this doesn't include ones fully secured by residential mortgages). These had a low of 3.14% in July 2021, a high of 7.91% in April 2024 and by March 2025 were down to 6.38%.
How has this all related to what's coming out of people's pockets?
Well, looking broader, and through another RBNZ data series, we can see that the previous cycle-low point of mortgage interest charged by the banks in a quarter was in the September 2021 quarter, with $2.32 billion charged. Scheduled repayments that quarter (this includes both interest and principal repayment) were also at a low of $4.795 billion.
Once rates rose, the peak of interest charged was not actually reached until December 2024, with $5.804 billion interest and $7.666 billion scheduled repayments.
So, in layperson's terms, $2.871 billion more (in a quarter) came out of pockets for scheduled repayments at the peak of the interest rate cycle than there had been during the historic low times of three years earlier. And remember, this peak was as recently as the December quarter. The tide has taken time to turn.
What about the March quarter, 2025?
It's starting to come down
Well, the data shows us that the interest bill had reduced to $5.571 billion, while the scheduled repayments were $7.527 billion. That's a $139 million quarter-on-quarter reduction. So, it's starting to come down - but it's only just started to come down.
As of March 2025 the mortgage loan book of all outstanding mortgages was $373.993 billion.
Within this, some $150.161 billion - just over 40% of the mortgage pile - was, as of March, up for an interest rate reset by the end of September 2025. That's about $25 billion worth of mortgages every month up for a reset, which is a lot.
In addition, $48.33 billion of mortgages was on floating and so could be reset at any time as well. Which means that nearly $200 billion, just over 53% of the total mortgage book, could have an interest rate reset - at lower rates - by September.
Some people have already had a mortgage rate reduction and face lower payments.
A heck of a lot more people are due for that to happen within the next few months.
This will help. People will start to notice more money in the pocket and start to feel more confident.
What about the economy so far?
In terms of key economic data, the annual inflation rate was 2.5% as of the March quarter, tucked into the 1% to 3% range the RBNZ is charged with achieving. Our GDP emerged tentatively in the December quarter (0.7% rise) from the large hole it fell into in the June and September 2024 quarters. This was better than the economists' predictions. Our unemployment rate for the March 2025 quarter remained at 5.1% - better than economists' predictions and indeed the prediction of the RBNZ, which was for a rise to 5.2%. (Economists generally said 5.3%).
The current expectation is that our GDP will have grown again in the March quarter, although nobody's expecting that it's shooting the lights out. But growth is growth. It's a starting point. A very big bright spot in the economy has been dairy and meat exports and I suspect the impact that's having, and will have, on regional New Zealand is not yet being fully factored in by many of the country's economists.
But the point is that the signs of recovery are there. Slow and gradual, yes. But there. Much of the statistical information that's coming out about the economy so far this year has been BETTER than economists, and indeed the RBNZ, have expected.
And a word on the global turmoil? Well, surely we've just got to judge by events as we see them develop rather than trying to second guess.
From the RBNZ's perspective, should it really drop the OCR down a lot from here (some bank economists suggest it should go as low as 2.5% by the end of this year) when the signs are starting to show that the rate reductions already in place ARE starting to work?
Pivotal RBNZ review
The next RBNZ review of the OCR on May 28 will be pivotal. A further cut from 3.5% to 3.25% appears almost certain. But what the RBNZ indicates it will do next beyond that will be very interesting.
House market activity as measured by new mortgages is rising. The last time mortgage rates were low, this fired up the market. Now, admittedly we appear to be a very long way from such a situation at the moment. But the RBNZ would nevertheless not want to risk future recurrence of that at some point further down the track, nor would it want to see inflation start to meaningfully blip up again.
Banks would probably like to see continuing OCR falls so that they could continue to push down their mortgage rates and be able to compete to keep growing their market share, and hence profitability. Without further large falls in the OCR, it's hard to imagine banks pushing rates much lower than they are, although my hunch is we will still see rates in the low 4s by the end of this year.
Obviously much hangs with the RBNZ. It has to decide how much momentum the economy can start to build based on the OCR reductions we've already seen. Or whether significantly more is needed.
To my mind the RBNZ overcooked the speed and magnitude of OCR rises on the way 'up'. We wouldn't want to see it do the same in reverse on the way down.
*This article was first published in our email for paying subscribers early on Friday morning. See here for more details and how to subscribe.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.