
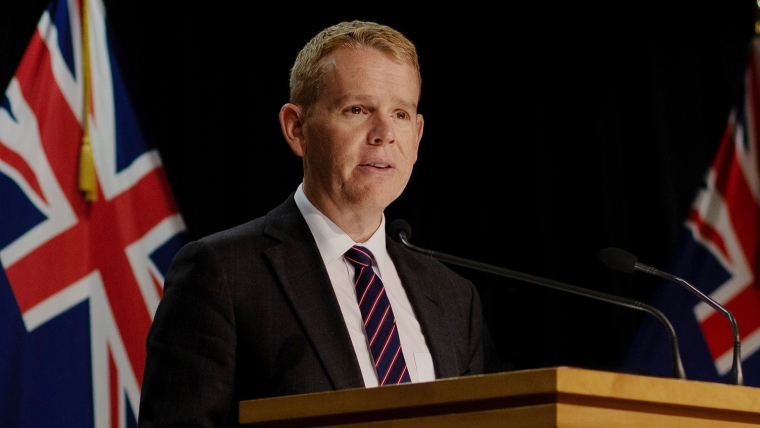
The path of future monetary policy will be partly decided by whether Chris Hipkins’ makes good on his promise to deliver a no-frills Budget that doesn’t exacerbate inflation.
The Reserve Bank of New Zealand (RBNZ) will likely end its rate hike crusade this month with one final increase to the Official Cash Rate in its May Monetary Policy Statement.
Recent data offers some signs that higher rates are cooling inflation but not to the extent that the RBNZ will be deterred from one last 25 point hike to reach 5.50%.
Consumer price index data for the first quarter of 2023 showed a decline in the rate of inflation—at 6.7% annually, down from 7.2%—although the improvement was mostly imported.
This was lower than forecast by the RBNZ, but not enough on its own to declare victory.
Labour market data released on Wednesday showed the unemployment rate holding on at 3.4% and private sector hourly wage growth up to 8.2% from 8.1%.
This was not such good news for the central bank, which had forecast a slightly higher unemployment rate and slower wage growth. It was, of course, good news for workers.
Taken together, the two data points don’t give much reason for the RBNZ to diverge from its plan to set the OCR at 5.50% and leave it there.
Stephen Toplis, BNZ’s head of research, said even then the central bank was unlikely to rule out the possibility of further tightening thereafter.
ANZ economists said while the slightly-stronger labour market wasn’t helpful for inflation, it wasn’t likely to lead to higher-than-expected interest rates.
“This very much a look in the rear-view mirror; and forward-looking indicators do signal waning labour market pressures over the rest of the year”.
The final instalment in this trilogy of data will be the government’s Budget 2023, set for release on May 18, which may also affect future monetary policy
No-thrills budget
Prime Minister Chris Hipkins’ pre-budget speech would likely have been moderately reassuring for RBNZ policymakers, according to BNZ economist Craig Ebert.
The speech committed to bring operating expenditure back down to near 30% of gross domestic product in coming years and promised the May budget would contain “no-frills”.
On the other hand, Hipkins ruled out any new tax changes, including a cyclone recovery levy which could have funded the rebuild without adding to inflationary pressures.
The Treasury has estimated the economic damage from the North Island floods and Cyclone Gabrielle could be between $9 billion and $14.5 billion, and add 0.4% to inflation.
Ebert said while Hipkins had ruled out “major” tax announcements, it did leave room for more minor tweaks to tax rates which could be inflationary.
For example, the Prime Minister has said income tax thresholds will have to be adjusted for inflation at some stage in the future. That would be more likely an election policy than a budget announcement, but would provide some economic stimulus if, or when, it happened.
Tax cuts of some sort would be almost guaranteed were National and Act to form a coalition government after October.
Ebert said RBNZ would be conscious of any potential stimulus, although it usually doesn’t factor anything into its macroeconomic forecasts until it is official government policy.
More relevant to the Monetary Policy Statement in May will be the actual spending levels contained in Budget 2023.
The path of monetary policy will be (ever-so-slightly) softened if Hipkins’ sticks to his word and the government can resist an election-year, lolly-scramble budget.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.