
ANZ New Zealand, the country's biggest bank, has posted a 9% fall in half-year profit after a significant rise in credit impairment charges on loans.
For the six months to March 31, ANZ NZ says its net profit after tax fell $94 million, or 9%, to $1.002 billion from $1.096 billion in the six months to March 2022.
The drop came as credit impairment charges weighed in at $121 million versus a release, or write-back, of $20 million in the March half last year, which included the release of provisions raised prior to ANZ's sales of UDC and shares in Paymark. The credit impairment charge was attributed to an increase in collectively assessed credit impairments, and higher individually assessed credit impairments due to lower write-backs.
A collectively assessed provision is established after an impairment assessment on a collective basis for a group of the same type of loans where losses have occurred but aren't considered individually significant. Individually assessed credit provisions are made when there has been a deterioration in the creditworthiness of an individual or entity. A write-back , or reversal, of an impairment loss reflects an increase in the estimated service potential of an asset since the date when the impairment loss for the asset was previously recognised.
Net interest income jumps
Operating income was up $346 million, or 16%, to $2.490 billion. Net interest income, the difference between the revenue generated from a bank's interest-bearing assets such as loans and the expenses associated with paying its interest-bearing liabilities such as deposits, surged $366 million, or 21%, to $2.127 billion.
Parent the ANZ Banking Group said the net interest margin for its NZ unit was 2.67%, up 34 basis points, attributed to favourable deposit margins from a rising interest rate environment. Its cost-to-income ratio was 35.4%, down 530 basis points.
ANZ NZ's operating expenses fell $15 million, or 2%, to $809 million.
"While a rising interest rate environment contributed to the result, this was offset by intense competition in home lending, which we expect to remain a feature of the market for some time into the future," ANZ NZ CEO Antonia Watson says.
"From talking to business customers across the country, confidence remains very subdued as high interest rates and escalating costs impact business profitability against a backdrop of weakening demand."
"Given the ongoing uncertain environment, we need to remain cautious, which is reflected in the increase in credit provisions," Watson says.
"ANZ NZ recognised a credit impairment charge of $121 million, and total credit impairment provisions increased to $860 million [from $739 million]."
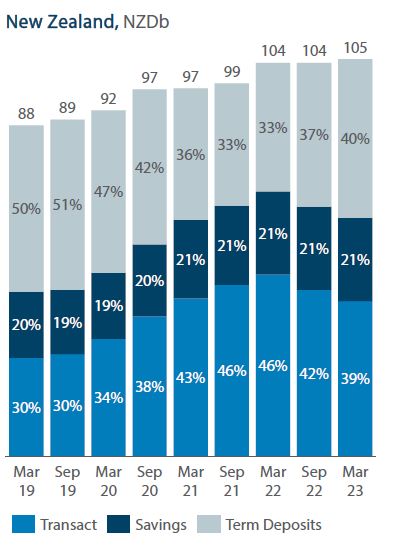
ANZ NZ's annual gross lending rose 4% to just over $129 billion, and its customer deposits increased slightly to $104.614 billion.
'Closely monitoring' how customers are managing
ANZ NZ says it has provided support to customers hit by floods and Cyclone Gabrielle with emergency access to more than $11 million of interest free funds, and has waived about $1.3 million in fees.
Watson says ANZ NZ is "closely monitoring" how customers are managing, especially as home loan borrowers move to higher interest rates.
"We have a team proactively contacting customers to make sure they're aware of their options to manage repayments and provide support for those who need it," she says.
"Fortunately, many of our customers took the opportunity to pay down debt while interest rates were low, and a third are ahead on their home loan by six months or more."
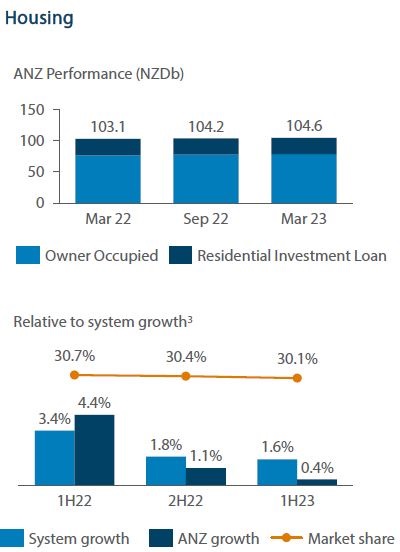
Customer deposits
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.