
The country's wholesale interest rates have become "too high and too expensive", according to Kiwibank economists.
In Kiwibank's latest First View publication, chief economist Jarrod Kerr, senior economist Mary Jo Vergara and economist Sabrina Delgado say they "would expect to see a fall" in wholesale rates, following the Reserve Bank's review of the the Official Cash Rate (OCR) this week.
The central bank is universally expected to leave the OCR unchanged at 5.5% after it published forecasts in late May showing it wasn't forecasting any more increases and it was forecasting the OCR to remain at the 5.5% level till the second half of next year.
Other than the “unchanged” announcement on Wednesday the economists we expect the RBNZ to reiterate a steady path ahead. They think the last line from the last statement in May will stay the same (or very similar. It was: "The Committee is confident that with interest rates remaining at a restrictive level for some time, consumer price inflation will return to within its target range of 1% to 3% per annum, while supporting maximum sustainable employment." (RBNZ MPS, May’23).
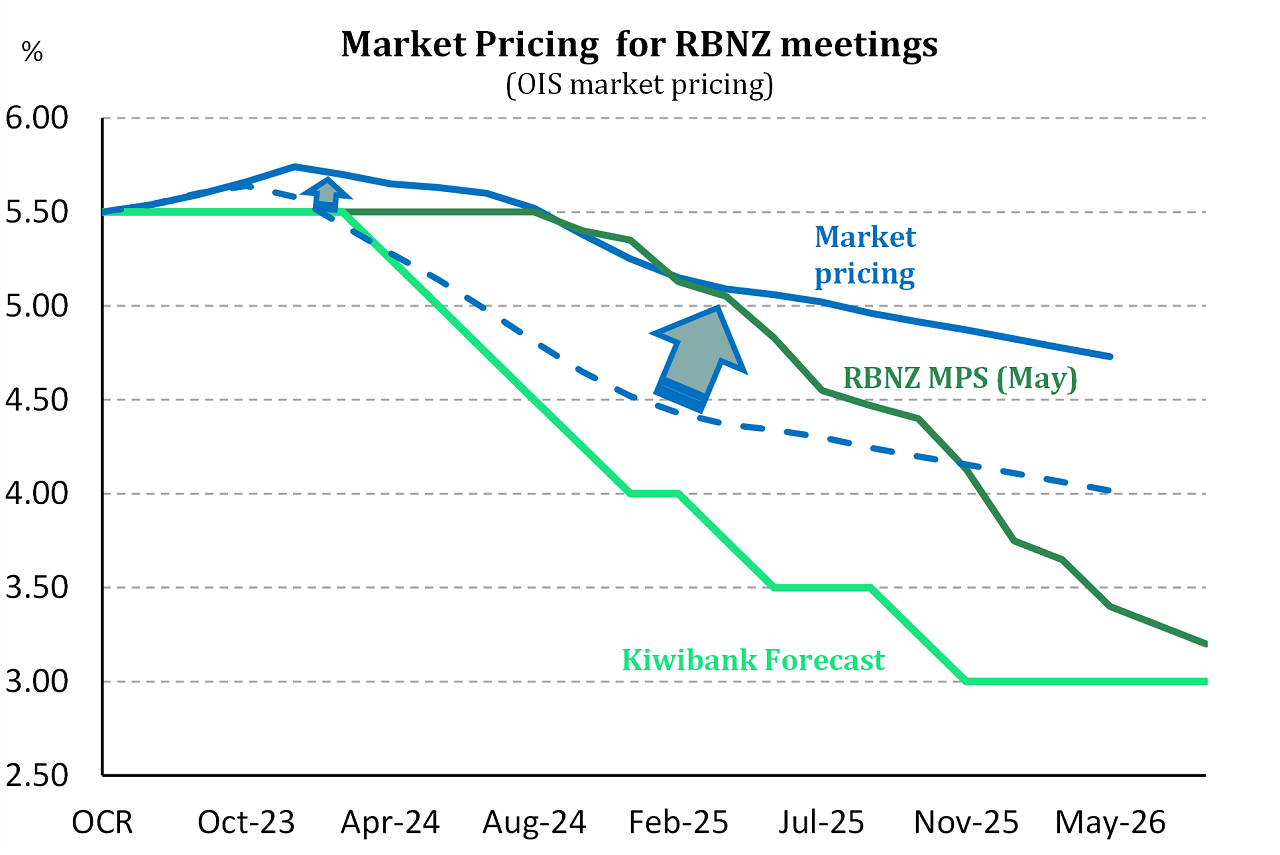
The economists say that wholesale rates "have lifted beyond the RBNZ’s own projected OCR track".
"Expectations for the terminal rate, or peak in the OCR, haven’t changed much. But the expectations for the RBNZ pause have pushed out a lot."
They note that the wholesale rate increases have pushed expectations of rate cuts back from February next year to October or November of next year.
"We think short end rates are too high, and too expensive. We think wholesale rates should fall back to where they were."
Where the wholesale rates were previously is denoted by the dotted line in the below graph:
Ross Weston, Kiwibank's Head of Balance Sheet – Treasury said the NZ wholesale yields had continued to lift "on offshore direction".
"In NZ there are +25 [basis points] of [OCR] hikes now priced into November which at this juncture feels unlikely to be delivered, with the first -25bp cut now pushed out to August."
Weston said "a punchy rinse and repeat" of the RBNZ's May OCR statement is largely expected, but the wholesale interest rate moves increase the chances "of a more forceful on hold message given the recent weaker data and increased mortgage holder pain".
Kerr, Vergara and Delgado noted that they had updated their NZ economic forecasts last week "but not by much".
This had included a 'double dip' recession forecast. While they had also noted that mounting migration means more demand, and higher house prices.
"We ultimately think inflation will fall far enough, and fast enough, to enable rate cuts from February next year."
They pointed to the Government Crown Accounts of last week as being supportive of this view.
"The Government’s coffers are a little lighter than expected. In the eleven months to May’23, tax revenue came in $2.2 billion below forecast at $103billion [largely due to lower corporate taxes] and points to a much weaker than Treasury-forecast economy."
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.