
By Roger J Kerr

All the lead indicators appear hunky-dory for the NZ economy this year, a continuation of free consumer spending, job security/opportunities on the income side, dairy prices rebounding and fairly robust confidence all round.
All too good to be true?
So what can go wrong?
As has been seen with the changes in the US and the UK over recent times, the world can deliver up totally unexpected outcomes and with that come unintended consequences, uncertainty and volatility.
What we do know is that inflation is no longer dead and the doomsayer commentators on this front have had to go back into hibernation for a few years.
Trumponomics coupled with higher oil prices could mean the Federal Reserve lifting short-term interest rates in the US sooner and by more than the current 2017 dot-plot of three 0.25% increases.
On the domestic front, the potential risks in 2017 that could disrupt the good times the NZ economy is enjoying right now, centre around:-
- NZ inflation increases at a faster clip than the RBNZ expect (as highlighted in last week’s commentary), resulting in earlier OCR increases and thus higher mortgage interest rates slowing spending from highly indebted homeowners.
- Chinese demand for Auckland residential property assets slows up considerably compared to recent years due to new regulations in China and NZ.
- Dairy prices reverse back down as global demand softens and supply has not really reduced that much.
- Local political risk starts to creep in from mid-year as business owners/investors postpone decisions on new projects as they do not know what a Labour/Greens coalition government could mean for the NZ economy. The markets will be watching the political opinion polls with keen interest over coming months.
- Global share markets tank on higher US interest rates and Chinese economic worries (similar to what occurred at the start of 2016).
- Our booming tourism sector gets hit by some unexpected event and confidence is lost.
I would not give any of these risks a high probability of occurring. However, investors and borrowers with interest rate risk need to be aware of them.
You know the world is upside down when the Premier of the Communist Chinese regime strongly advocates free global trade and the President of the largest open-market economy in the world is pushing anti-free trade and protectionism!
Any changes globally away from free-trade and more border protectionism are not good news for an economy like New Zealand’s, being so dependent on exports.
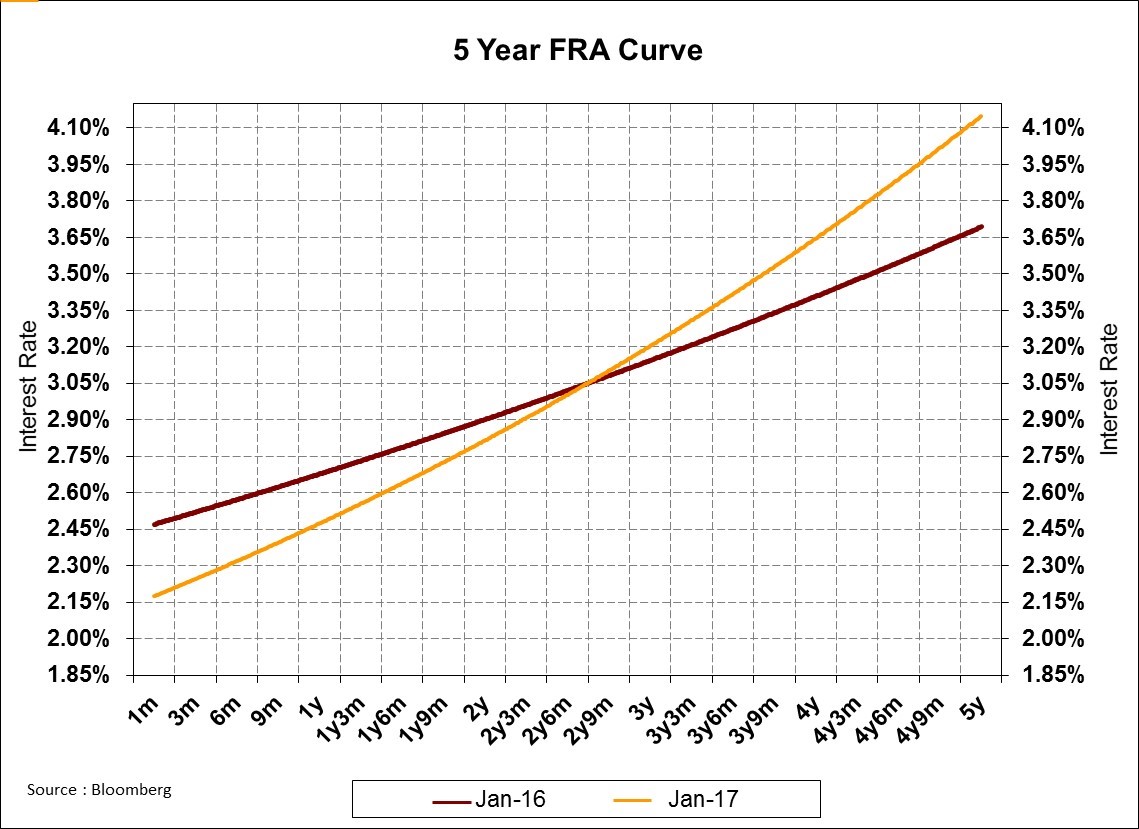
The forward curve on NZ 90-day wholesale interest rates has certainly changed from a year ago.
The moneymarkets are now pricing 90-day rates to be at 2.50% in 12 months’ time i.e. two 0.25% OCR increases. Perhaps the markets have gone too far with the speed of increases, or are they expecting higher inflation outcomes this year well above RBNZ forecasts? (Refer chart).
Daily swap rates
Select chart tabs
Roger J Kerr contracts to PwC in the treasury advisory area. He specialises in fixed interest securities and is a commentator on economics and markets. More commentary and useful information on fixed interest investing can be found at rogeradvice.com
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.