

The Reserve Bank (RBNZ) doesn’t need to keep printing money to buy government debt.
Since the onset of COVID-19, it has successfully suppressed interest rates and helped financial markets operate smoothly by buying bonds via its quantitative easing or Large-Scale Asset Purchase (LSAP) programme.
But bond-buying isn’t achieving much anymore, and the RBNZ best start preparing to move out of emergency response mode.
This is the (paraphrased) message from ANZ senior strategist David Croy.
He suggests the RBNZ winds back its bond-buying every week to the point it isn’t buying anything come September.
The market is in a position to absorb the debt the Treasury is issuing, without the RBNZ being a buyer of last resort.
What’s more, things could get confusing if the RBNZ continues printing money to buy bonds, while it hikes the Official Cash Rate (OCR).
Croy argues it would be better for the RBNZ to stop the bond-buying, take a breather, and then embark on tightening monetary conditions by hiking the OCR - possibly from as early as November.
Background
Going back a step, the RBNZ’s Monetary Policy Committee in March 2020 launched its LSAP programme.
In doing so, it committed to being a very active player in the New Zealand Government Bond market to suppress interest rates to boost inflation and employment, and prevent the market from freaking out at a time it was being flooded with new government bonds to pay for the COVID-19 recovery.
The RBNZ committed to buying up to $100 billion of New Zealand Government Bonds on the secondary market (not direct from the Treasury) by June 2022.
To date, it’s bought nearly $53 billion of government bonds.
It has been winding back its weekly bond purchases to $200 million, from well over $1 billion last year.
Croy suggests the RBNZ cuts this purchase rate by $20 million a week, until it isn’t buying anything come September.
RBNZ may as well keep some powder dry
He makes a technical, but important point - by stopping the bond-buying, the RBNZ wouldn’t be “cancelling” its LSAP programme ahead of its end date.
Rather, the programme would sit there, and RBNZ could "print money" to buy bonds again, if necessary.
But because the bond market doesn’t need the LSAP programme right now, the RBNZ may as well keep some of its powder dry should the economy take a turn for the worst in the future.
“In short - there’s limited ammo left; it’s not needed at the moment, so it’s better to put it back in the bag,” Croy says.
The bond market can handle it
He believes the market wouldn’t be overwhelmed by the Treasury continuing to issue a relatively high number of bonds for a few reasons:
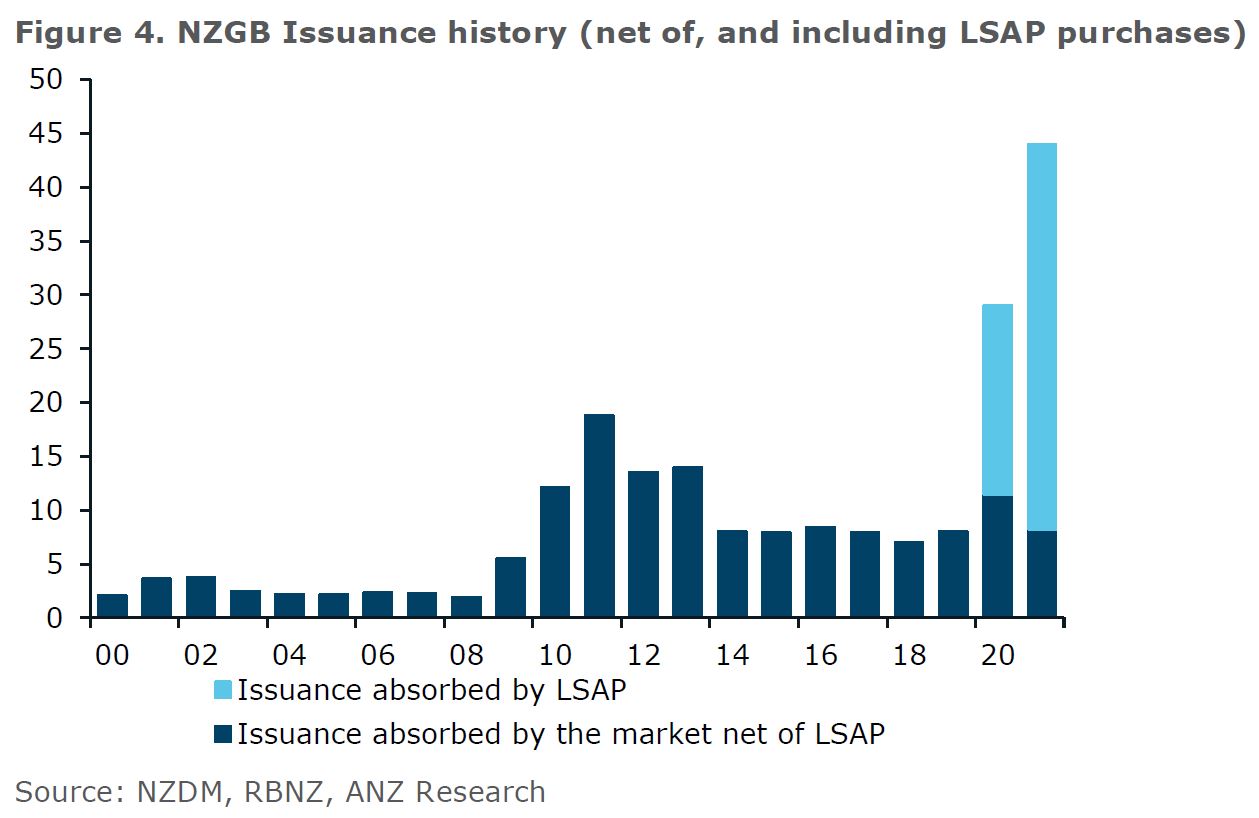
- It hasn’t actually had to absorb much debt to date, because the RBNZ has been there, buying around $53 billion of the $66 billion of bonds issued over the past 15 months (see graph below);
- The Treasury has just made a big pay out ($11.3 billion) for a matured bond;
- There is much more cash in the banking system than there was a year ago; and
- The Treasury is likely to revise down its forecast 2021/22 bond issuance programme from $30 billion, because the economy is doing better than expected.
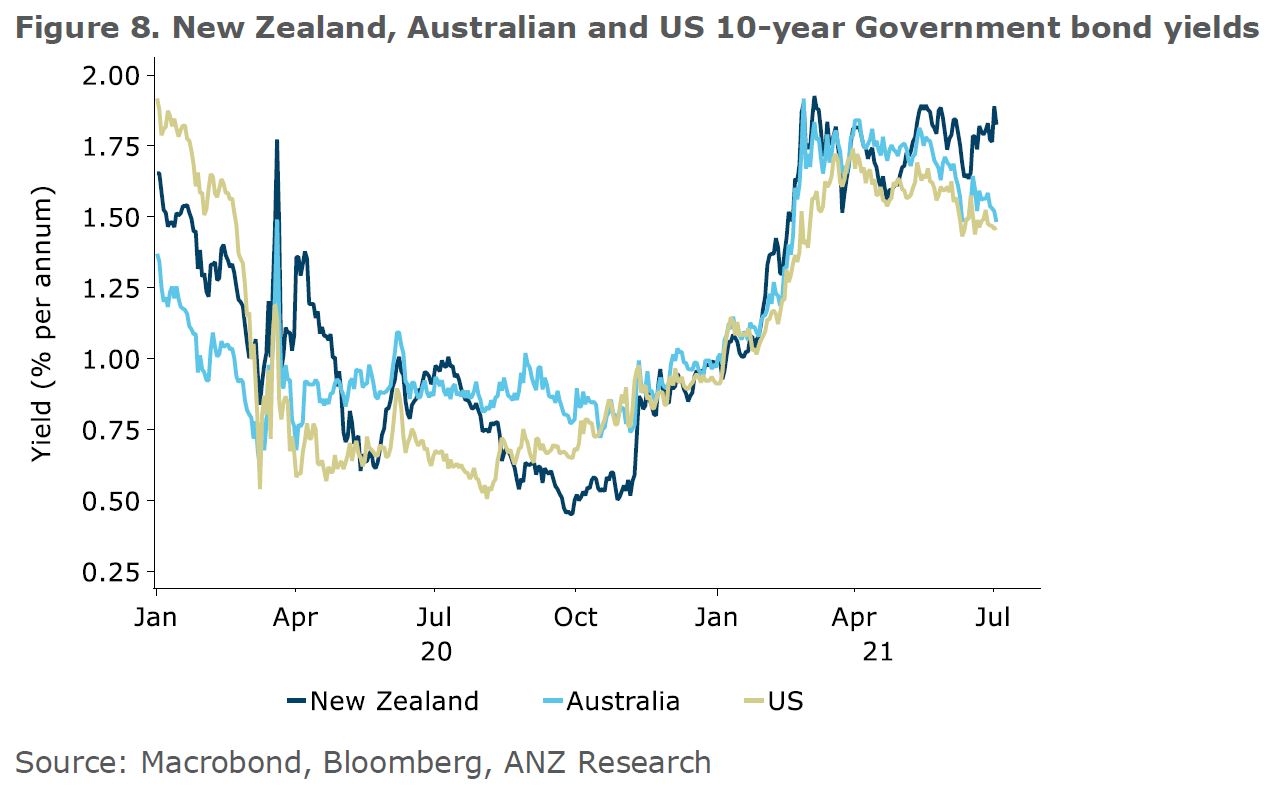
Croy also suspects winding down bond-buying wouldn't materially increase interest rates.
He notes New Zealand Government Bond yields have “remain joined at the hip with US and Australian bond yields”, despite the RBNZ reducing the pace of its bond purchases while its overseas counterparts have largely avoided talking of tapering.
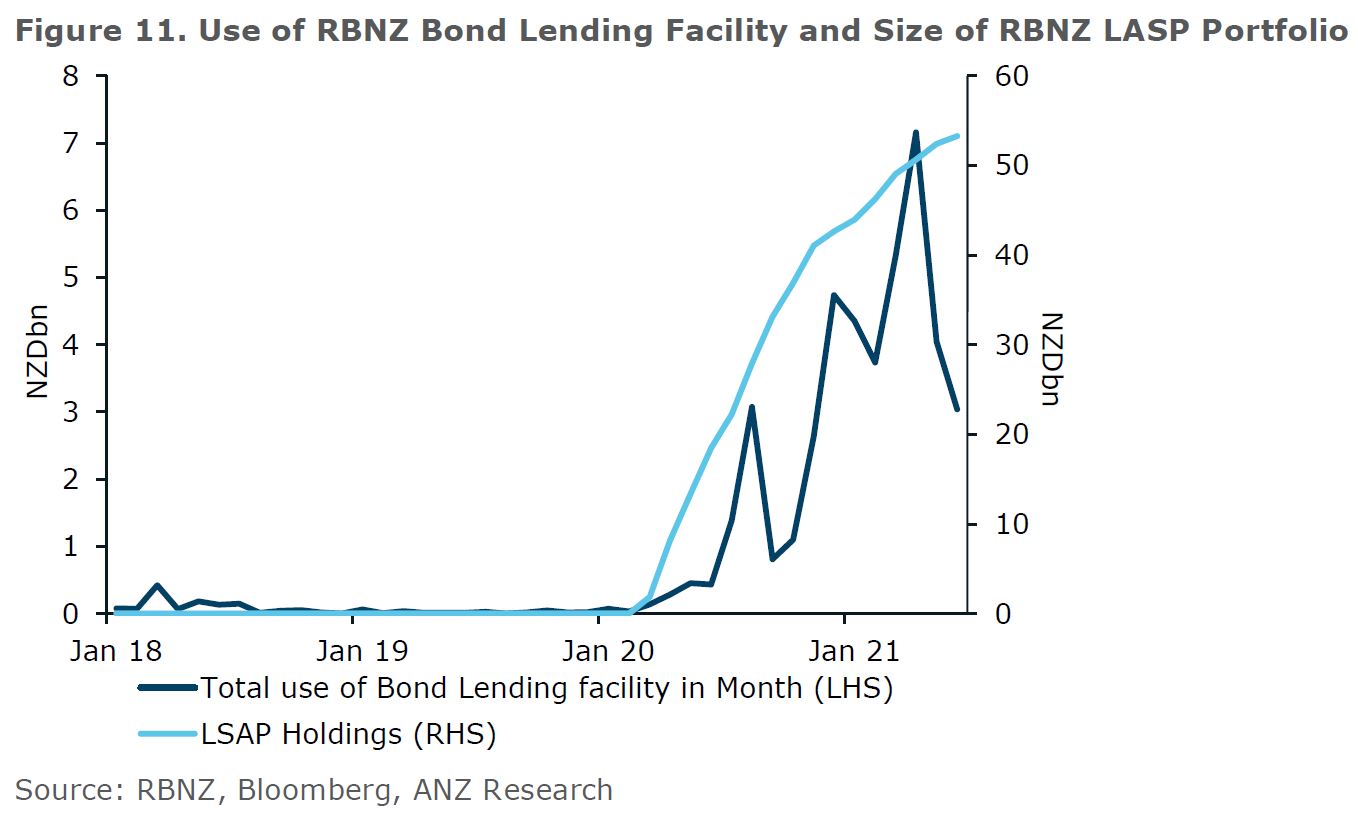
Another point Croy makes is that the uptick in banks’ use of a RBNZ bond lending facility could indicate the RBNZ is congesting the market by holding so many bonds.
The graph below shows the increased use of the facility, which banks tap into when they’re short a particular bond on any given day, because they’ve sold it, on-lent it, or don’t expect a deal to settle.
Clarity is key
Coming back to the point made earlier around the RBNZ avoiding mixed messages in the way it deploys its monetary policy tools, Croy believes it will follow the path set by the US Federal Reserve following the 2008 Global Financial Crisis.
The Fed signalled it would slow its asset purchase rate. It then issued a paper detailing the “principles” it would follow as it looked to “normalise” its balance sheet, before ceasing bond purchases and hiking its Fed funds rate.
Croy says the Fed gave markets plenty of warning around what it was doing, and expects the RBNZ to follow suit.
RBNZ will have to keep managing its large balance sheet
While Croy’s take-home message is that the RBNZ should wind down its weekly bond-buying fairly quickly, it’s important to note the RBNZ is likely to be an active player in the bond market for decades.
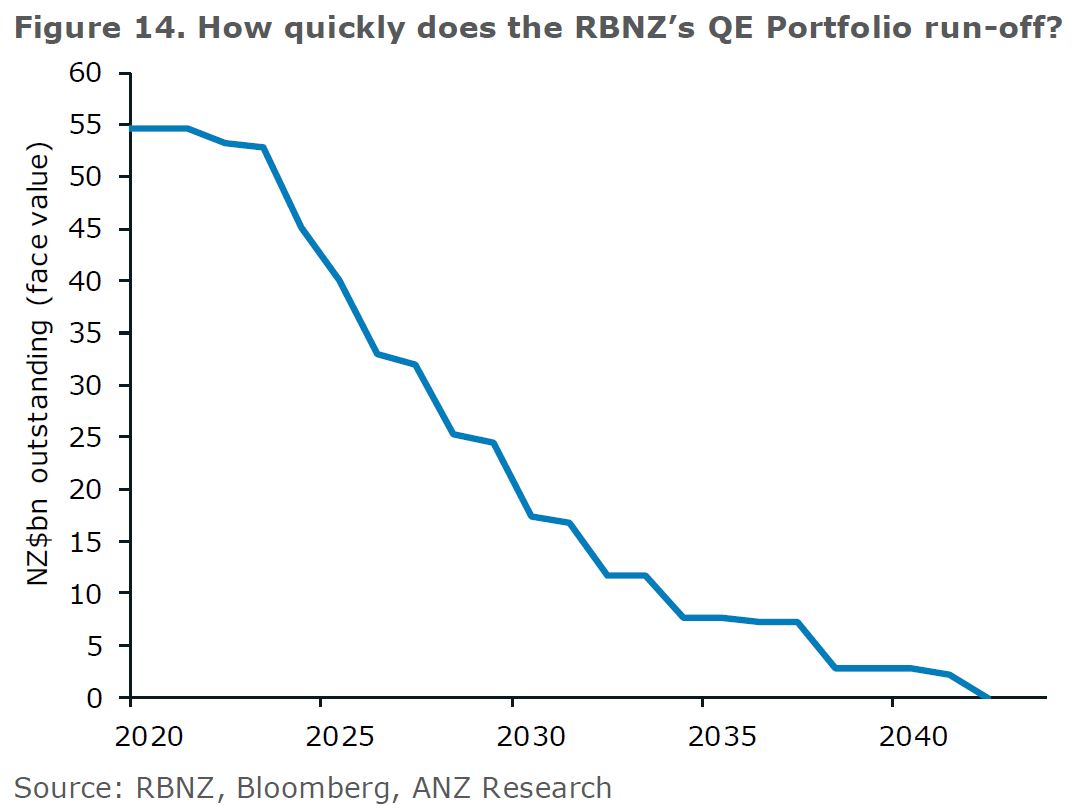
Croy acknowledges that even once the RBNZ stops “printing money” to buy bonds, it can’t necessarily just let its balance sheet shrink at the rate the bonds it owns mature.
The RBNZ might need to reinvest at least some funds from matured bonds. This is simply a feature of quantitative easing. The RBNZ now has a much larger balance sheet that it’ll need to keep managing.
The longest-dated bond it owns only matures in 2041.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.