
BNZ senior interest rate strategist Nick Smyth believes it would make sense for the Reserve Bank (RBNZ) to soon start selling some of the $54 billion of New Zealand Government Bonds (debt) it bought in 2020 and 2021.
This would help clear the decks, should the central bank decide to use bond-buying to lower interest rates again in a future downturn. The RBNZ might find it difficult to enter the market with a splash again, if it is already too dominant a player.
But, because the RBNZ is only allowed to sell the bonds it owns to Treasury, and Treasury doesn’t have enough cash to pay for a heap of purchases, it’ll have to issue more debt to cover the cost.
Larger bond issuances would put upward pressure on interest rates, which would align with the RBNZ’s goal of tightening monetary policy to lower inflation.
The RBNZ has said it wants to gradually shrink the size of its bond portfolio. It’s soon due to detail whether it plans to actively sell bonds or let them drop off its balance sheet at the rate they mature.
Smyth's case
Smyth, in a research paper published during the week, said he believed the RBNZ should start selling bonds to Treasury in the middle of the year.
He said the RBNZ could sell $5-10 billion a year. If it sold $7 billion in the year to June 2023, Treasury would need to increase its forecast bond issuance by the same amount.
This would bring Treasury’s forecast issuance back in line with where it was before December, when it cut its forecast issuance for the year to June 2023 to $18 billion.
Under the indemnity provided to the RBNZ by the finance minister when it launched its bond-buying programme, the RBNZ is only allowed to sell New Zealand Government Bonds back to Treasury.
While the RBNZ was required to buy the bonds on the secondary market (to stop it looking like the RBNZ was directly financing the Government), it isn’t allowed to sell them on the secondary market.
The condition exists to prevent sales made by the RBNZ causing market dysfunction. For example, there could be a problem if the RBNZ decided to sell a wad of its bonds at the same time Treasury did a big issuance.
The RBNZ is due to provide guidance on its bond portfolio early this year - possibly when it releases its next Monetary Policy Statement on February 23.
Meanwhile Treasury is next due to revise its forecast bond issuance programme at the May Budget. Hence, Smyth believed a start date of July for the bond sales made sense.
He didn’t believe Treasury flip-flopping on its forecast issuance was problematic.
Furthermore, he maintained there would be enough demand in the bond market to absorb the higher issuance, particularly if New Zealand Government Bonds qualify for inclusion in the World Government Bond Index.
Smyth believed it would make sense for the RBNZ to sell its longer-dated bonds, as those with shorter maturities are due to roll off its balance sheet soon anyway.
OCR hikes could be slowed - maybe
As for the impact on interest rates, Smyth said RBNZ bond sales would point to a steeper New Zealand Government Bond yield curve.
Treasury issuing more bonds would also put upward pressure on longer-term yields.
Accordingly, Smyth said the RBNZ might not have to increase the Official Cash Rate (OCR) as much as it otherwise would’ve, but this “remains to be seen”.
The RBNZ has said that looking ahead, it prefers to set monetary policy using the OCR.
NZ different to the US
If the RBNZ did what Smyth suggested, it would be a world leader. The Reserve Bank of Australia and United States’ Federal Reserve, for example, are only just due to stop their bond purchases, let alone start sales.
But Smyth noted that unlike the Federal Reserve, which owns bonds with a range of maturities that will naturally drop off its balance sheet regularly, the bonds the RBNZ owns will mature in lumps.
Furthermore, the first big tranche of New Zealand Government Bonds the RBNZ owns only matures in April 2023.
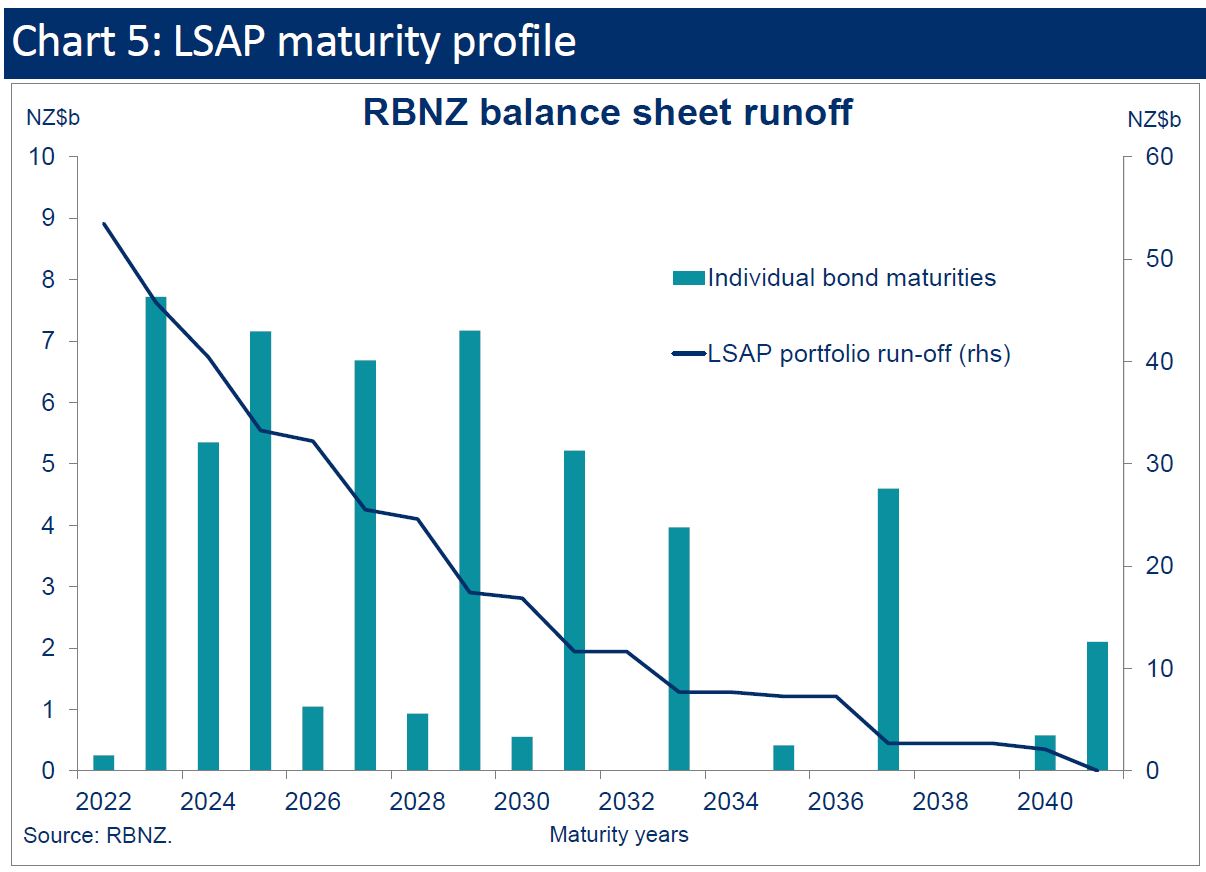
If the RBNZ only let the bonds drop off its balance sheet as they matured, it would still hold over 20% of the New Zealand Government Bonds on issue by mid-2026.
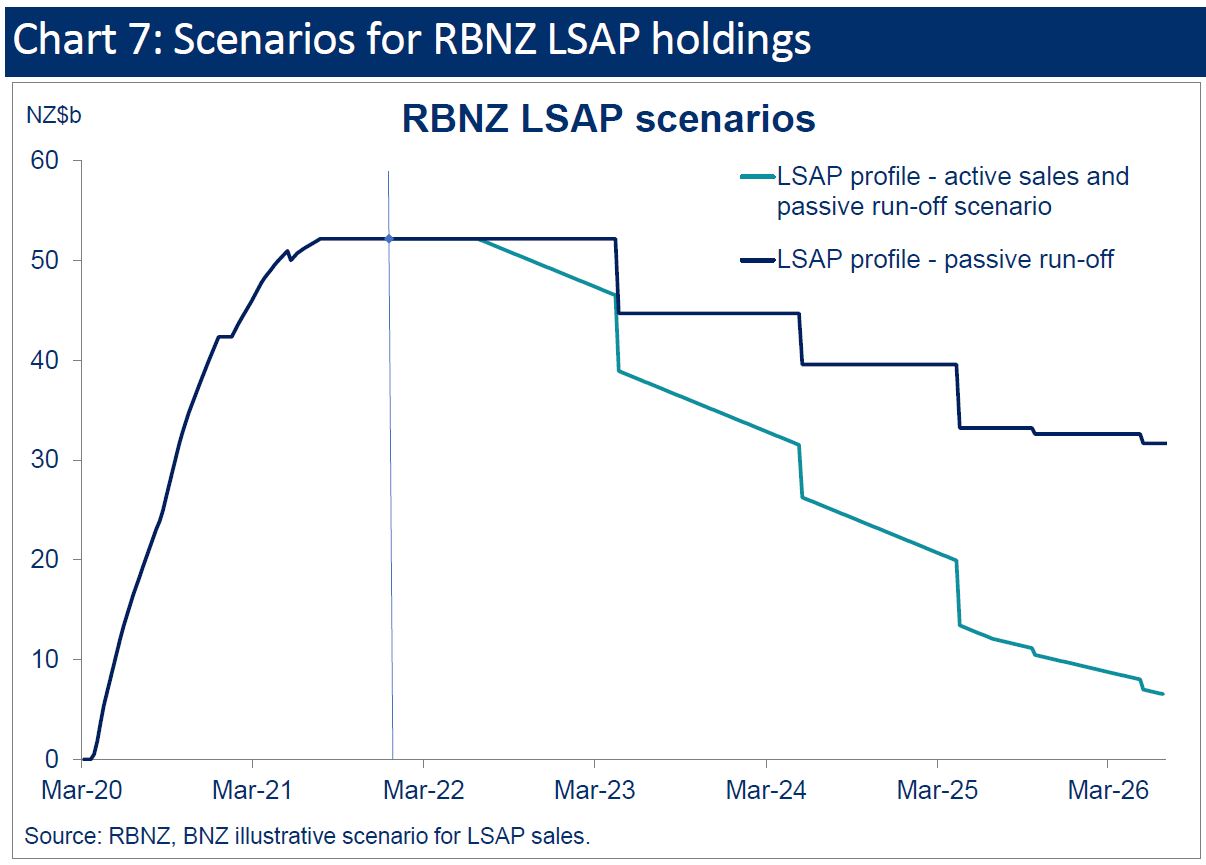
The bigger a player the RBNZ is in the market, the less capacity it has to intervene again to put downward pressure on interest rates.
Smyth expected the RBNZ to give itself some flexibility, making sales contingent on the economic outlook and market function.

We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.