
 By Roger J Kerr
While the debate continues throughout New Zealand as to what policy changes could or should be enacted to bring down the value of the NZ dollar exchange rate, the free-floating currency’s pricing in the forex marketplace remains within a relatively tight trading range.
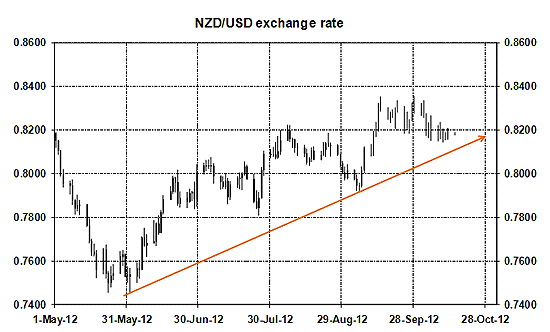
The NZD/USD has not returned to the highs of 0.8350 seen in mid-September; however every attempt to sell it lower over recent weeks has been met with firm buying interest.
The result is a period of relative stability for the Kiwi, albeit at levels well above 0.8000 that makes life tough for many in the export sector without adequate hedging on board through this period.
It feels like the next significant movement will be lower to below 0.8000, however there needs to be a catalyst that breaks the current shackles.
Looking ahead over coming weeks and months, the following factors are sees as providing the impetus and maybe the catalyst for future NZD direction:
Australia/China:
The expected sharp pull-back in the AUD/USD rate to below $1.0000 (which the NZD/USD rate follows) has been stalled over recent times by the US monetary policy QE3 action which temporarily weakened the USD and pushed hard commodity prices higher.
Given lower Chinese and overall global GDP growth forecasts, it is difficult to see commodity prices holding their recent gains. Chinese GDP data later this week may be lower than the 7.8% growth forecast and therefore could provide the next pointer for commodity prices.
Commodity inventory levels for coal, iron ore and aluminium generally remain high, thus prices are unlikely to be increasing with weaker industrial demand.
Weaker Australian economic data is anticipated between now and the end of the year, however last week’s jobs data was better than expected.
The AUD/USD and NZD/USD rates are approaching key support levels; a breach below could ignite further selling of both currencies (see chart below). The moneymarkets in Australia are still pricing-in another 0.90% of interest rate reductions over the next 12 months on top of the recent 0.25% cut in their OCR to 3.25%.
Lower interest rates and lower hard commodity prices continue to be negative for the Aussie dollar.
Europe and the euro:
The EUR/USD exchange rate has again failed to hold above $1.3000, however there have to be fresh and new reasons for the markets to buy dollars, sell Euro’s.
The ECB have not yet cut interest rate again, however it appears inevitable that they will do so soon. European bond markets have stabilised and the ECB’s “whatever it takes” rhetoric has worked so far to calm markets and has brought down borrowing costs for the Italian and Spanish Government on new debt issues.
However, Euroland is in economic recession with major debt problems that are not easily resolved. The EUR/USD rate is more likely to return to $1.2200 than move back above $1.3000 in such economic conditions.
Global manufacturing:
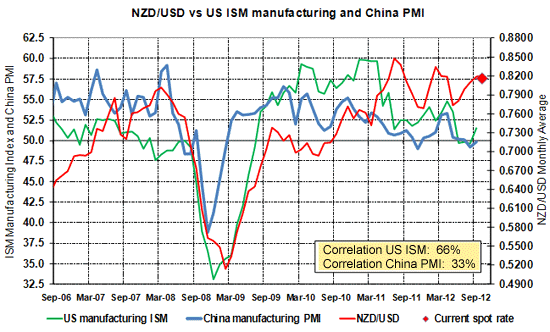
Both US and Chinese Performance of Manufacturing indices recovered somewhat in September after recent falls.
However, overall global manufacturing confidence indices are still trending down and the NZD/USD exchange rate has a reasonable correlation to the PMI figures (see chart below).
Safe-haven investment related buying of the Kiwi and Aussie currencies in May/June, when Europe had one of its bouts of crisis, caused the NZD/USD rate to remain well above where the PMI lead-indicators suggest.
Realignment seems likely.
Global sharemarkets:
Extraordinarily low returns for investors on bond yields, coupled with quantitative monetary easing around the place have propelled sharemarkets higher in 2012.
Given the strong gains by the equity markets to date, lower global growth forecasts and generally lower than expected US corporate earnings in the last reporting round, the direction of sharemarkets over coming months is more likely to be a downward correction than further gains.
The NZD/USD rate remains highly correlated to the Dow Jones Index and falls in the Dow to below 13,000 would stimulate NZD selling as investment markets move to a “risk-off” mode.
As readers will observe, all the above international factors are outside anyone in New Zealand’s control or influence.
Talk of exchange rate policy changes, monetary policy changes and intervention by the RBNZ to sell the NZD lower in the FX markets here is completely futile against global currency traders, speculators and investors who buy and sell the AUD (thus the NZD) on the above-listed variables.
The short to medium term view is that the aforementioned external drivers will determine the NZ dollar direction downwards, not what anyone says or does in New Zealand.
------------------------------------------------------------------------------------------------------------------------------
To subscribe to our daily Currency Rate Sheet email, enter your email address here.
------------------------------------------------------------------------------------------------------------------------------
* Roger J Kerr is a partner at PwC. He specialises in fixed interest securities and is a commentator on economics and markets. More commentary and useful information on fixed interest investing can be found at rogeradvice.com
No chart with that title exists.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.