
 By Roger J Kerr
Every man and his dog are expecting our short-term interest rates to increase by 2% over the next two years.
How quickly they might increase depends on the NZD/USD exchange rate which in turn determines the inflation rate the RBNZ are mandated to.
The question is whether borrowers are prepared for and thus hedged against these increases.
In the corporate borrowing world most companies run interest rate hedging policies that require them to be well over 60% fixed and fixed out to 10 years forward in various proportions.
However, there appears to be much less preparedness against the looming market risk in the home mortgage borrowing space.
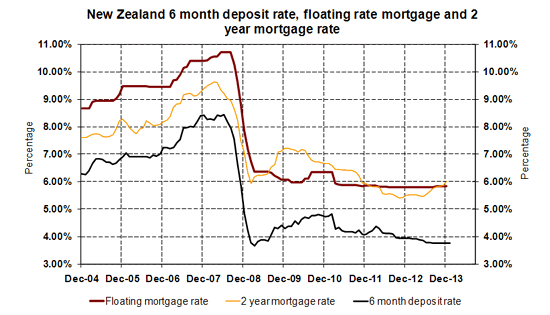
Current RBNZ statistics reveal that 75% of home mortgage borrowers are either variable rate (floating) or are fixed for a period less than 12 months.
In corporate borrower interest rate risk management language “floating” rate risk is any interest rate re-set/re-pricing within 12 months.
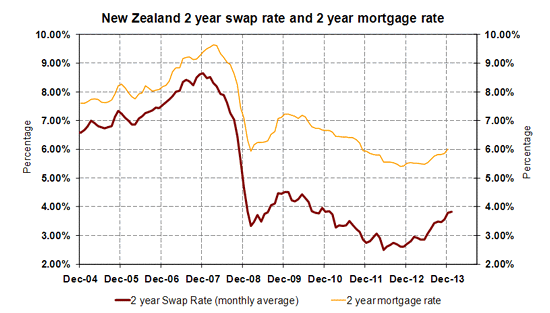
History tells us that the majority home mortgage borrowers just go for the lowest rate on offer and 5.75% floating lending rates right now are less than the 6.29% two-year fixed rate offers. Clearly, the home mortgage borrowers are betting that average floating rates over the next two to three years will be less than 6.29% to 6.60%.
Alternatively, they know the mortgage rates will be increasing and are taking advantage of the current lower floating rates to build up cash reserves to pay for the higher interest costs later on.
However, as many will testify, such cash reserves tend to get spent on the latest toys that are available.
On the assumption that floating/variable mortgage lending rates continue at a 2.90% margin over wholesale market 90-day interest rates, by the end of 2015 floating mortgage rates could be as high as 7.75%.
Why then are there not more mortgage borrowers fixing two and three years today at 6.29% and 6.60%?
Must be that many are so highly leveraged against their house values/incomes they cannot afford 6.60% or they just do not believe that short-term rates will increase.
These borrowers must also believe that the rock star economy will keep the NZD/USD rate high and inflation low.
Seems to me a lot of risk is being taken here, which is one reason why consumer spending over the next two years may not be as buoyant as many currently predict.
-----------------------------------------------------------
To subscribe to our daily Currency Rate Sheet email, enter your email address here.
No chart with that title exists.
Roger J Kerr is a partner at PwC. He specialises in fixed interest securities and is a commentator on economics and markets. More commentary and useful information on fixed interest investing can be found at rogeradvice.com
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.