
By David Hargreaves
So, we can take it as a given that the Reserve Bank's loan to value ratio (LVR) restrictions will celebrate their fifth birthday later this year - and right now it's difficult to see them ever being removed in their entirety.
If there had been a genuine appetite on the part of the RBNZ to say farewell to the - let's face it, supposedly temporary - LVR rules then it might have been imagined the central bank would at least signpost the possibility of following up on January's slight loosening of the rules.
Instead, the latest Financial Stability Report and ensuing media conference on Wednesday appeared to highlight a central bank that's happy with the job the rules have done and unwilling to part with them in the near term, if at all.
The LVRs, lest we should forget, were created in 2013 and officially brought into usage as of October 1 that year.
The initial iteration was through a 'speed limit', allowing just 10% of new lending by banks to be for house purchases with deposits of less than 20%.
This was followed by an ill-starred Auckland-centric move in 2015 that saw the general 'speed limit' of 10% retained in the largest city and with the additional impost of a 30% deposit rule for Auckland property investors. Outside of Auckland the general 'speed limit' was lifted to 15%.
There was virtually no impact on the Auckland market - while the loosening of the rules outside of Auckland poured petrol on the housing markets elsewhere, very probably assisted by 'Auckland' investor money looking for easier targets.
So, then there was 2016 in what I still think was at the time a kind of panicky last resort - but which has seemingly done the trick. This was the blanket introduction of a 40% deposit rule for investors right round the country, while the general owner-occupier 'speed limit' was put back to 10%.
In relaxing the rules from January 1 the RBNZ has shifted the investor deposit limit down to 35% and relaxed the general speed limit to 15%.
Being the naturally cautious body that it is, the RBNZ was always likely to want to give itself more than six months of observing how things are going after the relaxation of the rules before deciding whether to go the well again.
And it is true that the RBNZ likes to keep things close to its collective chest.
Notwithstanding that though, the language in both the latest Financial Stability Report document and at the media conference suggested that the RBNZ feels it's holding a reasonable hand of cards at the moment and it's not prepared to lay that hand on the table.
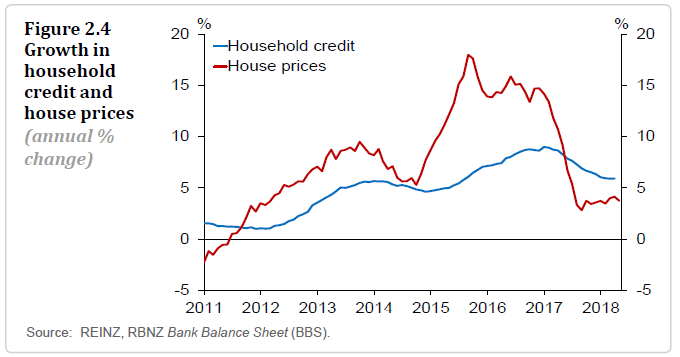
It's instructive to look at what's happened both to the housing market and borrowing patterns through the three evolutions of the LVRs. After the first implementation in 2013, the general speed limit, the housing market did cool. But, and it's a very big but, during the same period the RBNZ hiked interest rates four times in the belief that inflation was just around the corner. It wasn't and the hikes were reversed - but there can be no question they will have contributed to the cooling of the housing market in that 2013-14 period.
So, then to 2015 and the Auckland-centric move. Basically Auckland investors said 'is that all you've got?' and carried on, while elsewhere the loosening of the rules seemed to act as a definite spur to people to start climbing in boots and all, with the result that what had largely till then been an Auckland-led boom became more country-wide.
And then there was the 2016 move, tightening up the general speed limit and bringing in the heavy artillery against the investors nationwide. Call it desperation, call it what you will. But it worked. In fairness again though this did coincide with a squeeze on bank funding and a move to a far more cautious lending strategy on their parts.
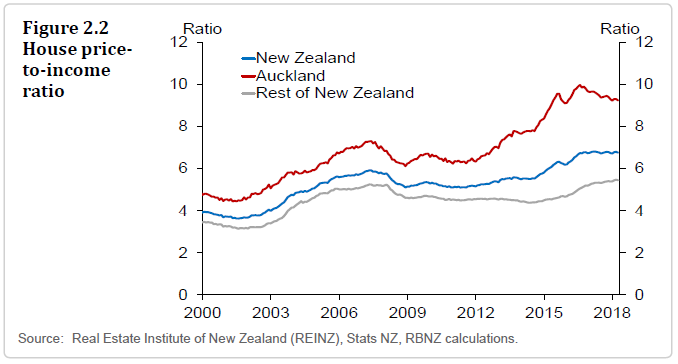
The really interesting thing about the 2016 move though is that if the whole market had been clobbered then it could be imagined that the RBNZ would be under huge pressure to lift the LVR restrictions totally.
The real focal point or, if you will, leverage in all this has been provided by the first home buyers. They are the public face of a distorted housing market. The victims. As people most likely to be wanting to borrow more than 80% of the cost of a house these were the people always most likely to be affected by a blanket 'speed limit' on high LVR lending. And so that seemed to be the case from 2013 onwards.
Unfortunately the RBNZ's excellent new mortgage lending by borrower type figures didn't appear till mid-2014 - so, it becomes anecdotal how the mortgage market share broke down before then. What we can say is that the monthly figures in 2014 showed the FHBs making up slightly less than 10% of new mortgage lending. Investors at that time were making up just under 30% of the total - but this soon moved to in excess of 30%. In Auckland it was higher.
By mid-2016, the FHBs, possibly helped by the relation of the overall LVR speed limit outside of Auckland, had lifter their overall share of borrowing to around 11%. But the investors were storming. They were up to about 35%.
So out came the RBNZ blunderbuss. By the end of last year the FHBs were up to a 15% share of overall lending, while investors' share had shrivelled to under 21%
What happened following the January relaxation of the LVR rules was therefore always going to be very important.
The latest available figures are for April. These show that the FHB's share has risen to a new high of over 16%, while the investor figures have recovered a bit too - at about 23.5%.
Now, anybody worth their salt will tell you percentages alone can be a bit meaningless. The most meaningful detail in all this is the fact that the actual amounts borrowed by FHBs have stayed remarkably consistent month-by-month even as the amounts borrowed by investors have fallen by hundreds of millions. In April 2016 prior to announcement of the third instalment of LVRs, the FHBs borrowed $789 million. In April this year they borrowed $868 million.
Contrast this with the investor grouping, which in April 2016 accounted for $2.182 billion worth of new mortgage borrowing, but in April this year totalled just $1.264 billion.
This is hugely significant because the FHBs are politically loaded. They've been used as the justification by various vested interest parties as to why the LVRs should be removed.
The fact is though - whether this was by design, or as I suspect an accident - the 2016 changes to the LVRs have tilted the balance back somewhat toward the FHBs and where they were previously being outbid by grey-haired baby boomers they now have a fighting chance again.
As I say, this is all hugely political. The idea of the future of the country being locked out of homes is a very bad look for anybody interested in winning a general election.
So, there would be satisfaction all round at the moment, firstly though the fact that the housing market has gone quiet but secondly and most definitely that the FHBs are in there and managing to get homes.
Why would anybody want to change that?
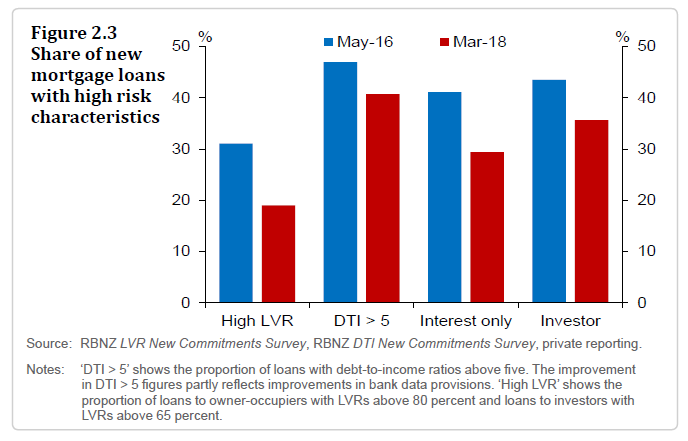
The Reserve Bank reiterated the point it has made previously that only about 8% of NZ households have investment properties - but they account for 40% of housing debt.
I think there is room for argument as to whether investors really are a bigger risk to financial stability in a serious housing downturn - but the RBNZ certainly believes that.
Therefore there is every reason to believe it would be keen to see the indebtedness of investors drop.
That's why I can't see any chance at all that the RBNZ will want to let the higher deposit limit on investors go at the moment. I think that is going to be in place for a very long time and I can't see it being reduced any further from the current 35% level.
As for the general overall speed limit of 15%, well, the key point (and sorry to hammer this) is the fact that the FHBs are now managing. Why therefore loosen it further?
RBNZ Governor Adrian Orr said the central bank would wait "at least" till the next Financial Stability Report in November before addressing possible further relaxation in the LVR rules.
Personally, I think there's no chance at all there will be relaxation in those rules this year.
And really, with a housing market currently in check but not going wildly backwards, I see no compelling reason for the RBNZ to loosen the rules any further.
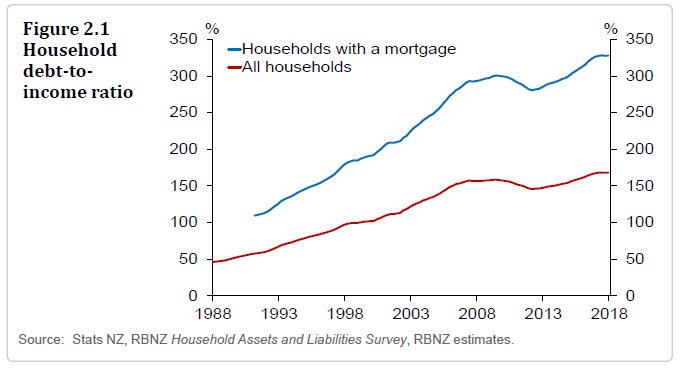
The other big point to consider is that the RBNZ is still very keen to get some sort of debt-to-income or debt servicing instrument added to its repertoire of 'macro-prudential tools' (of which the LVR measures are one).
The previous National-led Government pushed back against such a measure and the new Government has shown no appetite for it either.
To me, it's logic to have a DTI of some description available. I think the RBNZ will keep working away on this one.
Is there a potential some way down the track for a bit of a trade-off? 'We get our DTI and you get a further reduction in LVR restrictions?'
It's got to be at least a possibility, surely. Why then would the RBNZ give up the current state of the LVRs without perhaps some sort of trade off occurring?
Either way, whether the LVRs are relaxed further or not (and as I say, don't hold your breath for this year), I now think they will never be completely retired.
Indeed, outgoing Acting RBNZ Governor Grant Spencer alluded to such an idea in his final major speech before retiring from the role in March, suggesting that tools such as LVRs could either be switched 'on' or 'off' but would remain established within banks’ reporting and compliance systems.
The LVRs are here for good and I wouldn't bet against the RBNZ getting its DTIs too - eventually.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.