
It's nearly time to get the popcorn ready.
This coming Wednesday (May 24) the Reserve Bank (RBNZ) will be having its latest review of the Official Cash Rate (OCR). The recent history of these announcements suggests it won't be dull.
My best guess (and your guess is as good as mine) is that the RBNZ will increase the OCR by 25 basis points (bps), taking it to 5.5%, the highest level since December 2008.
Assuming that's what happens, this will be the 12th consecutive increase to the OCR since the beginning of this tightening 'cycle' in October 2021 and it will mean the cash rate has been raised - at unprecedented speed - by a thumping 525 bps from its pandemic low of 0.25%.
And if Wednesday's increase is 'merely' 25 bps this will follow eight consecutive hikes of at least 50 bps (with a 75-pointer thrown into the mix for good measure in November 2022).
The big question will be: What comes next?
Well, hopefully, we will get a few clues thrown our way.
This Wednesday's review will be accompanied by the RBNZ's latest Monetary Policy Statement (MPS) - so, the RBNZ's got plenty of scope to outline its current thinking and how it feels its strenuous efforts to rein in inflation are going.
Of vital interest will be the forecasts contained right at the back of the MPS.
The last MPS was issued in late February. To refresh memories, here's an abridged table of the main forecasts made then. (The full table appears on page 57 of the MPS.)
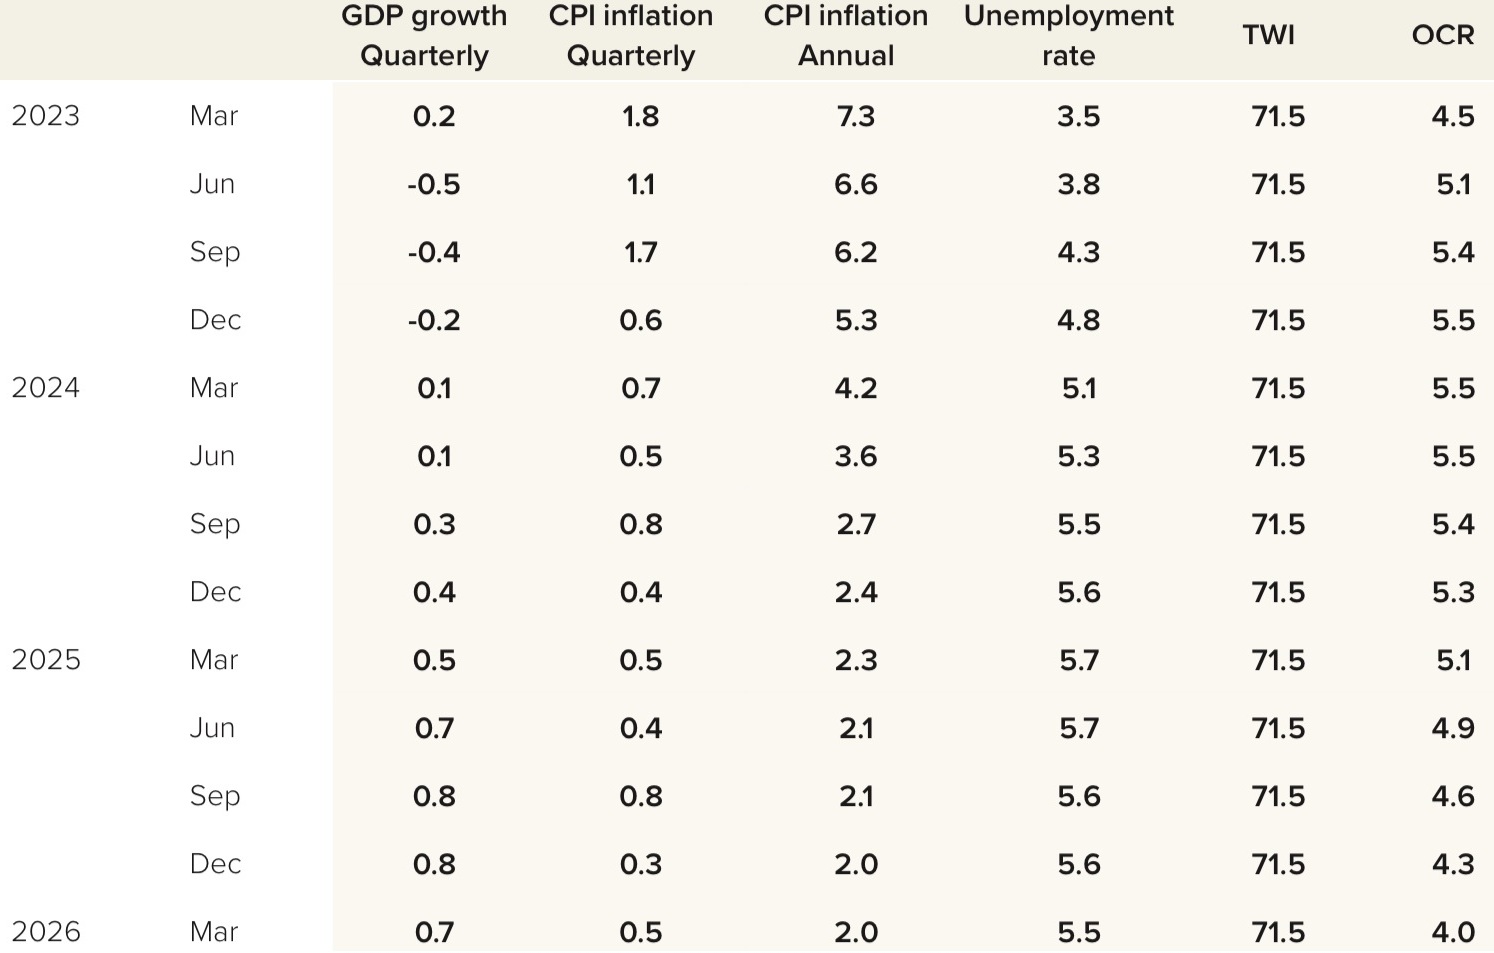
Okay, so, the big thing on Wednesday is going to be looking at the latest set of forecasts and how they differ from those made in February - because they will. Actual economic developments since February demand that.
The first thing everyone will want to look at is that forecast figure on the far right - for the OCR. As can be seen from the table above, the RBNZ was forecasting the OCR to peak later this year at 5.5%.
So, if we do indeed get a 25 bps increase on Wednesday then we will be there. Already. The OCR will have hit what the RBNZ indicated was going to be the peak. Journey over. Apparently. But really?
Will the RBNZ want to give the impression it has definitely 'finished' with rate hikes? Hmm. I doubt it. Not when it will be all too aware of the 'market's' inclination to start pre-empting interest rate reductions.
Therefore there must be a better-than-reasonable chance that the RBNZ will want to forecast a new, higher peak of maybe 5.75% or even 6%.
In just the past week of course the Westpac NZ economists forecast a peak of 6%, very much breaking away from the previously existing general consensus among major bank economists that the peak would be 5.5%. Subsequently economists at the country's largest bank, ANZ, have forecast a peak of 5.75% by July, as have economists at global economic researcher Capital Economics.
Significantly, wholesale interest rates at time of writing were now 'pricing in' a peak OCR of over 5.75%. This would please the RBNZ. Falling wholesale interest rates (and the downward pressure this was starting to put on retail rates - IE mortgages) were the prime catalyst for the shock 50 bps rise the RBNZ implemented at its last OCR review in April.
Would a higher forecast peak from the RBNZ now be warranted, or at least justifiable?
Well, for a start it is worth remembering that a forecast is just a forecast. If the RBNZ forecasts a peak OCR of 6% this does not mean the central bank HAS to raise the OCR that high. We've seen before that whatever the RBNZ projects in terms of future OCR levels has a marked influence on how the wholesale markets and subsequently the banks price interest rates. The projection is just about as effective as the actual 'real' hiking of the OCR.
What economists are now starting to suggest is that the RBNZ will keep on hiking at the next two or three reviews (in 25 bps moves).
This does, however, leave the same 'problem' for the RBNZ come, say July, (less than two months away) that it has hit a perceived peak level of the OCR and the 'markets' are eyeing future rate cuts.
One thing I think the RBNZ could and perhaps should consider (and again this assumes that the OCR does move up to 5.5% on Wednesday) is forecasting a 'pause' in rate rises for the next few months but then forecasting the OCR moving up in say the final quarter of this year. Such a strategy would give the RBNZ the chance to take a breath and assess the impact of all its hikes to date, but would also keep the pressure on the markets in terms of expectation of further future rate rises.
That latter point could be vital, because as mentioned further up the article, even if RBNZ took the OCR to 5.5% and forecast that the rate would stay there for the next year the 'markets' would be immediately looking for reasons to start dropping rates. But the explicit suggestion by the RBNZ that, okay, it's pausing now, but it's going to raise rates again, would give second and third thoughts. And crucially from the RBNZ's perspective it will likely keep mortgage rates roughly where they are now - which is what it wants.
So, back to that question of whether a higher forecast peak is warranted, or at least justifiable, it's worth having a look at how actual economic events have unfolded this year when compared with some of those RBNZ forecasts made in February.
December quarter GDP shrank by 0.6%, when the RBNZ had picked it to grow 0.7%. March 2023 figures have yet to be released.
The Consumers Price Index (CPI) showed annual inflation of 6.7% as of the March quarter, which was considerably better than the RBNZ's expectation of 7.3%. But nothing is simple. The RBNZ had expected domestically generated inflation to be 7.1% and the actual figure was a reasonably adjacent 6.8%. And its the domestic inflation that the RBNZ can do something about and therefore worries the most about.
Unemployment for the March quarter came in at just 3.4% versus the RBNZ's pick of 3.5%, while private sector average ordinary time wages increased at an annual rate of 8.2% against an RBNZ pick of 7.6%.
So, a mixed bag there. The labour market was still hotter than the RBNZ wants and was picking, GDP much weaker than expected, and inflation not as strong as expected.
I would say there's still enough justification from those three key data sets (and particularly from the labour market data) for the RBNZ to go ahead with an OCR increase next week.
But beyond these, I guess you would say, 'big three' data sets, it is arguably some of the more 'minor' real time economic data we have seen recently that may well be causing the most consternation within the RBNZ.
We are still spending money, in greater volumes than would please the RBNZ although crazy food prices are playing a part there, because it's costing 12.5% more to fill the grocery basket this year. Such an obvious inflationary impact on households could help to fuel the dreaded 'inflationary expectations' - these self-fulfilling thoughts that lead to future inflation. However, one note of encouragement for the RBNZ will have come from its recent Survey of Expectations, which showed a marked drop in the expectations of future levels of inflation.
But if that's a positive for the RBNZ, well then there's the surging inbound migration...
The RBNZ has already made reference to the latter as a potential inflationary factor. And it's the migration situation that tipped the Westpac economists over to expecting a 6% OCR.
Anything the RBNZ says on Wednesday about migration (and it is sure to) will therefore be of the utmost interest, particularly as to how inflationary the RBNZ may judge the impact to be. Migration is complicated. On the one hand the influx of workers will take heat out of the labour market - which is good for the RBNZ. On the other hand all these extra people will increase demand in the economy, which could be inflationary. Bad for the RBNZ.
The migration concerns will come on top of concerns the RBNZ has previously expressed about how inflationary the aftermath of the Auckland Anniversary Weekend floods and Cyclone Gabrielle could be. And the RBNZ will be quickly trying to digest the impact of Thursday's Government Budget announcement and how potentially inflationary some of the rebuilding initiatives and other stimulus measures might be. Early indications are that the RBNZ was right to be concerned.
Obviously it will be interesting to see if the RBNZ has a view on whether the Budget might require it to do more work (IE interest rates higher than they would have been), although it is likely to be reasonably discreet about what it says. The media are already keen to play up a Government-versus-RBNZ conflict. But clearly the Budget looks to have added potentially more upward pressure on inflation - and by implication the OCR.
Taking all these various factors together, it is to be imagined that RBNZ Governor Adrian Orr will again be sporting his 'hawk' outfit on Wednesday and it may yet be some time before we catch a glimpse of 'the dove' again.
Will there be room for surprises in Wednesday's announcement? A 50 bps rise, for example? Well, it seems that under this Governor the RBNZ always has room for surprises.
That's why we will all be well advised to have that nice big bucket of popcorn by our sides on Wednesday.
Expect anything.
*This article was first published in our email for paying subscribers early on Friday morning. See here for more details and how to subscribe.

We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.