
The Reserve Bank (RBNZ) is seeking public feedback on a central bank digital currency (CBDC) to be used by the general public, which they wouldn’t need a commercial bank account for, and it says could lead to banks and other deposit takers losing profits and liquidity.
In a new consultation paper, Digital cash in New Zealand, the RBNZ notes it has still not yet decided whether to issue a CBDC, which it's referring to as "digital cash."
It says digital cash would be a new form of cash issued by the RBNZ to the public in addition to banknotes and coins, and the electronic money in people's bank accounts. It'd be; denominated in NZ dollars, it could be swapped 1:1 with physical cash, and other forms of NZ dollars, like money in your bank account. It'd also be private, secure, and able to be trusted, the RBNZ adds, noting "the Reserve Bank will not control how you spend your money." It'd also be "available to everyone and distributed by the private sector – but you would not need a bank account to use it."
The RBNZ is focusing on money it would offer to the public and business, not to wholesale markets. However, digital cash would be designed as a general-purpose CBDC and would be available for wholesale use, it says. Accounts would be held with intermediaries and service providers, not the RBNZ itself.
The level of digital cash issued would be driven by user demand, the RBNZ says. Demand could stem from deposits, physical cash or income growth. The RBNZ says it hasn't forecast how much digital cash people may want.
"But we can expect that if people want to use a lot of digital cash, then banks and other deposit takers will lose deposits. This could cause them to lose profits and liquidity," the RBNZ says.
"We also need to consider the impact of issuing digital cash on wholesale funding [interest] rates [for financial institutions]. This is an important determinant for how banks would respond to fewer deposits. We will also consider whether we need to limit the amount of digital cash that people or businesses can hold. As well as what interest rate would be paid if any. We also need to test if there are any financial system stability impacts from issuing digital cash, including whether there are any transitional impacts on stability," says the RBNZ.
Preliminary scenarios of digital cash supply
It has developed preliminary scenarios of digital cash supply level, but says these scenarios aren't what it expects would happen because it has no evidence suggesting demand for digital cash would reach high levels.
However, two scenarios are modelled in the consultation paper. The first, the "high" scenario, sees $10 billion of digital cash issued. That's equal to the level of cash in circulation at the end of 2022.
"We swap cash and reserve balances to issue the digital cash. We assume digital cash doesn't earn interest and people can only hold $2000 each."
In this the scenario the RBNZ says its balance sheet stays the same size and there's minimal impact on commercial banks' deposit funding and profits.
Its "extreme" scenario sees $42 billion of digital cash issued. That's equivalent to 20% of retail deposits at the end of 2022.
"We swap cash and reserve balances to issue the digital cash. We also need to use foreign exchange operations to increase reserve balances to issue the full amount of digital cash. We assume digital cash earns a competitive interest rate [paid by the RBNZ similar to retail deposit interest rates]. We also assume that people can hold more than $2000 each by balances over $2000 do not earn any interest," the RBNZ says.
Under this scenario, commercial banks would face reduced deposit funding and profits, it says, which they could choose to respond to by getting more funding from investors, reducing lending or increasing lending rates. The RBNZ's balance sheet would become longer, as it's issuing more liabilities than before.
Innovation & competition
Ian Woolford, the RBNZ's Director of Money and Cash, says digital cash would ensure central bank money is available to all New Zealanders and able to be used digitally.
"It would also help enable a money and payments system that is innovative, competitive and contributes to the development of New Zealand’s digital economy. It would be the first digital form of New Zealand currency backed by the Government and available to the public. Physical cash in banknotes and coins would still be available, so people would have the option to use either digital or physical cash," he says.
"You would likely need a digital wallet, payment card or phone app to access your digital cash. You wouldn’t need a commercial bank account to use it."
"Innovations in money and payments are challenging New Zealand’s monetary sovereignty. Like crypto-assets, distributed ledgers, smart contracts, and digital currencies issued by global technology companies. New Zealand’s money must innovate to stay relevant and useful and ensure our monetary sovereignty," Woolford says.
"There is also a huge opportunity for digital cash to support competition and innovation by enabling our powerful fintech sector. Digital cash would be mainly used for payments by individuals and businesses, to pay online, instore, or even to pay your child’s pocket money in the same way you can use cash currently."
"You could use it to do new things like make an instant digital payment to anyone in New Zealand. Today, New Zealanders still cannot make instant payments electronically to other people, unless they are both with the same bank," says Woolford.
“It would also work via Bluetooth, so you could make payments without connecting to internet. This would be useful in an emergency, or when the power is out."
Many central banks overseas are also considering the introduction of a CBDC, whilst some are testing various concepts for one, and a handful have already introduced a CBDC. See more on this here.
The RBNZ previously consulted on the idea of a CBDC in 2021 as part of its Future of Money work. And in 2022 Woolford spoke on our Of Interest podcast, acknowledging the RBNZ considering launching a CBDC is in part a defensive move to protect the RBNZ's and NZ's monetary sovereignty.
Under threat
The RBNZ says the uniformity of NZ's money is being challenged by the decreasing use and availability of cash, and the emergence of new types of assets detailed by Woolford above. Additionally, CBDCs being considered by other countries could become a threat.
"If other currencies become more popular than the NZ dollar in New Zealand, then we could lose our monetary sovereignty," the RBNZ says.
"If a lot of people use them, it can pose a risk to our economy, the New Zealand dollar, and our monetary sovereignty. Monetary sovereignty is important because it means that New Zealand can independently manage its money, set interest rates, and make decisions without being overly influenced by external forces."
"We also have an opportunity to innovative central bank money. As well as to improve future efficiency and drive innovation in New Zealand’s money and payments. New Zealand’s payments landscape is dominated by a small number of large players. The barriers to entry are high and New Zealand’s payment services have become less innovative than other countries. Digital cash would help bring down barriers to entry to the payments system. Digital cash would also be a new piece of digital public infrastructure that supports digital transformation in New Zealand," the RBNZ says.
The RBNZ says digital cash wouldn't see it provide digital cash services directly to users. Rather, there'd be digital cash service providers offering digital cash services, with the public able to choose which provider to use.
"You could also change providers or use several providers depending on the services you want. These may include banks, payments companies and new providers," the RBNZ says.
"There would be a range of devices that people can use to access and make digital cash payments. The Reserve Bank would own and operate a digital cash payments platform. This platform would facilitate all digital cash payments."
"Digital cash service providers would not be able to touch your digital cash. That means, even if a service provider failed, you would not lose your digital cash," says the RBNZ.
Digital cash payments would be available 24/7, and would be sent and received instantly. People could use digital cash to make payments without internet access by downloading their funds to a local device and use Bluetooth technology to make a transfer to another device.
"There is also the possibility that digital cash can support wholesale uses such as cross-border payments."
The RBNZ says digital cash would be private and secure, with people free to use and spend it as they want to.
"The Reserve Bank would not be able to, nor want to, place any limitations on how the digital cash can be used. The Reserve Bank will set rules on how third parties can collect, use, share and delete your information."
When might a CBDC actually be introduced?
The RBNZ argues digital money could provide new entry points to NZ’s payment landscape for new service providers by providing an open, interoperable, and safe payments platform that can be accessed by banks and other third parties to provide a wide range of digital cash services. Additionally it could improve digital financial inclusion by offering more consumer choice such as basic money and payment services and offline payments.
"We are considering a delivery approach that allows the market to deliver many different services, in the digital cash ecosystem. The Reserve Bank would provide a digital cash platform that has built-in functionality to encourage a diverse and rich ecosystem. The Reserve Bank would also set the guard rails for how the market can operate in the digital cash ecosystem. This approach prioritises open competition and a dynamic market, while ensuring the remaining digital cash principles are achieved," the RBNZ says.
"We want your feedback on our judgments and design options for digital cash. This will inform our future work on whether digital cash is right for New Zealand. Digital cash will not replace physical cash," the RBNZ says.
It's seeking submissions by July 26, and says it's undertaking "multi-stage exploration" of a CBDC until about 2030.
An RBNZ spokeswoman told interest.co.nz a decision to actually issue a CBDC would be made following discussion with and agreement from the Government. The RBNZ expects to make recommendations in 2026 on whether to proceed to the next stage, and would then develop prototypes to test how a CBDC could work in the real world, during 2028 and 2029. A CBDC could then be introduced around 2030.
"We are now sharing our latest thinking on what digital cash could look like in New Zealand. We describe what we mean by digital cash and how New Zealanders could use it. We also describe why the Reserve Bank is investigating it, and what it would bring to New Zealand. We want your feedback on our judgments and design options for digital cash. This will inform our future work on whether digital cash is right for New Zealand," the RBNZ says.
Figure 3 from the RBNZ's consultation paper, below, summarises its public policy objectives for a CBDC.
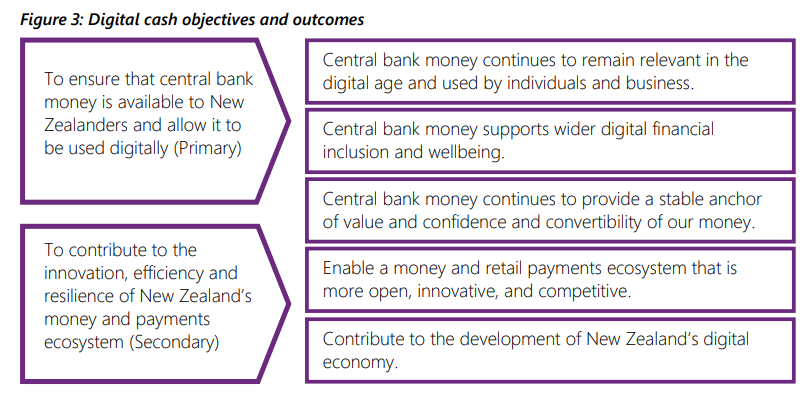
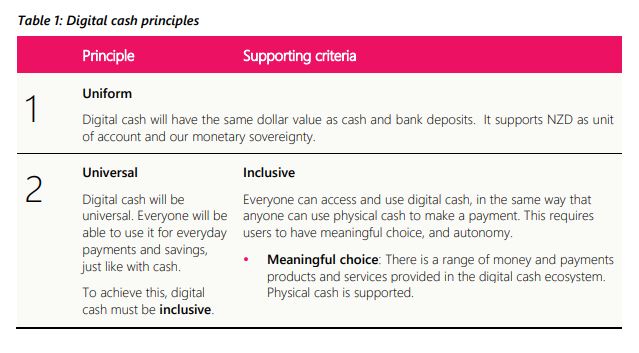
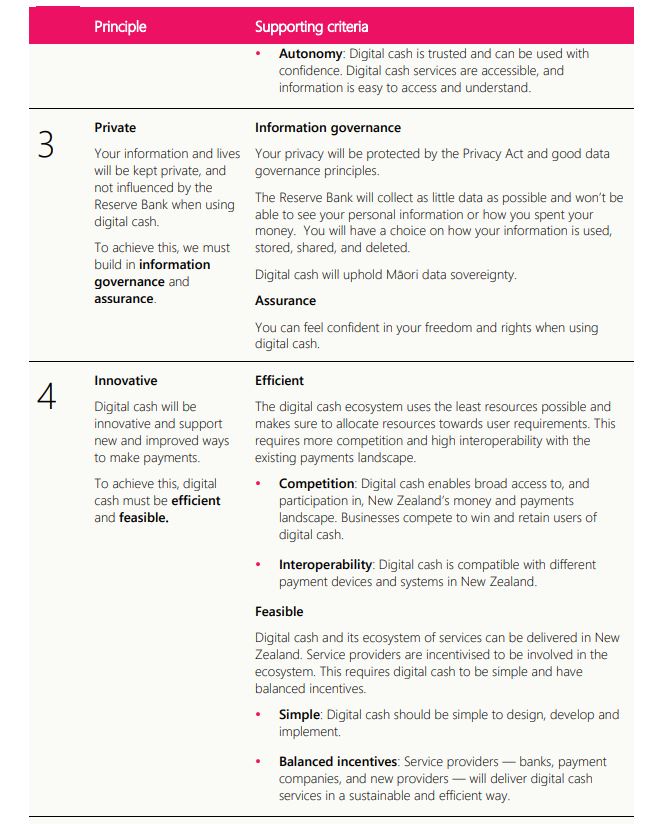
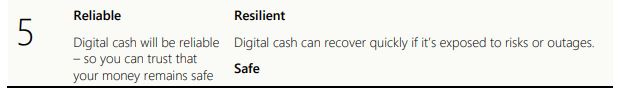
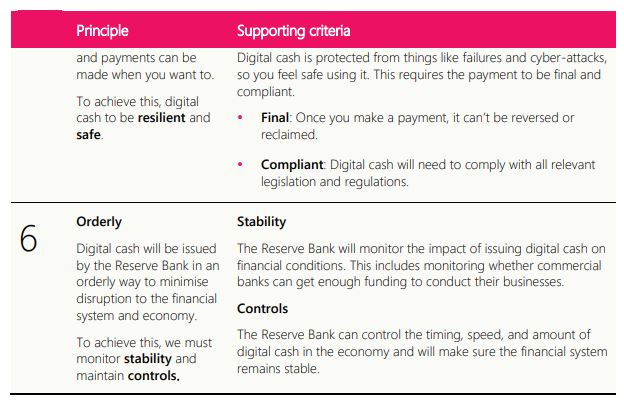
Table 1, below, sets out the outcomes a CBDC needs to meet to achieve the RBNZ's public policy objectives.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.