
The country's banks are expecting that demand for new residential mortgages will stabilise over the next six months "with buyer confidence returning".
And the banks feel that if interest deductibility on rental properties is reintroduced there will be "a more significant increase in investor demand".
In the Reserve Bank's latest six-monthly credit conditions survey, 15 banks, including the big five, have outlined their latest thoughts on credit trends in the immediate past and the near future. The Survey period covers credit conditions observed between the start of April 2023 and the end of September 2023 and asks how banks expect them to evolve over the next six months.
The expectation that demand for new residential mortgages will stabilise over the next six months stems from the fact that house prices are starting to show signs of recovery and interest rates are at "or near" their peak.
Mortgage demand has been very low this year, but has shown some signs of beginning to perk up a little in recent months. RBNZ figures for August, the latest available, showed that in that month the amount of money advanced rose by over 8% on a seasonally-adjusted basis. The $5.782 billion worth of mortgages committed to in August 2023 was up from $4.997 billion in July 2023 and up up 6.8% on the $5.413 billion of mortgages committed to in August 2023.
In the previous credit conditions survey released in April of this year the banks had said they expected mortgage demand would remain "subdued". And this has proven to be the case over the past six months.
"Demand for residential mortgage lending decreased in the last six months, continuing the trend seen since mid-2021," the RBNZ said.
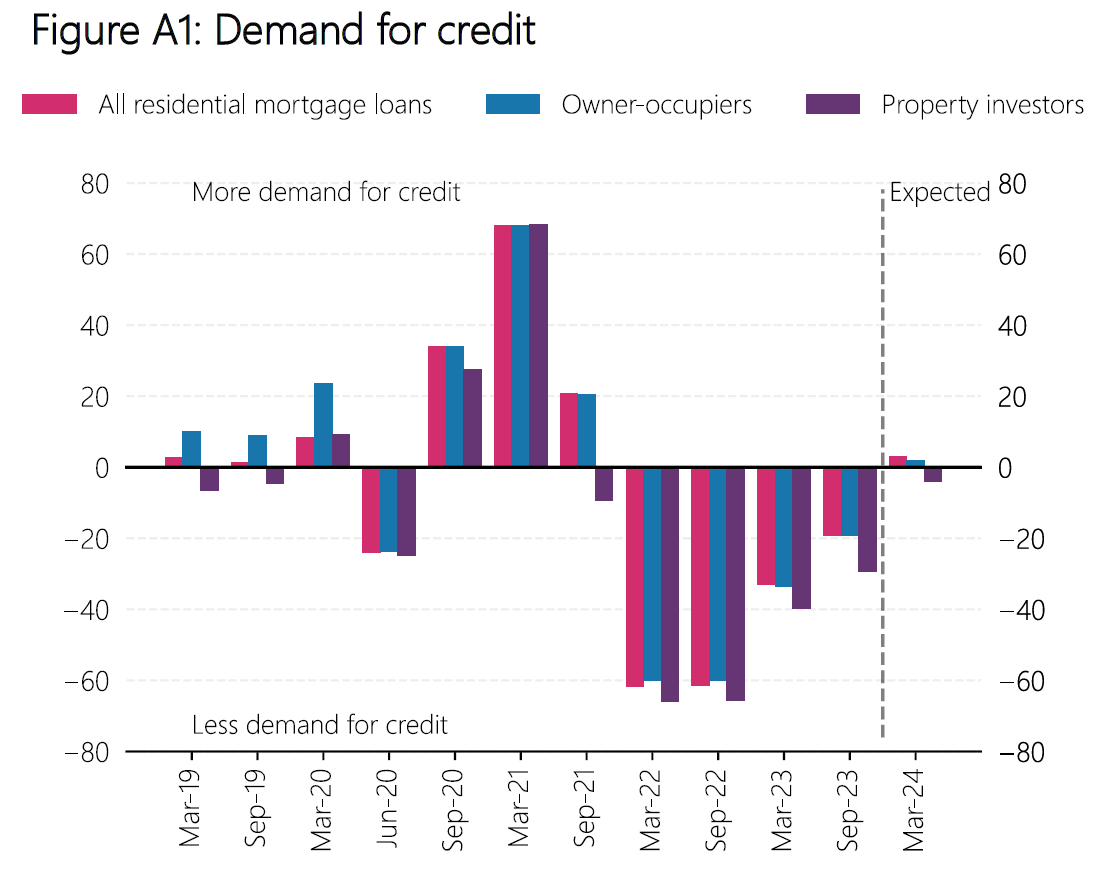
"Both owner-occupier and investor activity has remained subdued in the higher interest rate environment, with low consumer confidence and an uncertain trajectory for house prices also having an impact.
"Some potential buyers are opting to delay investment until there is greater certainty over future government policy," the RBNZ said.
"Banks also noted the impact of the increase in households’ living expenses on the ability of borrowers to pass affordability tests, particularly with some banks’ test rates continuing to increase."
The banks reported that there was an increase in the availability of residential mortgage credit over the past six months, "following materially tighter conditions over 2022".
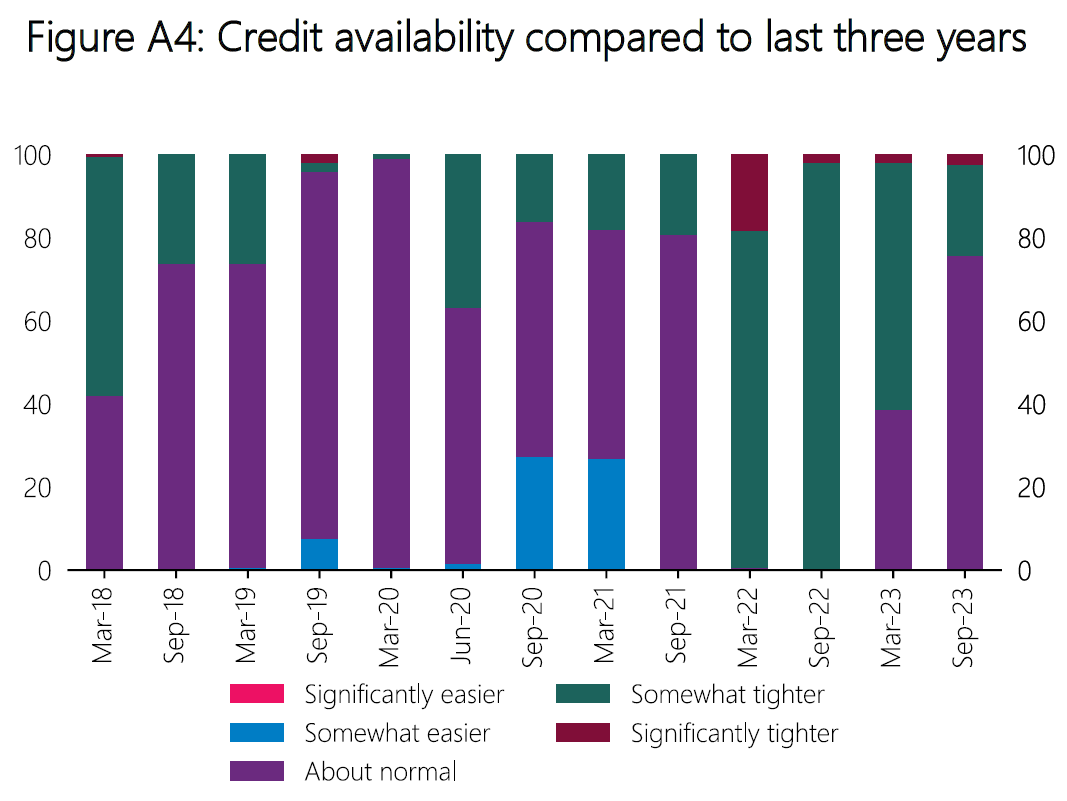
"While some banks have increased mortgage serviceability test rates slightly further, the effect on credit availability has been offset by an amendment to the Credit Contracts and Consumer Finance Act in May, which eased requirements for measuring borrowers’ discretionary spending, and the easing in the Reserve Bank’s LVR [loan to value ratio] restrictions in June," the RBNZ said.
However, availability of consumer credit tightened slightly over the past six months, "as some banks adjusted pricing following changes in risk appetites".
The banks reported increased demand for consumer credit over the survey period. This was driven by demand for secured personal lending, as demand for unsecured personal lending and credit cards contracted.
"A key driver of this trend has been inflation in household expenses which have necessitated some households to make greater use of credit facilities. However, some banks noted that tightening in their unsecured lending terms had reduced the number of applications, making it more difficult to assess underlying changes in demand."
Most banks do not expect significant change to household credit availability over the next six months, however, it was noted that Debt-to-Income restrictions may have some impact if introduced in 2024.
The RBNZ has long sought to have the option of DTIs.
Having finally received government approval in 2021 the RBNZ then began preparatory work and earlier this year released a debt servicing framework, which will enable restrictions to be possibly brought in by March 2024 if needed - with the banks therefore getting 12 months to get their systems ready, should they be required.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.