
The lowest unemployment rate in decades is a bigger headache for Reserve Bank (RBNZ) monetary policy than the highest inflation in 30 years, BNZ Head of Research Stephen Toplis argues.
In his preview of next Wednesday's Reserve Bank Monetary Policy Statement, Toplis says the RBNZ needs the unemployment rate to rise, effectively meaning it needs people to lose their jobs, if it's to meet its monetary policy targets.
Toplis lays out just how blunt a tool the central bank wields.
"The Reserve Bank’s task is clear. At its most basic level it has to get current annual inflation of around 7.0% down to 2.0% and it will require the unemployment rate, now 3.2%, to rise to around 4.5% to meet its maximum sustainable employment objective."
"The only way the RBNZ can achieve this is to keep raising interest rates until it gets the traction it desires. And so it will," says Toplis.
The RBNZ's Policy Targets Agreement with the Government requires it to target maximum sustainable employment alongside price stability when setting monetary policy. However, just what maximum sustainable employment is is somewhat vague. It is not a specific unemployment percentage.
In its last Monetary Policy Statement the RBNZ said employment was assumed to be above its maximum sustainable level, as reflected in a wide range of indicators detailed in the RBNZ's maximum sustainable employment indicator suite below.
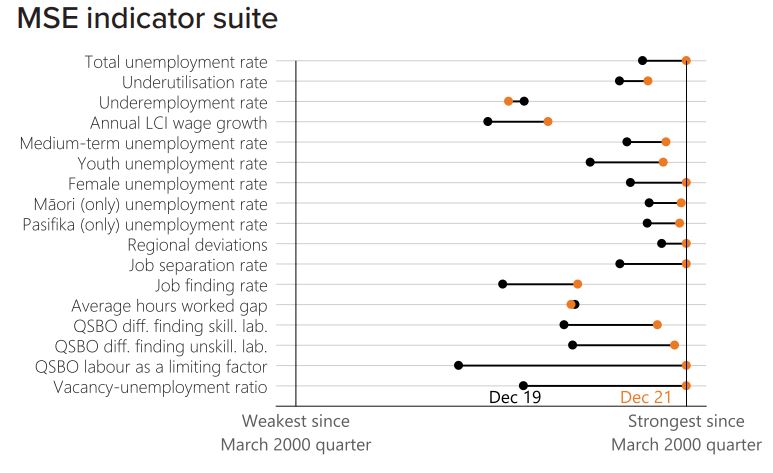
According to Statistics NZ, unemployment was running at 3.2% in the March quarter. That was unchanged from the December quarter and is the lowest rate recorded since the Household Labour Force Survey began in 1986. The Statistics NZ data shows 94,000 people were unemployed as of March. Annual wage inflation was running at 3%.
In terms of inflation targeting, the RBNZ must keep future annual inflation between 1% and 3% over the medium term, with a focus on keeping future inflation near the 2% midpoint. As of March the annual consumers price inflation (CPI) rate was 6.9%, according to Statistics NZ. That's the highest it has been since 1990.
Commodity prices hold the key to inflation
As big as it may be Toplis reckons the inflation task, at least initially, might be the easier one for the RBNZ.
"So much of current inflation can be attributed to rising global commodity prices, particularly oil. All it would take is for commodity prices to stabilise at current levels and the lack of commodity price inflation would have a marked downward impact on the local CPI inflation track. A modest correction could have headline inflation plummeting via its tradeables component. Stabilisation in commodity prices is a major part of our expectation that headline inflation returns to target in 2024," says Toplis.
"The bigger problem for the central bank is the state of the labour market. It is stretched to breaking and, consequently, wages are headed higher. Ongoing wage growth, coupled with rising inflation expectations risks making above-target inflation more permanent. On this basis, the RBNZ needs to see a marked softening in the labour market not only to meet its maximum sustainable employment objective but also to help ensure expected declines in inflation become more permanent."
"The frustration for the [Reserve] Bank is that labour market issues are currently more driven by supply than demand. Opening the borders and easing visa criteria are designed to help offset supply problems but we fear any respite will be limited. To start with, there will be a long lag between policy change and actual people flows, as folk go through the bureaucracy and then prepare for the big move. At the same time as the inflows improve, we expect the outflows to accelerate," Toplis says.
"There is already clear evidence of this, particularly amongst the key 20 to 35 year age group. If the supply response is as limited as we assume, then the only way the excess demand for labour can be moderated is if economic conditions reduce the need for staff. And bear in mind that the initial requisite reduction in growth will merely reduce the excess demand. It may take a substantial slowing in growth, or a recession, to generate the shift in the unemployment rate that will be needed to equilibrate the labour market in the eyes of the Reserve Bank."
"To put this in perspective, we think we would need around 18 months of zero employment growth to get the unemployment rate to rise to the RBNZ’s NAIRU estimate. All this being so, the Reserve Bank will have little option but to hike the cash rate a further 50 basis points when it delivers its Monetary Policy Statement next Wednesday."
NAIRU, or the non-accelerating inflation rate of unemployment, is a theoretical level of unemployment below which inflation would be expected to rise.
The key questions
Ahead of the May 25 Monetary Policy Statement Toplis says the big questions are:
· What will be the peak in the cash rate?
· How fast will the RBNZ want to get there? And;
· Will the RBNZ be willing to show a reduction in the cash rate toward the tail end of its forecast track?
"In the February Monetary Policy Statement, the RBNZ published a peak in the cash rate of 3.35%. We don’t see the need for this to change much. It is a model driven variable so some variation may occur. And we wouldn’t be surprised if it was nudged a little higher, say to 3.50%, but we doubt the RBNZ would push it so high as to match recent-past market pricing of a terminal rate of around 4.25%," says Toplis.
"Since the beginning of May, market pricing has moved closer to 3.75%. We don’t believe the Reserve Bank would want this pushing any higher at this juncture. At its April review, the RBNZ said that its 50-point hike was consistent with the interest rate track published in February. A further 50-point hike, which is what we expect, would not be consistent with that track."
"Consequently, the very fact the RBNZ will have moved rates 100 basis points over two meetings indicates a more hawkish stance. Moreover, we expect the Bank to produce a track which, effectively, brings forward the remainder of the tightening cycle from that which it published in February. Indicative of this, we think the Bank will have the cash rate at 3.0% by November of this year. Previously it took until mid-2023 to get to this point. If it does raise interest rates in this manner, the pace of increase will have been the most aggressive witnessed since the Bank began inflation targeting," says Toplis.
"Where the neutral [OCR] rate is perceived to be is a key factor in determining the future level and pace of increase in the cash rate. At the time of the February Statement the neutral cash rate was deemed to be 1.86%, or 'around 2.0%,' in the Bank’s words. It is plausible the RBNZ could shift this. But it could move it in either direction and history has shown us any shift is unlikely to be sizable."
The neutral OCR rate is the level where it's deemed to be neither stimulating nor constraining economic activity.
"The strength in core inflation that has been witnessed might indicate the neutral rate should be estimated as higher. In contrast, the extent by which current mortgage rates have risen already, the effective tightening in monetary conditions from tighter lending criteria, the observed impact these changes are already having on the housing market, lower population growth and heightened risk aversion (i.e. lower investment activity) might suggest a nudge in the other direction," Toplis says.
"Whatever the case, we doubt any such revision would see the neutral rate deviate substantially from 2.0%. This being so, a 50-point hike next week means the cash rate will be perceived as having returned to neutral. The RBNZ will, again, be leading the global central bank pack. It will be the first to contemplate what should be done with contractionary monetary conditions."
"As far as we are concerned, the response should become more cautionary once this stage has been reached. Given that the New Zealand economy is walking a tightrope at the moment, the RBNZ will not want to be the reason it falls off. The RBNZ said that its April 50 point hike was a stitch in time. That stitch will have been well and truly sewn when the cash rate hits 2.0%, so we see the RBNZ deferring to regular 25 point increases thereafter," says Toplis.
"Of course, they won’t rule out a further 50 point move at some point in the future. In particular, July will be seen as live. But it will be back to data watching in the interim, and in the period between now and the July meeting there is a very strong chance that: the global outlook will deteriorate further, in part as central banks elsewhere move their respective settings towards neutral; the decline in New Zealand house prices accelerates; and leading indicators remain in recessionary territory. This being the case caution should reign. When the Reserve Bank publishes its May missive, it will extend its forecast OCR track by an extra quarter, to June 2025. It is almost certain the peak in the cash rate will come a year, or more, earlier than published in February."
"This being so, there will be an opportunity for the Reserve Bank to publish a track which has the peak maintained for around 12 months followed by a quarter or two of rate cuts in 2025."
"We will be watching the tail end of the track closely. After all, the RBNZ will, at some stage, indicate that its actions have won the battle and that rates will need to start returning to neutral from the topside rather than the bottom. The Bank’s modelling will, by definition, drive such an outcome. Were the Bank to publish a small retreat in rates in 2025 it might be a good way to (a) reduce the chances that the market pushes its estimated terminal rate higher and (b) indicate that the RBNZ believes it has matters under control," Toplis says.
More overseas workers expected
In its February Monetary Policy Statement, the last one it issued, the RBNZ said it assumed labour market tightness would peak in the first half of 2022.
"High frequency jobs data suggest that employment growth is starting to slow and higher interest rates are expected to reduce demand over the medium term. More international workers are expected to arrive during 2022 as border restrictions are gradually eased. Net inward migration is expected to increase gradually towards its 20-year average over coming years, depending on decisions related to any changes to immigration policy currently being reviewed," the RBNZ said in February.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.