
The economy shrank by -3.7% in the September quarter as particularly Auckland languished under the impact of a Covid Delta lockdown, according to figures out on Thursday from Statistics New Zealand.
But while that's the second largest drop ever in a quarter (after the lockdown-impacted -10.3% June 2020 quarter), the figure is actually very much in line with recent forecasts from economists.
The performance of the economy in the latest quarter was adversely affected of course by the Auckland lockdown that extended through the latter half of the period. But the results still showed a degree of resilience and demonstrated that businesses have become more adept at handling the major lockdown disruptions.
Economists had earlier been expecting a fall of -7% to -8% but had revised their picks upwards in recent days as it had become clear the outcome would be better than earlier anticipated. In its November Monetary Policy Statement the Reserve Bank had picked a -7% figure for the September quarter.
The latest GDP figures announced on Thursday follow on from a strong rise in the June quarter - although that figure has now been revised down by Stats NZ to +2.4% from the earlier announced +2.8%. There were a number of other revisions made to earlier GDP figures by Stats NZ as well.
ASB senior economist Jane Turner said that after incorporating the various revisions to past figures, the September quarter GDP was "just" 0.3% below the same quarter of the previous year – "a phenomenal result given the impact of the Alert Level 4 lockdown over the second half of Q3".
"The result reflects the underlying momentum heading into the lockdown and the resilience of the NZ economy," she said.
"Going forward, the key question is how quickly the economy bounces back to pre-Delta levels – we expect this to take place over the first half of 2022. A key determinant will be how household spending growth holds up over 2022 in the face of a number of headwinds including the higher cost of living, higher interest rates and some uncertainty as NZ adjusts to living with COVID-19. We expect the RBNZ will continue to lift the OCR [Official Cash Rate] over 2022, to a peak of 2%."
Stats NZ said some industries were more affected than others by the higher alert level restrictions during the September 2021 quarter.
- Service industries, which make up about two-thirds of the economy, fell 2.7%.
- Goods-producing industries, which make up about one-fifth of the economy, fell 7.3%.
- Primary industries, which make up the remainder of the economy, fell 3.1%.
Annually, GDP rose by 4.9% over the year to September 2021 when compared with the year to September 2020. Stats NZ said, however, that care must be taken when comparing annual measures as the year to September 2020 includes the first lockdown in the June 2020 quarter.
“The four industries with the largest falls in activity were retail, accommodation, and restaurants; manufacturing; construction; and arts and recreation as they were the most affected by lockdown measures. Face-to-face activities were unable to take place, physical workplaces were closed, and non-essential workers remained at home during alert levels 3 and 4,” Stats NZ's national accounts industry and production senior manager Ruvani Ratnayake said.
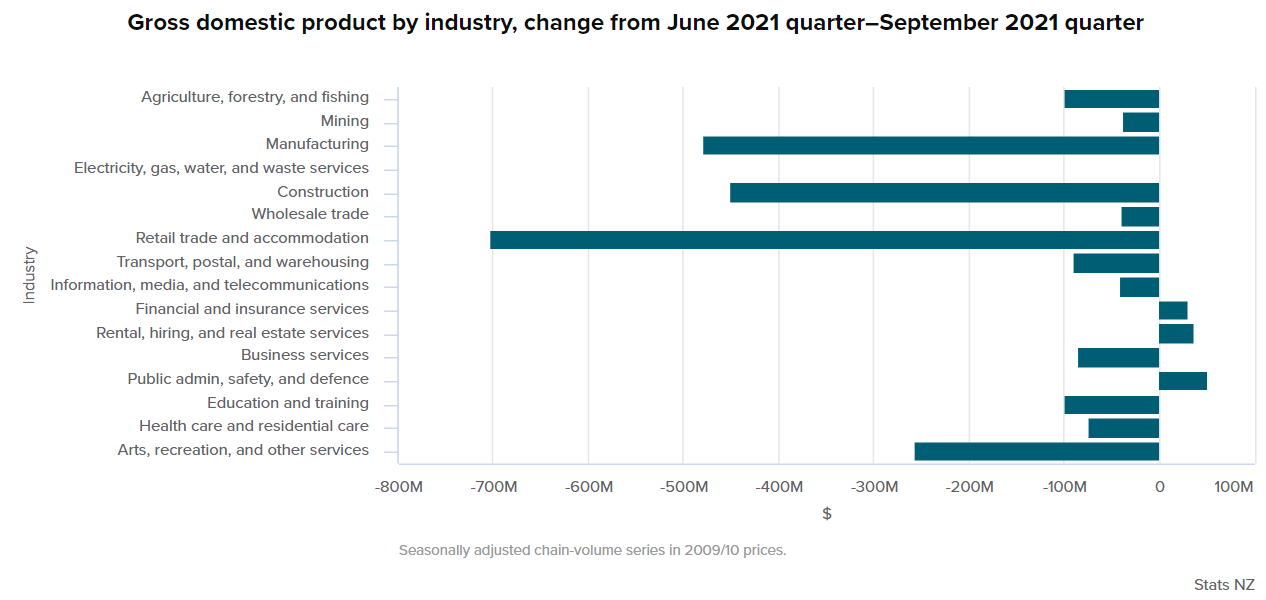
The falls in production were mirrored by corresponding falls in household consumption expenditure and investment expenditure, which fell by 7.5% and 5.3% respectively.
ANZ senior economist Miles Workman said the lesson learned over the past 18 months or so is that government support via the wage subsidy and other business support is an extremely effective, "albeit costly", way to limit the broader economic fallout.
"We’re hopeful that things will pick up largely where they left off ahead of lockdown, but we are cognisant of the fact that underlying economic conditions are very different to the last time we were asked to stay home and save lives. This time: The housing market isn’t poised to unleash a tsunami of equity upon those lucky enough to not be locked out of the market. In fact, house prices now appear poised to fall.
- Monetary conditions are tightening, not loosening.
- The labour market is tighter than a tight thing.
- We’re mostly vaccinated and are gearing up to live with traffic lights and endemic Covid.
- Capacity constraints are biting hard and inflation pressures are at multi-decade highs. That’s not optimal timing for additional fiscal stimulus, but Budget 2022 is set to deliver that anyway.
"One thing’s for sure, whatever comes next won’t be a rinse and repeat of the past year or so. Hopefully, the strong labour market and gradually reopening border puts the economy on a sustainable growth path, but forecast uncertainty remains very high," Workman said.
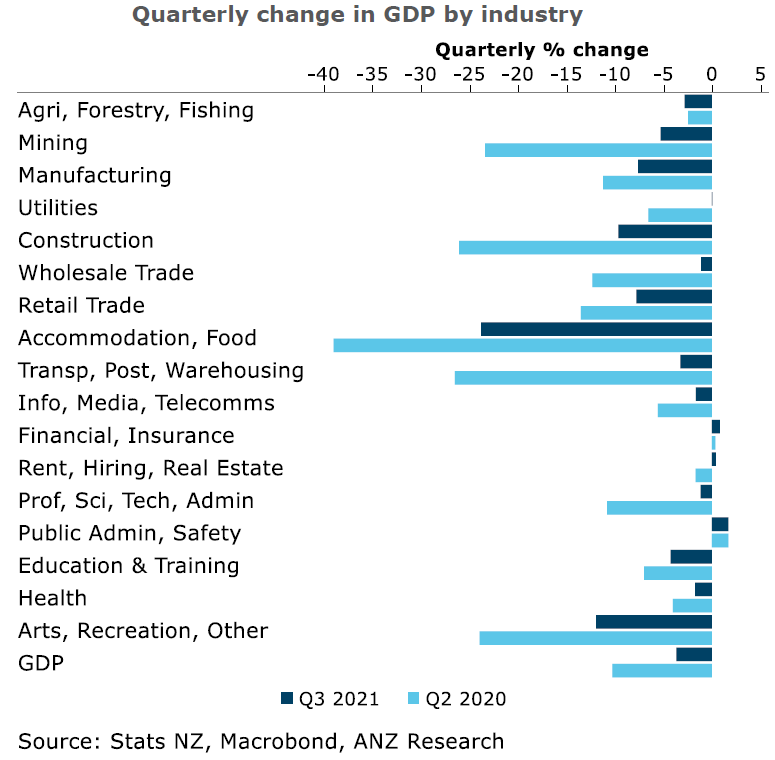
Below is a graph showing the percentage movements in GDP in all industries and comparing this with the lockdown affected June 2020 quarter.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.