Market movements have remained well contained, with US equities relatively flat and US Treasury yields showing only modest changes. The NZD has recovered slightly, pushing back above the 0.56 mark, and is modestly higher against most key crosses.
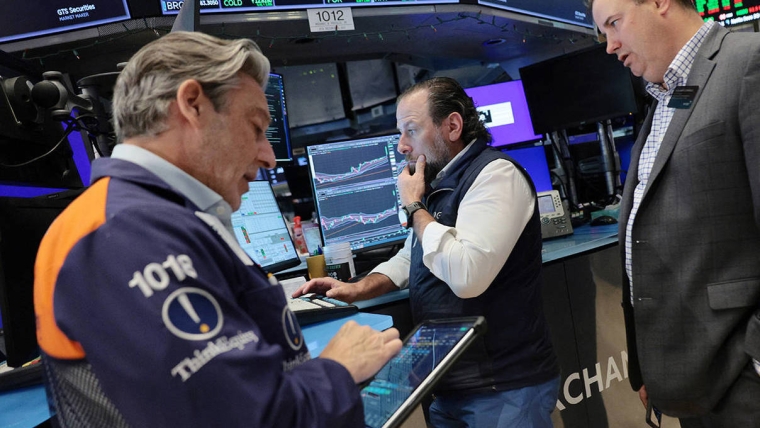
The US earnings season got off to a strong start, with JP Morgan, Goldman Sachs, Wells Fargo and Citi all reporting higher profits, supported by both trading and banking operations. Strong equity trading was a notable feature, while net interest margins expanded against the backdrop of higher interest rates. Share price reactions to the results were mixed, and US equities are trading relatively flat overall.
Oil prices remain elevated against the backdrop of Middle East hostilities. The Saudi-led coalition in Yemen warned that some sites should be evacuated ahead of a “special operation”, while Trump said in a social media post that “the Houthis are behaving very badly”. Bloomberg reported an increase in attacks on ships crossing the Strait of Hormuz and signs that the flow of cargoes may be slowing in response, according to contacts in the shipping industry. Brent crude is trading around USD106.
US Treasury yields continue to be closely correlated with gyrations in oil prices. The 10-year yield tracked lower alongside oil prices during the NZ trading session and fell to an overnight low of 5.17% before reversing course. It is currently at 5.22%, up 3bps from the NZ close, with the curve slightly flatter. In European bond markets, risk sentiment has improved somewhat, with French and peripheral 10-year spreads narrowing against Germany; the French spread has contracted by 5bps.
In economic news, the IMF released its latest World Economic Outlook report yesterday, leaving its forecast for world GDP growth in 2026 unchanged at 3.1%. Growth is expected to pick up to 3.4% in 2027, an upward revision of two-tenths. The inflation forecast was revised up by three-tenths to 4.7% for 2026 and by four-tenths to 4.1% for 2027. The IMF noted that the global economy is once again proving resilient, but unevenly so, with the stable global aggregate masking a reallocation of growth across economies.
In currency markets, the NZD lurched lower yesterday afternoon to a low of 0.5580, but that level once again proved supportive. It subsequently recovered to an overnight high just above 0.5615, close to where it currently sits. The repeated rejection of moves below 0.5580 since the start of the month has solidified that level as a marker of support, for now at least.
Other major currencies showed a similar pattern, reflecting broad-based USD weakness. The AUD has recovered to 0.6980, while the EUR briefly traded above 1.12 overnight. NZD crosses are mostly higher overnight, although the gains have been small.
Global forces supported a move lower in NZ rates yesterday, with NZGB yields marked down 2–4bps across the curve. The 10-year yield closed below 5% for the first time this month, at 4.98%. Swap rates were also marked down 2–4bps, with a flattening bias, leaving the 2-year rate at 3.99% and the 10-year rate at 4.68%.
In the day ahead, China’s inflation and trade data will be released. However, the highlight of the week is tonight’s US CPI report. The consensus expects the core rate to rise by 0.2% m/m, which would be moderate enough to keep the Fed on the sidelines at its late-October meeting. An upside surprise, however, could increase the pricing of a rate hike from the 6bps currently priced and support the USD.
Daily exchange rates
Select chart tabs
Jason Wong is the senior Markets Strategist at BNZ Markets.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.