
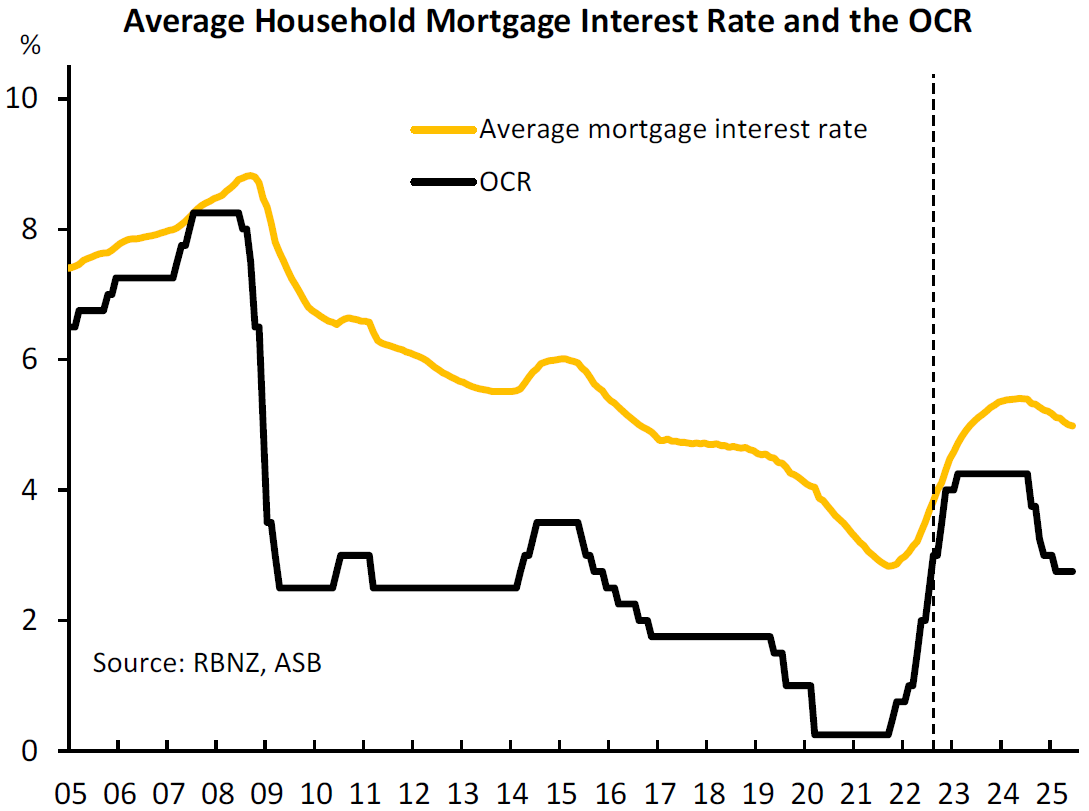
Average mortgage costs for Kiwis are likely to keep rising and approach 5.5% by the start of 2024, ASB economists say.
And they say that even if the Reserve Bank (RBNZ) cuts the Official Cash Rate in 2024, average borrowing costs are unlikely to move lower till 2025.
ASB senior economist Mark Smith has done a detailed crunch on household living costs, which follows on from one he did earlier in the year.
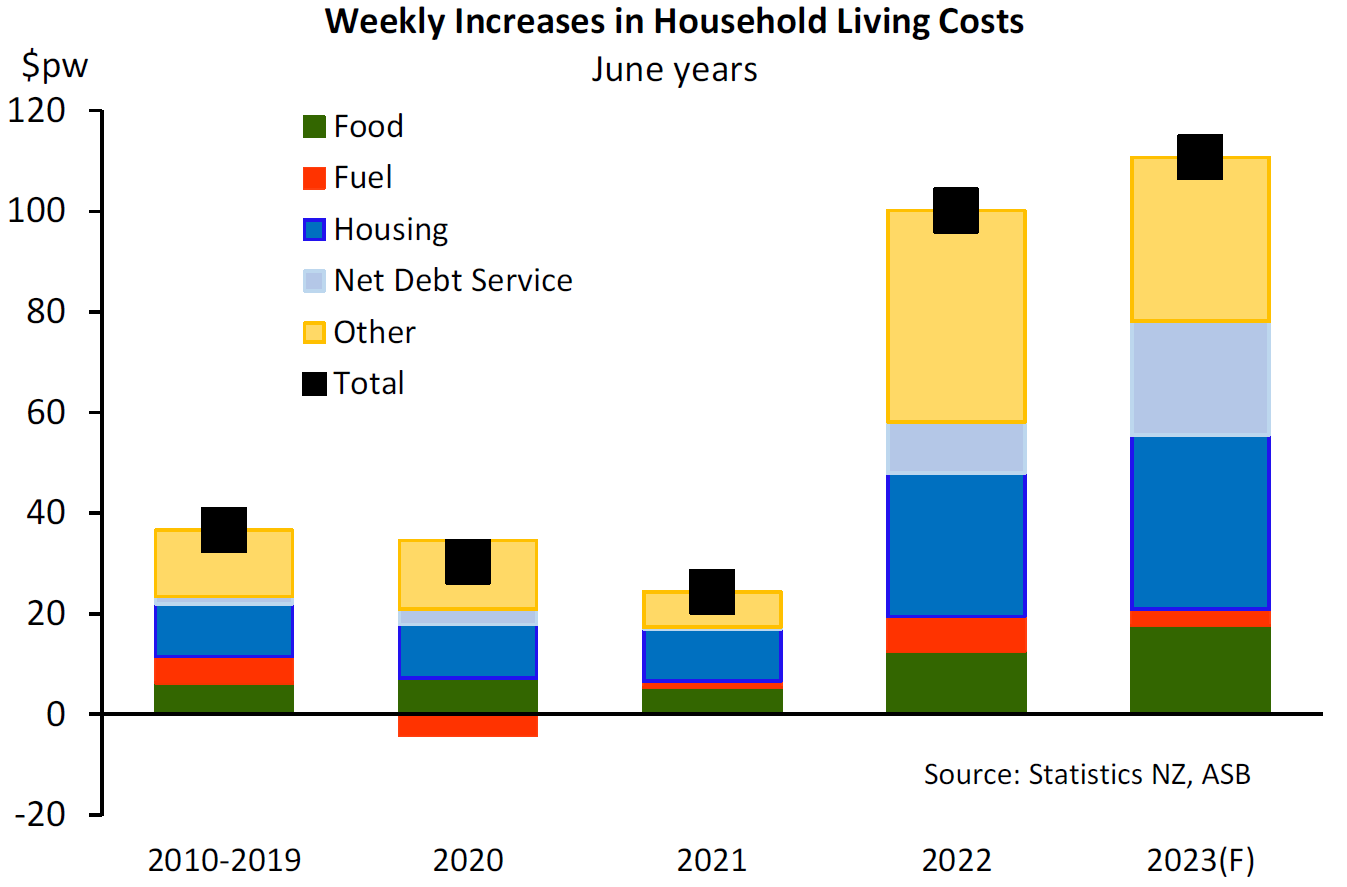
In the latest update Smith estimates households may face an approximate $110 weekly increase in living costs for the year to June 2023. However, he notes that household incomes are also rising strongly.
In terms of mortgages and debt servicing, Smith says these costs "have further to run".
The OCR is currently at 3.0%. The ASB has recently raised its forecast of the OCR peak from 4.0% to 4.25%.
"Current carded mortgage interest rates, particularly for shorter terms, look set to move up further," Smith says.
"Moreover, fixed mortgages are rolling on to much higher rates, which is pushing up average debt servicing costs, albeit gradually. All up, the average mortgage interest rate facing borrowers should climb slightly above 4.5% by the end of 2022, and approach 5.5% by the start of 2024.
"Even if the OCR is cut in 2024, average borrowing costs are unlikely to move lower until 2025."
Although the ASB economists expect annual CPI inflation to have peaked (at 7.3% as of June) they believe domestically-generated inflation will be slow to recede from its 6.3% record high.
"Assuming households maintain their current spending habits, more of the increases in living costs we expect are likely to be domestically-focused. Of the approximate $110 weekly increase in household living costs in the June 2023 year, around two-thirds of those would either be non-tradable goods/services or debt servicing," Smith says.
He notes that these figures are averages for the household sector.
"Households without much debt will be faring better, whereas highly-indebted households and those without a decent income buffer will find the going much tougher."
But he says while costs and prices have risen strongly, so have household incomes.
"In fact, we have been surprised with how quickly household income growth has responded. Having an exceptionally tight labour market has clearly helped with firms having to pay more to attract and retain staff. According to June 2022 income figures from the Household Labour Force Survey, average household incomes rose by close to 6% in the June 2022 year. Wage and salary earners did particularly well, registering an 8.7% increase in weekly gross income. The strength in the recent numbers has been corroborated from a number of other surveys."
Smith says that after netting off income taxes and Kiwisaver contributions (in total assumed to be slightly under 40% of the increase in household incomes), the figures suggest after-tax incomes rose by just over $100 per week per household in the June 2022 year, broadly on par with the rise in living costs.
"We expect household incomes to post more sizeable increases in the next couple of years, largely reflecting sizeable increases in wages and salaries and the expected rebound in other incomes. This should mean households in general should have sufficient funds to pay the bills and potentially increase consumer spending. However, the impacts will vary hugely depending on the individual circumstances of households."
The economists have calculated a household income gap that is the difference between weekly increases in after tax incomes and living costs.
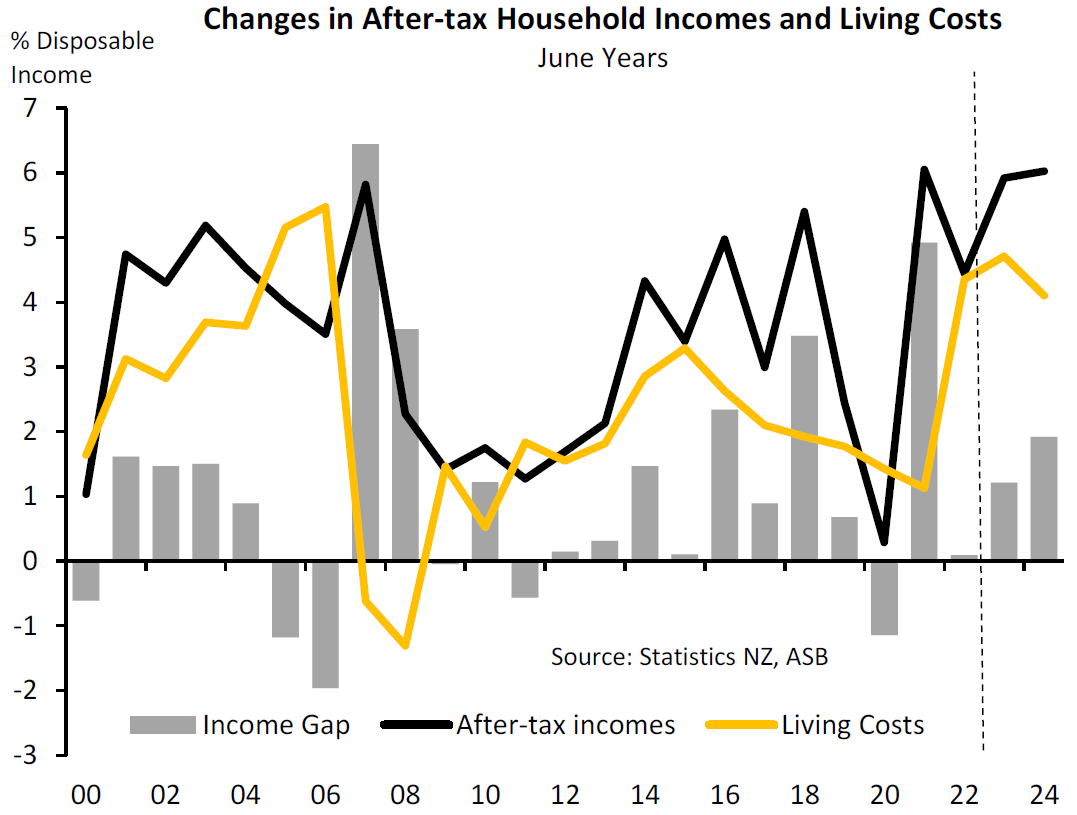
"Weekly increases in living costs in the June 2022 year were the highest for at least 20 years, but this has been more than offset by sizeable increase in after tax incomes," Smith says.
He says the ASB economists' analysis suggests that the outlook for household spending "is not as dire as it looked last year when we flagged upside risks to the inflation outlook".
"The economy could continue to surprise with its resilience, adding to capacity pressures. The wage inflation outlook is clearly stronger and in the absence of a labour productivity miracle there is limited scope for strong wage growth to be sustained without blowing an inflationary gasket. Risks of a prolonged period of high wage and core inflation remain.
"What are the implications for monetary policy settings? We expect a further 125bps of OCR hikes by early 2023 and a 4.25% OCR peak.
"The higher the OCR goes the larger the subsequent fall, and we feel that pressures on household budgets will be felt acutely by some households. Prolonged subpar rates of household spending could trigger OCR cuts, but not until the RBNZ is confident it is on top of inflation, which looks to be some way away in the context of anaemic labour supply and potential output growth.
"Conversely, persistently high rates of wage inflation that are not offset by rising productivity and/or a more resilient household sector outlook point to a longer period of restrictive monetary settings and potentially a higher OCR peak that what our (upwardly revised) forecasts suggest."
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.