sign up log in
Want to go ad-free? Find out how, here.

Rates markets were highly volatile. 10-year US Treasury yields hit a 24-year high before retracing sharply. Concerns over France’s fiscal outlook drove a broader sovereign bond sell-off. The US dollar strengthened

Currencies / analysis
Rates markets were highly volatile. 10-year US Treasury yields hit a 24-year high before retracing sharply. Concerns over France’s fiscal outlook drove a broader sovereign bond sell-off. The US dollar strengthened
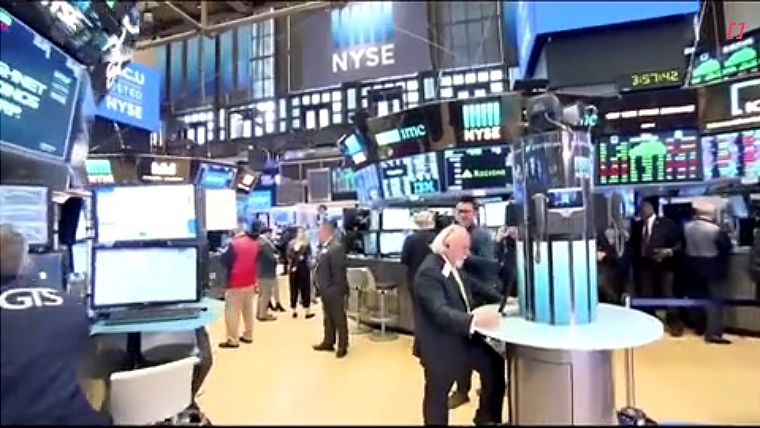
NYSE trading floor

Global bond markets remained volatile. The 10-year US Treasury yield reached a fresh 24-year high near 5.34% before retracing, while the most actively traded Brent crude contract gained almost 4% to above US$100 per barrel. Rates volatility and higher energy prices weighed on risk-sensitive assets. US equities are little changed but there were large falls across the major European indices with the Euro Stoxx closing 1.5% lower. The US dollar strengthened, pushing the NZD to a fresh low for the year near 0.5600.

European markets came under pressure as concerns over France’s fiscal outlook triggered a broader sovereign bond sell-off. France’s 10-year spread to Germany widened above 140bp, from around 100bp two weeks earlier, while spreads also widened in Italy, Belgium and Greece. The move weighed on the euro, European bank shares and broader equity markets, underscoring investors’ sensitivity to fiscal risks across the region.

The US manufacturing ISM edged down in September but remained consistent with solid expansion in the sector, with the underlying details generally firmer than the overall result. The index slipped 0.1 point to 54.5, slightly below the 55.0 consensus. New orders rose to 55.3 from 53.7, while the employment index increased to 52.7 from 51.2, pointing to further near-term gains in manufacturing payrolls. Prices paid climbed to 77.9 from 71.1, reflecting the recent rebound in commodity prices.

Price action was choppy across the intermediate and long end of the Treasury curve, while front-end yields declined steadily. The 2-year yield is 10bp lower as the market continues to pare expectations of near-term Fed tightening. The implied probability of an October hike has fallen to around 30%, with about 25bp of tightening priced across the two remaining FOMC meetings this year. The rally appeared to reflect the softer risk tone, despite the relative resilience of US equities. The 10-year yield traded in a wide range, reaching a fresh cycle high of 5.34% before falling sharply to 5.22%, driven predominantly by a fall in real yields.

The US dollar gained against most G10 currencies, with the DXY reaching a 2026 high as the sell-off in European bonds boosted demand for safe-haven assets. The yen and Swiss franc strengthened against the dollar, reflecting their defensive characteristics. The euro was the weakest G10 currency amid concerns about the impact of France’s fiscal and political uncertainty. EUR/CHF fell close to 1.5% in overnight trading.

The NZD broke below its previous 2026 low near 0.5625 during the local session and extended its decline towards 0.5600 overnight. The move broadly matched the fall in the AUD and reflected the softer risk tone. NZD/EUR firmed, while NZD/JPY fell towards 88.20, also a fresh 2026 low.

Offshore developments continued to drive NZ rates price action in yesterday’s local session. With few domestic catalysts, the swap curve shifted higher and steeper. The 2-year rate partially reversed the previous day’s rally, rising 3bp to 4.08%, while the 10-year rate increased 6bp to 4.08%, returning towards its recent peak. The government bond tender attracted solid demand, with NZ$2.1bn of bids across the two nominal lines. Both maturities recorded cover ratios of close to five and cleared through prevailing market levels.

September ANZ consumer confidence is released today. Euro area flash CPI is expected to rise to 3.7% y/y from 3.3%, consistent with the upside surprises in the national releases and maintaining pressure on the ECB. The key US risk event is the September payrolls report, with consensus looking for a 90k increase following August’s 162k gain. The unemployment rate is expected to remain at 4.1%, with wage growth steady.

Daily exchange rates

Select chart tabs

Source: RBNZ
Source: RBNZ
Source: RBNZ
Source: RBNZ
Source: RBNZ
Source: RBNZ
Source: RBNZ
Source: CoinDesk


Stuart Ritson is a senior Markets Strategist at BNZ Markets.

We welcome your comments below. If you are not already registered, please register to comment

Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.

1 Comments

The Bond Market Just Knocked on the Door

Well, Stuart, this morning's report certainly caught my attention - particularly because it was only yesterday that I did a fairly deep dive into the balance sheets of the major French banks, prompted by the rapidly deteriorating French sovereign position.

What bothered me yesterday was remarkably simple - forget the comforting regulatory alphabet soup for a moment and ask how much actual shareholders' equity sits underneath these enormous balance sheets.

At BNP Paribas, roughly €138 billion of shareholders' equity supports more than €3.08 trillion of assets - around 4.5%. Société Générale is not greatly different, with total equity of roughly 4.8% of assets, or nearer 4.3% if equity attributable to the group is used.

In plain English, we are looking at something approaching €20-€23 of assets sitting above every €1 of accounting equity. That does not mean these banks are insolvent, nor does it mean that a fall in French government bonds translates dollar-for-dollar into losses against bank equity. Duration, hedging, accounting classification and the composition of their securities portfolios are important too.

But this morning's numbers suddenly make the exercise rather less academic - Stuart reports the French 10-year spread over Germany blowing through 140 basis points, having been around 100 only a fortnight ago, while European bank shares were simultaneously being hit.

And this is occurring with French public debt around 119% of GDP, roughly €3.6 trillion, while the sovereign faces another enormous refinancing requirement as the cheap debt issued during the pandemic and energy crises progressively matures.

This is where I think we need to look beyond the daily market explanation. France increasingly has the ingredients of the old sovereign-bank feedback loop sitting in plain sight.

The sovereign's funding cost rises. Existing bonds reprice lower. Refinancing becomes progressively more expensive. Government interest costs rise. Fiscal room contracts. Banks hold sovereign securities directly and indirectly throughout the collateral system, while simultaneously being exposed to the domestic economy that fiscal deterioration ultimately affects.

And sitting underneath all of this are enormous bank balance sheets supported by surprisingly thin layers of actual equity.

Interestingly, the market itself appears to be noticing. Credit-default-swap spreads on BNP Paribas, Société Générale and Crédit Agricole have recently risen much more sharply than the broader European banking measure.

But perhaps the most fascinating number in Stuart's report isn't French at all - the US 2-year yield fell around 10 basis points while the 10-year briefly exploded to 5.34%.

That is hardly a straightforward story about markets suddenly expecting the Fed to tighten aggressively. The short end was simultaneously backing away while the long end demanded substantially more compensation.

That brings us straight back to what I have been banging on about for some time - who is going to be the marginal buyer of this extraordinary volume of sovereign debt, and at what price?

The US has its gigantic refinancing requirement and fiscal deficit. France has its own increasingly uncomfortable refinancing arithmetic. Other European sovereign spreads are widening. 

Japan is dealing with its own bond-market pressures. And governments everywhere are discovering that debt accumulated when money cost virtually nothing doesn't disappear when interest rates normalise - it eventually has to be rolled over.

That is where this becomes structural rather than simply another volatile morning in the markets - and it is precisely why yesterday's exercise looking at actual bank equity rather than merely regulatory risk-weighted ratios is so critical.

#1 A French bank having 4-5% balance-sheet equity is not, by itself, evidence of a crisis.

#2 A French sovereign spread blowing through 140 basis points is not, by itself, evidence of a crisis either.

#3-6 Nor is a falling euro, rising bank CDS, weakening bank equities or a government refinancing hundreds of billions of euros of debt at progressively higher yields.

But put all of those pieces on the same table and suddenly the picture becomes considerably more interesting.

It was just yesterday I was looking at the dodgy foundations, and this morning the bond market gave them quite a shake.

Up
0