
By David Hargreaves
Well, on the one hand, the move by the Reserve Bank to further loosen the limits on banks' house lending is logical enough.
But on the other... it is a risk.
It's clear enough though that under Governor Adrian Orr the RBNZ is more prepared to err on the side of letting the engine run a little hot (and that applies to the economy in general too, not just the housing market) than certainly his predecessor Graeme Wheeler.
Wheeler I think was undoubtedly too cautious by half. Does Orr go too far the other way?
Time will tell.
One interesting development from Wednesday's Financial Stability Report and accompanying press conference was the official recognition that even as the LVRs are loosened, so the RBNZ is now prepared to say they are going to be with us in one way or another, at times obtrusive or at times unnoticeable, for good.
The permanent-temporary measure
This is a departure from what was said when the measures were introduced in 2013 and frequently re-iterated by the central bank subsequently. The moves were clearly described as temporary, even though just about every economist and most writers - yours truly included - believed they would be with us for the duration.
When asked specifically by my colleague Jenée Tibshraeny whether the LVR speed limits were in fact here for good (after earlier giving an answer that indirectly suggested so), Orr replied: "Yes. Will they always be ‘on’?...To be determined."
So, in other words the situation is as economists have surmised. Orr's use of the word 'on' in describing of the status of the LVRs gives credence to the suggestion that the RBNZ would see a time when the LVRs are left in place but are made 'non-binding' on the banks, with the central bank then reserving its right to make them binding again. That means in other words, switch them off and then switch them back 'on' - as may be deemed necessary if fire breaks out in the housing market again.
What's also clear from the Wednesday press conference is that the RBNZ's keen to use other weapons in its armoury apart from the LVRs to keep the banks in sound financial order - with a move to force them to keep more capital being broadly signalled.
Keeping more capital of course would impose its own limits on how much the banks could lend, so would have its own dampening effect on house lending.
It all sounds sensible enough.
However, to look at the specifics of the decision to loosen the LVRs, personally, I would have waited another six months.
By moving now with measures that will take effect on January 1 the RBNZ has certainly helped to give the summer housing market a lift.
People can debate among themselves on this one, but I think the market was looking reasonably buoyant anyway as we head into summer - and this should help.
My concern would be what happens after summer and moving into next winter. And that's where I think the RBNZ, with its next Financial Stability Report due in May 2019, could have waited for six months.
Freeing the investors
And I think most contentious in Wednesday's announcement was the decision to loosen the shackles on the investors.
Just to clearly reiterate what the position will be, it is this:
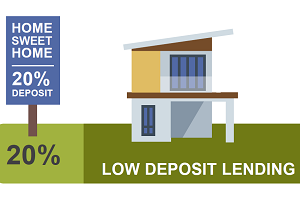
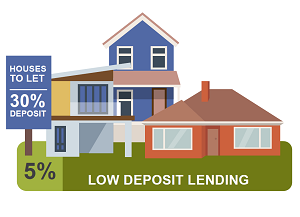
From January 1, 2019 the banks will be able to advance 20% of new mortgage lending to owner-occupiers with deposits of less than 20% of the value of the house. That's a loosening from the current 15% limit figure, which itself was applied as of January this year, having earlier (2013) been set at just 10%.
For investors, they will now (from January 1, 2019) need 30% deposits, down from 35% as of January this year and 40% earlier (2016).
It was the blunderbuss effect of applying the 40% deposit rule in 2016 that really put the handbrake on the housing market, which at the time was looking uncontrollable.
Whereas in mid-2016 the investors were accounting for around 35% of new mortgage borrowing, by the start of this year it had pulled back to only around 20%. Significantly over the same period, the first home buyers, who had arguably been crowded out of the market by the investors, were enjoying an increasing share of the borrowing, moving from single figure percentages to as high as 17.5% share of the market.
My question then really would be, why risk tipping that balance back again by loosening the rules further for the investors?
Leave them be
As I said higher up this article, I wouldn't have made any adjustments to the LVR settings at all at the moment - but if you were going to do it, I would have said, okay, let's see how we go with more relaxation for the owner-occupiers and leave the investors at 35% deposits.
Is there in fact more concern among the RBNZ people than they are letting on that perhaps there might be a significant downturn in house prices without loosening the belts of the investors?
It is interesting to look at the latest monthly RBNZ mortgage figures by borrower type. The figures for October came out on Tuesday. Overall they look fairly solid, with some $5.527 billion advanced. That compares more than favourably with the $4.605 billion advanced in October 2017 - but remember that one was affected strongly by the election and the post-election coalition negotiations. A better comparison is with the October 2016 figure of $5.36 billion - although that was at the time that the 40% investor blunderbuss was starting to really hit.
Anyway, looking at the shares of the money in the latest month, the share of investor borrowing has actually dropped to a new low of 18.7%, and that's a sharp drop from over 21% in September. That does surprise me, given that the figures for the investors had been edging up this year. So, maybe the RBNZ knows a few things about what's going on and is reckoning that the investors maybe do need some encouragement.
In this regard, I was interested in the comments on the LVR moves on Wednesday from the country's biggest home lender ANZ. Antonia Watson, ANZ’s Managing Director Retail and Business Banking. She said what’s had most impact recently on the market was moving the 'bright line test' from two to five years.
Driving them out
"That’s driven a lot of capital gains speculators out of the market which has dampened house price inflation in places like Auckland."
Well, I would imagine that the bright line test, which remember, is the capital gains tax we have without apparently having a capital gains tax, would probably more apply to investors, since most owner-occupiers sure aren't that thrilled about moving house every couple of years.
This all being the case, maybe this move by the RBNZ will head off a big fall in the participation of investors.
Still, I think you can debate about what sorts of share of the market the various types of house owner should have. Certainly at over a third of houses going to investors, I thought that was too many. And the poor old FHBs were not getting a look in.
The October mortgage figures show FHB involvement still as quite strong, with 16.6% of the borrowing going to them.
The relaxation of the 'speed limit' on owner-occupier lending should be good for the FHBs and give even more of them a chance to get into the market. And remember those lucky enough to win Phil Twyford's KiwiBuild lotto are not even included in the LVR 'speed limit' calculations as new builds are exempt.
Giving a lift
This all boils down to the summer housing market looking buoyant. But my concern would be that this move by the RBNZ is going to give the market a lift it possibly didn't need and maybe we will get a short term surge in prices. Maybe the investors will perk up again and climb back in - which will increase the competition for houses, obviously.
The concern principally then is that some FHBs may be tempted to over-stretch themselves in the face of a post-LVR-relaxation mini-boom.
If we then get hit by an external shock as winter approaches next year and if the economy starts to slacken - and people lose jobs - and if maybe interest rates start to twitch upwards (though that's certainly not forecast), well, it might not be good.
What we do want is young people able to buy their own homes. What we don't want is those people to get hit by a market downturn in their early months of them owning their homes at a time when they are financially at their most vulnerable.
The RBNZ has made its decision. I hope it's the correct one.
I would have waited.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.