
Summary of key points: -
- RBNZ ignites more volatility in NZD currency market
- Kiwi dollar rise to 0.6900 “too far, too fast”?
RBNZ ignites more volatility in NZD currency market
Following the two elections (NZ and the US of A) through October and early November, the next big risk event that stood out as influencing the NZD/USD exchange rate direction was the RBNZ monetary policy statement last Wednesday.
Last week’s commentary opined that the RBNZ would “stick to the script” of the previous statement in August, as not much had changed in respect to the outlook for the economy, inflation and employment and the monetary policy stimulus requirement in response.
I should have known better!
The current RBNZ Governor is not that predictable and does like to surprise and catch the markets off-guard.
True to past form, he delivered a statement that was not as dovish as the markets expected and did not attempt to jawbone the Kiwi dollar done as had been the consistent policy in all previous statements.
As a result, the NZD shot upwards instead of the expected short-term sell-off.
The only conclusion one can arrive at is that the most consistent thing about the RBNZ is their inconsistency!
The RBNZ messaging and signalling seems to lurch around from one quarter to the next and this has been the case for more than two years now since Adrian Orr became Governor.
Subsequent to the monetary statement last Wednesday, Assistant Governor Christian Hawkesby tried to explain that the RBNZ did not cause the NZ dollar to appreciate, it was the markets concluding that their previous pricing-in of negative interest rates next March needed to be adjusted back as the new Funding for Lending Programme, if effective, would in a way replace the need for negative interest rates. A rather poor excuse and explanation in my view.
If the RBNZ are doing their job, they should have good market intelligence in advance of all monetary policy statements as to how the markets will react to their words.
They should have known that any lowered level of threat about negative interest rates would send the Kiwi dollar higher.
Perhaps all the personnel restructuring at the RBNZ has reduced this important financial markets resource/presence and they are relying more heavily on the academics who sit as externals on the Monetary Policy Committee instead. I was expecting that by January/February time the RBNZ would be forced by the economic evidence to change their view on the need for negative interest rates. Instead, they essentially delivered that change last week!
An example of the RBNZ’s inconsistency is that fact they delivered several grave warnings about how any appreciation in the Kiwi dollar would damage exporter’s profit margins and restrict the export-led economic recovery when the NZD/USD rate was in the 0.6400/0.6500 region through the June to October period.
When the NZD lifted to 0.6800 in recent weeks (on election results and a weaker USD offshore) the RBNZ abandoned any comment about the exchange rate value! Perhaps they realised that the majority of our major USD exporters are already hedged against a weaker USD and thus their profits are somewhat insulated for the next two years.
One matter the RBNZ have been consistent on is that they have always been prepared to take the risk of doing too much monetary stimulus in response to the Covid economic shock, rather than finding out that they have not done enough.
My view is that they are already past that point of no return with too much stimulus for the current and future economic conditions.
They have flooded the economy with so much cash that out of control asset bubbles like the housing market are fuelled to the point that LVR credit controls will be required again.
Home mortgage interest rates are set to move lower as the banks’ own funding costs are lowered by the RBNZ’s Funding for Lending Programme.
Surprisingly, there were no strings attached to the banks’ lending of the cheap RBNZ funds, free to go into housing loans instead of being restricted to commercial and business lending.
In their attempt to meet their employment objectives, the RBNZ are throwing low-cost credit at the economy in the hope that business will finance new investments/expansion with extra debt.
The clear message from the corporate world, and also the banks themselves, is that business firms do not want to borrow any more (most are reducing debt levels).
The RBNZ’s policy is futile and potentially creating dangerous distortions in the economy.
A more practical message from Governor Orr should have been an admission that monetary stimulus is a blunt instrument and is not effective when additional business debt is not wanted/desired and some industry sectors need it, but most do not.
Governor Orr should have been insisting that the new Government does much more with micro-economic reforms to protect jobs in the industry sectors that need help and to stimulate stronger GDP growth.
To date there is far too much reliance on monetary policy to achieve the employment objectives and both the RBNZ and Government need to recognise this.
Kiwi dollar rise to 0.6900 “too far, too fast”?
The three cent ascent of the Kiwi dollar from 0.6600 to 0.6900 against the USD over the first two weeks of November certainly appears to be “too far, too fast”.
The NZD buying is more of the short-term speculative variety, thus prone to unwinding when new NZD highs fail to materialise.
Adding to the probability of a sizeable pullback in the NZD/USD rate from the current 0.6840 level is the potential for a weaker Euro value against the US dollar over the next few weeks.
Europe is going into much stricter Covid lockdowns than the US, therefore economic outcomes are going to be more negative for the Euro in the short-term.
Whilst the medium term outlook/forecast is for a weaker USD against all currencies in 2021 with the EUR/USD rate moving to $1.2500 and higher, in the shot-term in the lead-up to Xmas the EUR/USD rate is more likely decline to $1.1500 from the current $1.1800 level. The consequential impact on the NZD/USD rate from the stronger USD will be drift back to the 0.6600’s.
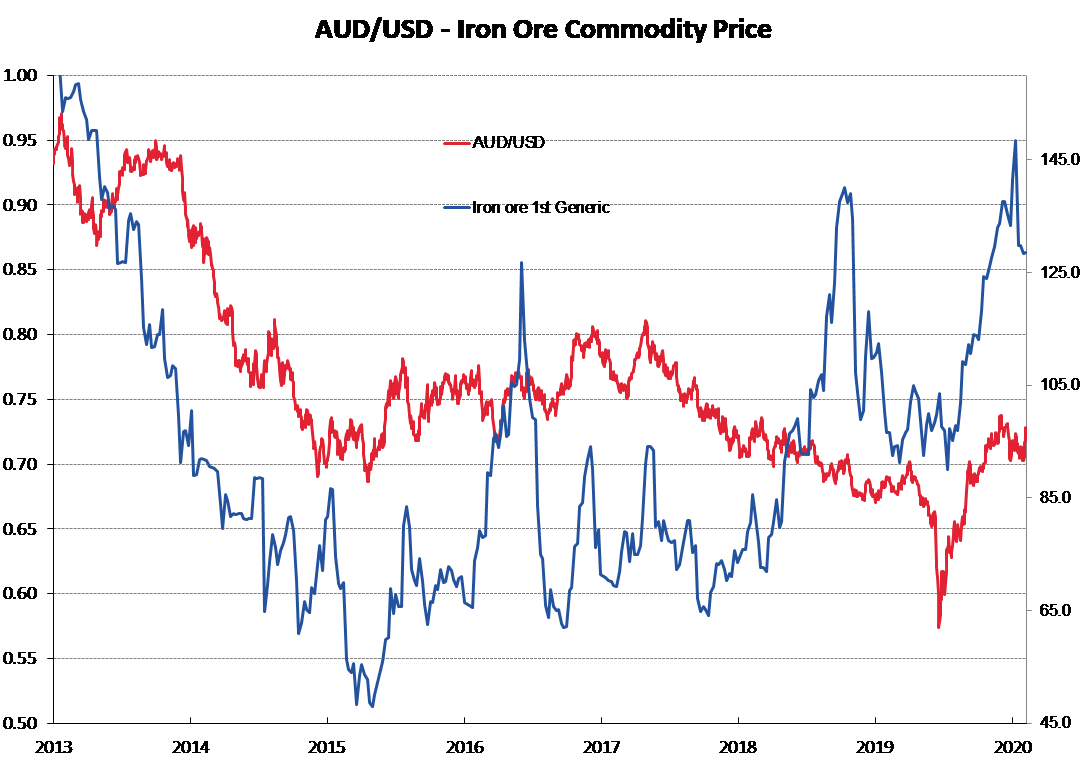
The Australian dollar has not made the gains the Kiwi has achieved in recent weeks. The NZD/AUD cross-rate has lifted to above 0.9400 as a result. At 0.7270, the AUD/USD rate is still more than one cent below its highs recorded in September. The news for the Aussie economy and thus currency has not been that positive of late. The Chinese have them under pressure with trade bans and with the Biden victory in the US, Australia has become the international outlier when it comes to climate change policies.
Further AUD gains to 0.7500 against the USD seem likely in the New Year on the basis of the high iron ore commodity prices, however in the short-term book-squaring before year-end may take the AUD back a little.
The risk of the NZD/USD rate rising to well above 0.7000 in 2021 remains elevated on the weakening USD forecast, however both EUR and AUD influences suggest a corrective phase lower before that.
As is the normal pattern with the NZD/USD rate over the Christmas/New Year period, daily NZD buying by the meat exporters in thin/illiquid FX markets will push the exchange rate upwards in the absence of seller son the other side.
Daily exchange rates
Select chart tabs
*Roger J Kerr is Executive Chairman of Barrington Treasury Services NZ Limited. He has written commentaries on the NZ dollar since 1981.

We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.