
By Roger J Kerr*
It has been an up-down-up movement for the Kiwi dollar over the last seven days. The most appropriate words to describe the Kiwi dollar’s recent performance in the curreny markets would have to be “resilient” and “resolute”, as it stabilises and corrects upwards from the 10 cent depreciation from 0.7400 in April to lows of 0.6427 on 8 October.
As anticipated, the September quarter’s CPI inflation results last Tuesday at +0.90% was substantially above prior market expectations and caused the frist “up” movement in the exchange rate to 0.6600. The outstanding feature of the inflation numbers was that price increases are occuring across the economy, not just the well-publicised fuel price increases.
The other take-out from the inflation outcome was that the RBNZ’s official forecast of a 0.40% increase was another serious forecast miss. On top of their earlier major forecast error for GDP growth for the June quarter, it does raise questions as to their reading of current economic conditions and their forecasting accuracy when they are so far wide of the mark with forecasts for time periods that have just completed.
The financial markets cannot really have too much confidence in the RBNZ’s future forecasting accuracy with this sort of performance record. They have more resources than anyone to track and forecast the NZ economy, so it is diassapointing that their econometric forecasting models are seemingly so inaccurate.
The NZD/USD quickly recoiled from 0.6600 when the minutes of the last US Federal Reserve monetary policy meeting were released mid-week. The US dollar strengthened off the back of the Fed’s economic analysis, reaching $1.1430 against the Euro. The Euro was also under downward pressures from Italian sovereign bonds selling off as the new “anti-establishment” government in Italy seeks to lever the EU authorities to accept their increased budget deficits. The NZD/USD rate pulled back to 0.6525, completing the “down” leg of the movement mentioned above. However, yet again, the USD could not sustain its gains below $1.1500 to the Euro and it has since returned to above that level.
The Kiwi dollar’s subsequent performance to appreciate back to 0.6600 again, despite ongoing volatility in global share markets and lower dairy prices during the week, perhaps underlines how much the Kiwi was over-sold in the FX markets a few weeks back. As this column has stated on numerous occasions over recent weeks, the speculative Kiwi dollar selling has been exhausted and most of the punters are now seeking to take their profits by buying back their Kiwi dollars. A movement in the short-term above 0.6600 will see the NZD/USD rate break out the top of its of its downtrend line that has held in place since April. A move above 0.6600 will also see the spot rate break above the 50-day moving average line form a technical/chart perspective. Just how quickly the Kiwi can climb back to 0.6700 and 0.6800 will largely depend on USD movements against the Euro in the lead-up to the US mid-term elections. I still expect to see USD weakness in the forex markets on political risk factors surrounding a possible change of power in the House of Representatives to the Democrats and a very close battle for the control of the Senate. The strong US economy and labour market would not suggest a massive swing in voter sentiment away from Trump and the Republicans. However, it still appears to be a very divided nation with the current President causing most of the division!
The NZD/AUD cross-rate, after hovering in and around the 0.9100/0.9150 range over recent weeks, has suddenly spiralled up 0.9260 as the Kiwi dollar has outperformed the AUD against the USD. There are two plausible explanations for the Kiwi dollar’s renewed out-performance of the AUD: -
- Previously the financial markets were pricing in a 50/50 probability of the next RBNZ OCR change being up or down. In contrast, the Australian markets were pricing in their next OCR as being upwards and the RBA were endorsing that expectation. The recent NZ inflation and economic growth data being so much higher than RBNZ forecasts has now shifted market sentiment to an increase in the OCR here and perhaps a lot earlier than most thought possible. Well, that’s what the NZD/AUD FX market is telling us with the higher Kiwi value at 0.9260.
- The AUD has been unable to make the recovery the Kiwi has due to weaker Chinese share markets and economic data weighing the currency down.
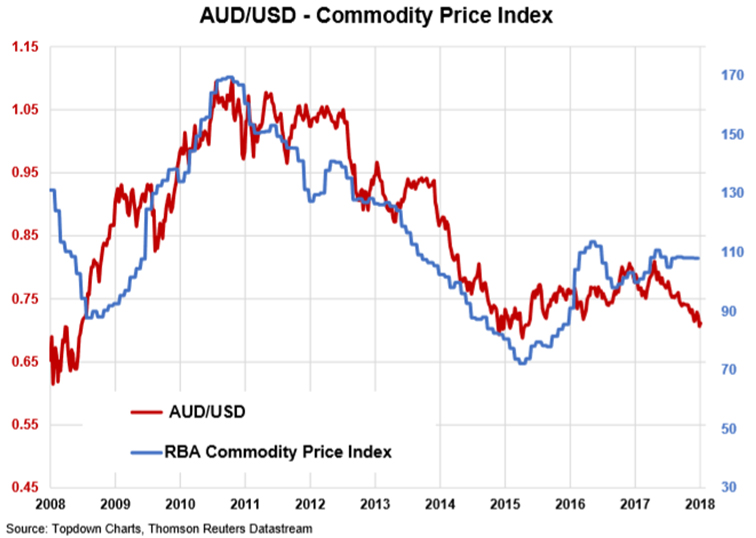
As stated in previous columns, further significant weakness in the AUD against the USD below 0.7000 is not expected. Their metal and mining commodity prices have not decreased over recent months and the close historical correlation between their commodities and currency value suggests the AUD/USD should be higher towards 0.7500 at least. The second reason why the AUD should hold above 0.7000 is the view that the Chinese monetary authorities will actively stop their Yuan exchange rate weakening above 7.00 to the USD. The Americans just stopped short of labelling the Chinese as currency value “manipulators” this last week, but the Chinese will not want to allow the US to use Yuan currency weakness as leverage over them in the trade battles. As the second chart below shows, the AUD/USD rate has closely followed the fortunes of the Yuan over the last 12 months.
Daily exchange rates
Select chart tabs
*Roger J Kerr is an independent treasury Management advisor. He has written commentaries on the NZ Dollar since 1981.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.