
The economy has spoken. We just don't know what it said.
Yes, the economists promised us 'noise' ahead of the release of the latest GDP figures. And we got that. In spades. But clarity? Not so much.
As a non-economist, I like to try to keep things simple. So, amid the data released by Statistics New Zealand last week that showed various parts of the economy seemingly going in different directions, there were two standouts.
First, the service industries grew a whacking 2.7%. Second, household spending slumped 3.2%.
Okay, on the first one, let's face it, we would have hoped like hell there would be something of a reasonable bounce. The March quarter was affected by the soaring outbreak of Omicron, and of course, GDP as a whole shrank by 0.2%.
The June quarter saw Omicron subsiding and a consequent easing of restrictions. Crucially the June quarter also saw the easing of travel restrictions. If you are going to let people travel freely for the first time in over two years, you would hope that at least some people are going to do that! A big surge for the travel-related industries should not be an almighty surprise! As I say, it would have been a very nasty surprise indeed if we had not seen something of a surge.
So, in terms of services, we are talking about a bounce off the floor. I don't personally think this shows us a raging economy. It shows some pent up demand being released. But I don't think it tells us too much about spending patterns in the immediate months ahead. As I say, we would be worried about the future of the travel industry if people didn't start to travel again once allowed. And likewise a few tourists here spending hard-earned will all help too.
Better therefore to not talk about 'strength' in those service industry figures. Talk about 'recovery'.
Right, before I talk specifically about the drop in household spending, it is worth going back to what the expectations were for the June quarter GDP.
Economists' forecasts were unusually widely spread, highlighting the difficulty in trying to read how an economy that's been as buffeted as it has is performing.
Apparently the range of forecasts straddled from 0.0% to 1.8%, remembering of course that the actual figure came in at 1.7%. And who was the 'outlier' at 1.8%? Well, it was... The Reserve Bank (RBNZ).
That's right, the folk that are currently physically trying to take heat out of the economy by hiking interest rates, were the folk that had the 'hottest' prediction for how the economy fared in the June quarter. In terms of predicting the outcome of GDP for the quarter, RBNZ shared the chocolate fish with Westpac economists (who said 1.6%).
So, think about that. The RBNZ, which is charged with trying to slow the economy and get inflation (annual rate last seen at 7.3% as of June quarter), back into a 1% to 3% range, was the organisation that had the most bullish view of how the economy was travelling in the June quarter.
It would be very interesting to know just what the breakdown was of that RBNZ 1.8% pick, but I'm happy to speculate that it may well have been somewhat how things turned out - IE, service industries bouncing, but household spending falling.
The latter is EXACTLY what the RBNZ would want to see. It indicates that the screwing up of interest rates is having an impact.
Now, what would the RBNZ want to see in the immediate future? Well, more of the same on the household spending front. And then a 'settling' of activity in the service industries.
Those GDP figures released last week, 'noisy' and all over the place as they are, have had quite a market impact. ASB economists immediately raised their expectation of a peak Official Cash Rate to 4.25% from 4% previously, and the following day economists at the country's largest bank, ANZ, came out with a market leading forecast of an OCR peak of 4.75% next year.
The wholesale interest rate markets have been moving up also - though of course expectations for what might happen with the latest US Fed decision will have been helping fuel this. The wholesale markets are now fully 'pricing in' an OCR peak of 4.5% by the middle of next year.
For its part, the RBNZ in its most recent Monetary Policy Statement in August forecast a peak OCR of just over 4.0% next year. The OCR forecasts are the column on the extreme right of the below table:
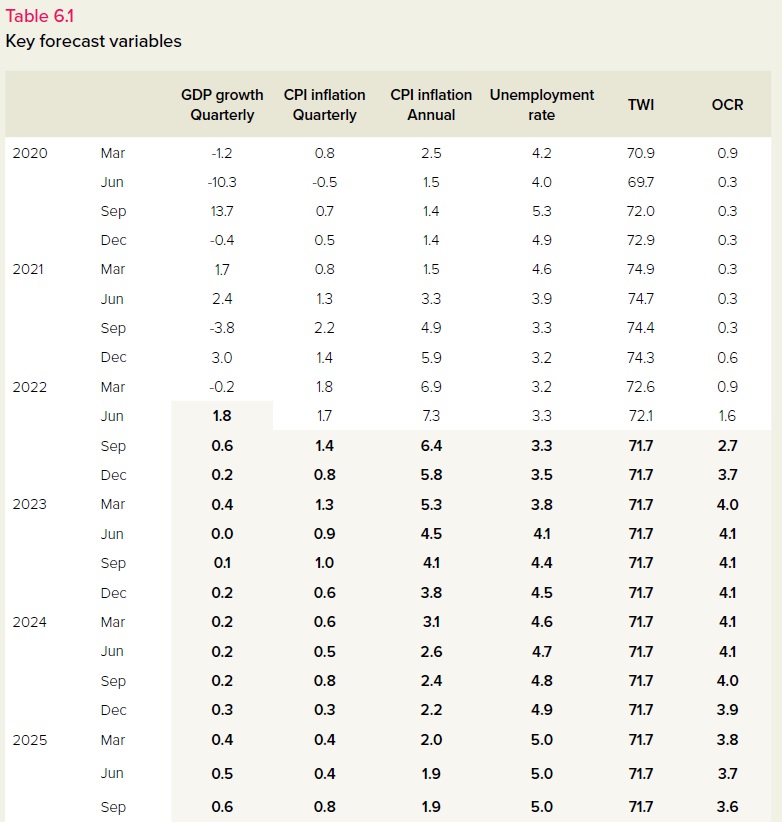
At the moment the OCR is at 3.0%, having been hiked massively from just 0.25% as at the start of October 2021. Each of the last five OCR reviews have seen 50-point hikes and I think it is virtually guaranteed that we will see another 50-pointer at the next review on October 5 and then one more 50-pointer for good measure at the final review for the year on November 23.
Now, remember, these forecasts by the RBNZ were arrived with it thinking that GDP would grow by 1.8% in the June quarter. So, the actual 1.7% result is NO surprise to the RBNZ, even if it is to some economists.
Why, therefore, would the RBNZ see the need at this stage for a higher OCR than it has already forecast?
I don't know how good I am at reading body language, but it seemed to me that during the August OCR review the RBNZ folk were very comfortable with how they were placed in terms of starting to get a handle on the big job of bringing inflation down. And they expected GDP to rise 1.8% in the June quarter.
What are they expecting for GDP in future? Well, those picks are in the left-hand side column of the above table. In short, the RBNZ is not forecasting the death of GDP, but close. There's no forecast of a recession, which is good.
But on the other hand, could we reasonably expect that a central bank that's currently grabbing the economy by the gonads to bring down inflation WOULD forecast a recession? Well, I wouldn't.
If you look at the figures above from June 2023 to September 2024 they range from 0.0% growth to 0.2% growth, IE hardly any growth at all. And indeed, it would only take very small downside misses on those forecasts to see us rack up six consecutive quarters of negative GDP growth. Now that, people, is a recession. A real one.
And, at the risk of labouring a point, the RBNZ, having expected GDP growth of 1.8% in the June quarter, is making these forecasts based on its current forecast trajectory for the OCR with a peak of maybe 4% or a little more. But crucially, it is now pushing the point that the OCR may stay at such levels for quite a while. So, in other words a slow and gradual squeeze of the economy, rather than a knockout punch.
The fact that the 'market' is now assaying the possibility of a 4.5% OCR, with wholesale interest rate pricing to match, means we may well see some upward moves quite soon from the banks on fixed mortgage rates - since of course it is the wholesale interest rates that have the most direct influence on the banks' cost of funds.
Would the RBNZ mind the banks getting ahead of themselves (again) a bit? I don't think so. Remember, fixed rates have eased a little since early July (when the average one-year mortgage rate was about 5.25% and the average two-year about 5.6%) to around 5.1% and 5.45% at time of writing.
The point is, at the moment, I think the RBNZ believes it has 'got this' (better late than never!) and that an OCR of around 4% for some time will do the trick, the economy will slow, and inflation will dwindle.
The big, big thing that could derail all this is the labour market. And I will get back to you on that one with a fulsome examination and explanation.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.