The Kiwi dollar has traded within a 0.6600 to 0.6660 band over this last week against the USD and has been unable to scale the heights of 0.6750 reached in illiquid holiday market conditions over the first few days of January.
There has been no domestic economic news of any note to influence the exchange rate significantly up or down, apart from a marginal improvement in business confidence in the NZIER quarterly survey results.
The manufacturing PMI Index fell in the December month to 49.3 from 51.4 in November. The result was less than prior market expectations, so was a negative factor on the Kiwi dollar, pulling it back from 0.6650 to 0.6615 on Friday 17 January.
The local economic performance remains mildly positive with retail, construction and housing improvements countering off against a decidedly flatter trajectory for tourism and manufacturing currently.
The one disappointing and concerning development in the NZ economy as a new year commences is that confidence, spending and investment levels in the dominant agricultural sector are poor despite record high prices for livestock and produce.
In normal times of super high export commodity prices, our farmers would be buoyant and upbeat. Typically, there would be a major economic impulse coming out of the rural regions with plenty of cash sloshing around.
Sadly, today many farmers are grumpy and disillusioned as they face multiple bureaucratic interventions on how they farm their land and run their businesses.
The current Government and other agencies are forcing unknown costs and compliance regimes on farmers from water to methane to health/safety to pointless resource consents.
The environmental/climate change lobby is enforcing impositions on our major industry that if continued will lower economic growth and living standards in New Zealand.
The mainstream media centred in the cities generally has a poor understanding of the significance of these farming issues, however the sector still powers the economy.
Spending and investment levels in the dairy sector are also muted despite the milk-solid pay-out returning to near record high levels.
Bank lenders are requiring debt reductions ahead of re-investment in productive capacity.
The horticulture industry however goes from strength to strength with kiwifruit and apple exports continuing to increase.
Unfortunately, rural New Zealand has diminishing political clout (due to population changes) to challenge several current Government policy initiatives that appear to be anti-farming.
RBNZ to remain “on-hold” for all of 2020
The next piece of data in the local NZ economic jigsaw is the inflation outcome for the December quarter on Friday 24 January.
Consensus forecasts are for a 0.40% quarterly increase, which will lift the annual inflation rate from 1.50% to 1.80%. Hardly a trend that justifies any consideration from the RBNZ of further interest rate cuts or money market forward pricing of such. A result above +0.40% will be positive for the Kiwi dollar.
We will hear next from the RBNZ on 12 February with their Monetary Policy Statement.
A feature of their updated economic prognosis should be the material reduction in global economic risks with a truce in the China/US trade war and Brexit finally happening.
No doubt they will find some other economic headwinds elsewhere to be overly cautious about.
However, in reality there is no economic trend or forecast to be negative about currently.
The flip-flopping of the RBNZ from overtly dovish to not dovish on the economic outlook has caused a good deal of the volatility in the NZD/USD exchange rate over the last 24 months. It is past time that they display some consistency in their outlook as our actual economic growth performance has been much more consistent in the 2% to 3% area than the central bank’s changeable viewpoint!
I do not expect the RBNZ’s decisions this year with monetary policy to impact NZ dollar movements at all as they are “on hold” with interest rate changes and will stay that way all through 2020.
AUD under-valuation over due for recognition
The Australian dollar has not matched the Kiwi dollar's impressive 6% recovery upwards against the USD over recent months.
The AUD exchange rate against the USD has only appreciated 2.7% from a low of 0.6700 in early October to 0.6880 today.
Currency speculators in the AUD have not unwound short-sold positions as much as the Kiwi dollar speculators did in late December.
Despite the terrible bushfires causing some minor uncertainties for the Australian economy at the moment, their outlook is also positive with global trade and industrial production expected to improve now the trade war and Brexit risks have reduced.
On many counts the Australian dollar is considered undervalued today as investment funds moved out of the AUD 12 to 24 months ago and have not yet returned. It only seems a matter of time before the undervalued position of the AUD is more fully recognised and funds rotating out of safe-haven currencies like the Yen and USD will buy the Aussie.
The Australian economy is heavily dependent upon China. The Chinese Government has made policy changes to get the Phase 1 trade deal done with the Americans and they have also loosened monetary policy of late to keep the growth engine going. The Chinese are also continuing (as expected) to strengthen the Yuan currency value, now at 6.86 to the USD.
Over the first half of 2019 the vast majority of Australian bank and global investment bank economist forecasts were for the Australian housing market to plummet, the economy to go into recession and the RBA to slash interest rates to zero. They were all wrong, none of those things happened.
The Australian dollar is over-due for a re-rating upwards against the USD.
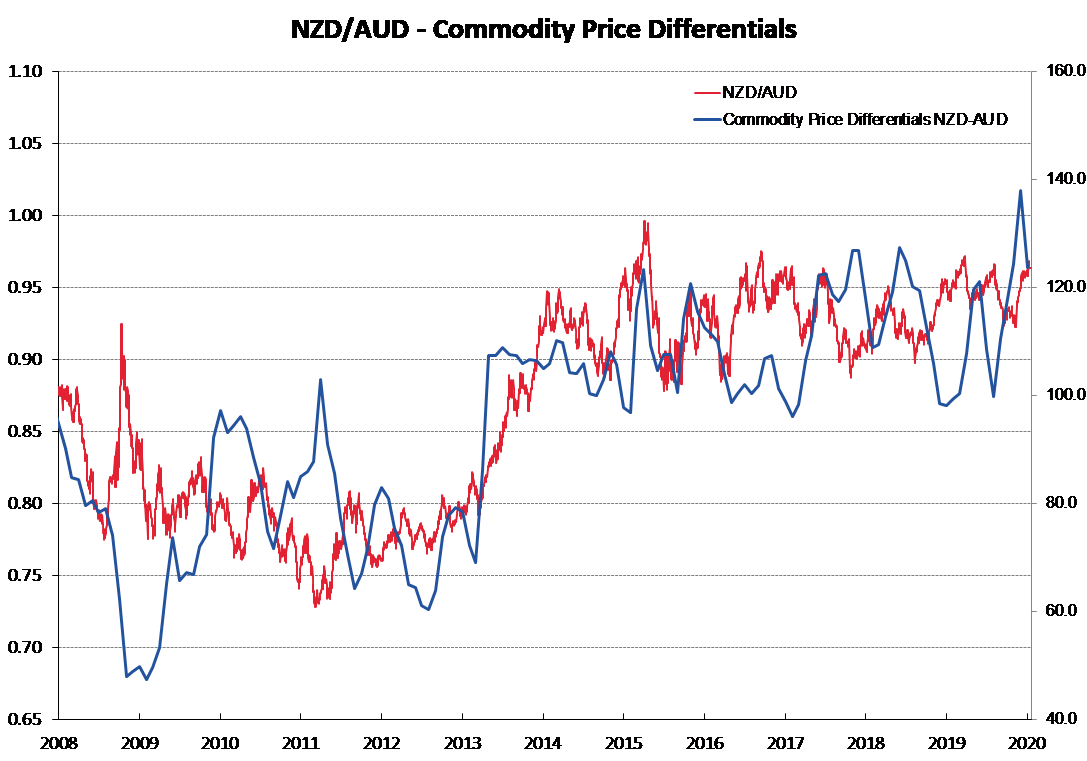
The Kiwi dollar’s out-performance of the AUD against the USD has driven the NZD/AUD cross-rate up from 0.9230 in November to a high of 0.9700 on 8th January. Over the last five years the bottom of the NZD/AUD trading range has progressively lifted upwards from 0.9000 to 0.9100 to 0.9200. The local AUD exporters who have maintained a discipline of increasing hedging percentages in the 0.9200/0.9300 area have again been well rewarded.
Over coming months, the NZD/AUD cross-rate is forecast to fall back to below 0.9400 as the AUD catches up and outperforms the NZD in the currency markets.
Daily exchange rates
Select chart tabs
*Roger J Kerr is Executive Chairman of Barrington Treasury Services NZ Limited. He has written commentaries on the NZ dollar since 1981.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.