
Summary of key points: -
- EUR/USD sideways shuffle continues
- Russians have already achieved their objective with Ukraine
- RBNZ need to stand up and address underlying inflation sources
EUR/USD sideways shuffle continues
US equity markets have settled down over recent weeks following their tumble in January in a delayed reaction to a more hawkish Federal Reserve.
As a direct result, the Kiwi dollar has also stabilised in the lower 0.6600 to 0.6700 trading range. However, daily volatility has not reduced with the NZD/USD exchange rate jumping about following the marginally higher than expected US inflation for January released on Thursday 10th February.
Largely following the Euro and Aussie dollar against the USD, the Kiwi initially ramped higher from 0.6650 to 0.6730 when the FX markets took the view that the European Central Bank may have to hike interest rates as fast as the Fed, thus strengthening the Euro.
The EUR/USD rate almost hit $1.1500 at one point during that day’s trading, however it just as quickly re-traced its steps and fell away to $1.1350. The NZD/USD rate in tandem returning back down to 0.6650.
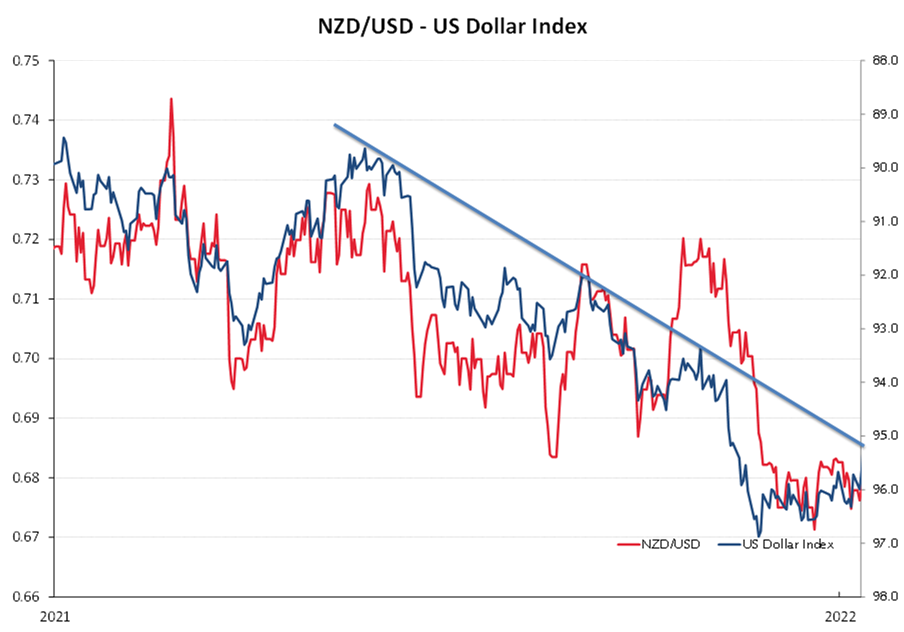
Whilst the NZD/USD rate movements have been dominated by the USD side of the equation over the last 12 months (reflected in the NZD/USD rate closely tracking the EUR/USD rate), that does not necessarily mean that local NZ economic factors have been totally dismissed as influencing the Kiwi dollar value over the next 12 months.
It appears that the global currency markets are still attempting to work out whether the Fed pushing US interest rates up this year is already fully priced-in to the US dollar value, or not.
The view of this column over recent months has been that the upcoming US interest rate increases are indeed fully factored-in already and the USD will end is strengthening trend.
The flickering of the EUR/USD exchange rate up and down between $1.1500 and $1.1150 since October 2021 points to the FX markets being very undecided as to whether the USD has come to a turning point. We will back the old adage that when the Fed actually raise rates (which will be next month), the US dollar generally starts to weaken from that point as all the buying of USD’s has already taken place beforehand in the expectation.
The sideways shuffle in the EUR/USD that confirms the market indecisiveness will not continue forever.
A crunch time for the USD may be looming as it fails to continue its upward momentum on the USD Currency Index. A weakening in the USD on its Index from the current 96.0 level to below 95.20 would break its uptrend of the last 12 months (refer chart below). Events that would be candidates to be that catalyst that causes USD selling will be; weaker than expected US economic data, the Fed going at a slower pace than what the markets are currently pricing and the ECB bringing forward their lifting of interest rates this year
Russians have already achieved their objective with Ukraine
Geo-political tensions are often represented in currency market movements. We have not seen the USD strengthen on the back of the potential invasion of the Ukraine by Russia, which is the traditional response of FX markets to the possibility of war.
Perhaps the Russians have already achieved their objective from their sabre-rattling, that is to get the oil price up to help their economy. It should be positive for equity markets and the Kiwi dollar when the Russian eventually de-escalate their military build-up.
RBNZ need to stand up and address underlying inflation sources
It is very clear that National Opposition Leader, Christopher Luxon and Finance Spokesman, Simon Bridges intend to shift the dial on the economic and political debate this year away from COVID and onto our inflation problem.
For the average, low-income household in New Zealand continuing rising costs is of much greater concern and impact than the mild Omicron strain.
There are no easy solutions to New Zealand’s inflation problem in 2022.
Increasing interest rates will reduce the demand side, however the majority of the price increases are coming from the supply side, namely: -
- Tradable inflation imported from offshore (oil, commodity prices, shipping, product shortages).
- Non-Tradable inflation generated domestically (local government rates, electricity, home-building costs).
The Prime Minister is blaming the increased inflation entirely on the imported tradable part. As has been the pattern with the current Government the “communication spin” seeks to divert blame elsewhere and does not tell the full story.
As this column has banged on about ad-nauseam for a long time now, non-tradable inflation has been out of control in New Zealand for many years, and no-one seems prepared to address the sources of that inflation and do something about it.
The RBNZ have a prime opportunity to apply their intellectual rigor and economic analysis to identify the core causes of the persistent non-tradable inflation in their upcoming 23 February Monetary Policy Statement.
Don’t hold your breath, they seem weirdly more pre-occupied with diversity and climate change as major issues. Regulation overload and Government policies are behind the constant price increases in local government rates and building costs.
Identical to the Fed, the RBNZ are arguably behind the 8-ball in lifting interest rates to control the rising inflation. The risk is that they are now forced to tighten monetary conditions too quickly to catch up, causing the economy to slow too abruptly i.e. a hard landing.
RBNZ Governor, Adrian Orr, to his credit, did foresee this current situation when he slashed interest rates to zero and printed money two years ago. He stated at that time that if the extraordinary monetary stimulus caused speculative asset bubbles and high inflation, it was a risk he needed to take and would deal with the high inflation when it occurred. That day has now arrived Adrian and you cannot be timid in dealing with it.
A more hawkish RBNZ in 10 days’ time will be positive for the Kiwi dollar.
Looking ahead, this year may turn out to be the classic “game of two halves” for the Kiwi dollar.
An appreciating NZ dollar over the first half as the RBNZ need to go harder than the market is expecting and potentially a weaker Kiwi dollar over the second half of the year as the economy underperforms under the weight of the tighter policy. Reduced consumer spending (due to higher mortgage interest rates), inflation and labour shortages will also contribute to the weaker economy.
Daily exchange rates
Select chart tabs
*Roger J Kerr is Executive Chairman of Barrington Treasury Services NZ Limited. He has written commentaries on the NZ dollar since 1981.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.