Summary of key points: -
- Monetary policy imbalances show up in exchange rate movements
- New Zealand’s domestic inflation problem – identify causes and enact solutions
- Crucial signpost for US inflation, interest rate and currency direction this week
Monetary policy imbalances show up in exchange rate movements
Global exchange rate movements over this last week have identified and confirmed the differing approaches and settings to monetary policies at this time.
The US Federal Reserve is clearly prepared to be very patient before embarking on interest rate cuts, they want to receive a high level of confidence that their inflation rate is heading to the target of 2.00% before committing to a policy adjustment. In stark contrast, the Japanese and Europeans appear to be a sixes and sevens with managing monetary policy, resulting in both the Japanese Yen and the Euro being sold against the US dollar over the last week. However, the NZ dollar and the Australian dollar have not lost ground against the USD, remaining close to the middle of recent trading ranges at 0.6150 and 0.6650 respectively. The recent message from both the RBNZ and RBA is that they are not comfortable with their sticky/high domestic inflation situations and therefore monetary policy has to remain at restrictive/tight levels for some time yet to pull that inflation down i.e. interest rates stay higher for longer in New Zealand and Australia
The problem with Australia is that the RBA never increased their interest rates in 2023 to a high enough level to change price setting behaviour in their economy. They are now paying the price for that policy error and a number of Aussie economic commentators are now calling for further RBA interest rate hikes from the current 4.30% level to drive inflation down earlier, than otherwise would be the case. The prospect of Australia increasing interest rates over coming months when everyone else (NZ excluded) is looking to cut interest rates is a real and growing probability. The key determinant as to whether the RBA hike rates, or not, will be their June quarter CPI inflation result due for release on 31 July. Current headline Australian inflation is 3.60%, which is forecast to reduce to 3.20% if the June quarter increase is +0.60%. Some economists are suggesting that the quarterly increase could be as high as 1.00%. If the quarter’s outcome is between +0.60% and +1.00%, the end result is that RBA Governor Michelle Bullock will have run out of patience and could well hike. The monthly CPI inflation indicator for May is set for release this Wednesday 26th June and prior forecasts are for the annual inflation rate to the end of May to have increased from 3.60% to 3.80%. The next RBA meeting on Tuesday August 6th stands as a potential major turning point for the Aussie dollar, an interest rate hike will send the AUD/USD above 0.6700 to 0.7000 in a flash.
The Japanese Yen has continued to depreciate against the US dollar as the Bank of Japan dilly-dally on their monetary policy management. Go back a few months, we had confidence that the Japanese would make decisions to change their monetary policy from negative interest rates to positive interest rates as wage increases in their economy were pushing up inflation. Unfortunately, the Bank of Japan appear very reluctant (scared?) to enact the necessary monetary policy changes. Their frustrating hesitancy to do the inevitable has resulted in the FX markets lambasting the Yen as the 5.00% interest rate gap to the US dollar makes it a “no brainer” carry-trade bet. The Japanese have intervened in the USD/JPY currency market to the tune of US$60 billion so far to halt the Yen slide. The intervention may have held the Yen below 156.00 during April and May, however the absence of Japanese interest rate increases has resulted in another Yen sell-off to 159.80 over recent days. The Bank of Japan’s next meeting is also 31 July, however there is a “summary of opinions” report from them on Monday 24th June. The Yen will remain under downward pressure until they actually make a decision to increase interest rates. The fact that the US is about to officially call-out Japan (alongside China) as a “currency manipulator” might be enough to embarrass the Japanese into taking some action.
The sell-off in the Euro from $1.0900 on 3rd June to below $1.0700 today had more to do with political events in France than the decision by the ECB to cut their interest rates by 0.25% on June 12th. The French economy has taken a real hit since President Emmanual Macron called a snap election a week ago. Business activity/investment and services industries (hospitality) have contracted due the uncertainty surrounding the election that takes place in two rounds of voting on June 30th and July 7th. Foreign investors into France are running for the hills and the negative sentiment has hurt the Euro. The Swiss central bank decided to cut their interest rates for a second time last week, adding to the downward momentum on the Euro. The ECB are unlikely to lower their interest rates again for quite some time, that in itself is supportive of the Euro if the US Fed cuts rates in September, November and December.
New Zealand’s domestic inflation problem – identify causes and enact solutions
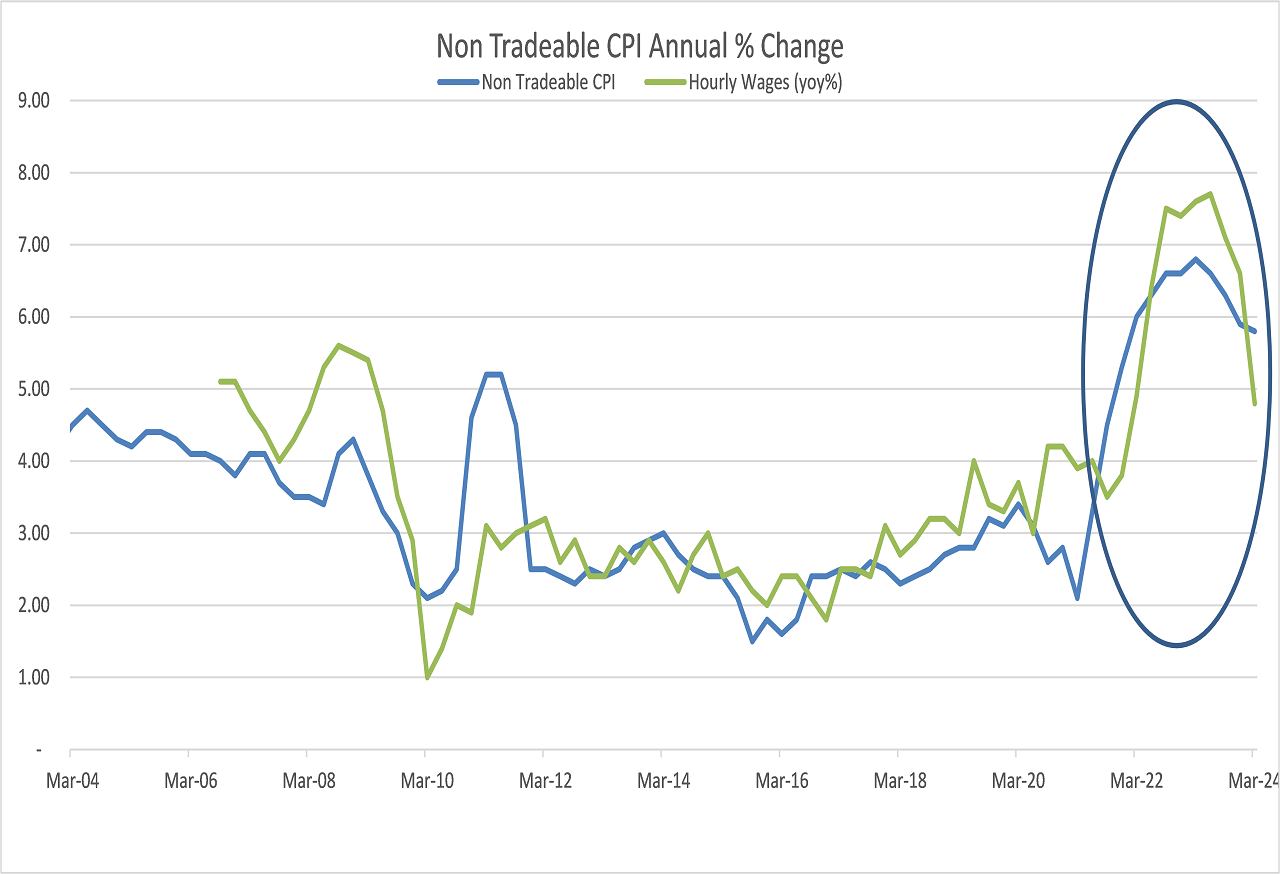
Over recent years this column has repeatedly highlighted and documented the “elephant in the room” problem New Zealand has with permanently high domestic/non-tradeable inflation. The solid rump of +3.00% persistent non-tradeable inflation is by no means new; it has been in place for more than a decade. The imported deflation from China over the 2014 to 2020 years just disguised the problem. The extraordinary and excessive monetary and fiscal stimulus measures in the Covid years covered the problem over again. As the chart below confirms, the immigration policies of the previous Ardern Government that caused acute labour shortages in 2021 to 2023 exacerbated the wage-push inflation problem further, resulting in the 5.70% non-tradeable inflation rate we have today. Percentage wage increases are now declining rapidly; however, it is not just wage increase that is behind the high non-tradeable inflation.
The sources and root causes of our persistently high domestic inflation fall into two categories: -
- Lack of competition in some domestic industry sectors – Open and robust market competition is the best discipline to keep prices/inflation low. Unfortunately, the NZ economy does suffer from a low level of “economies of scale” in many industries to create that fierce competition between suppliers of goods and services. The duopoly in retail supermarkets will not change unless a global player such as Aldi comes in and disrupts (as has happened in Australia). The New Zealand market is just not big enough population -wise for Aldi to make it work. Similarly, competition is more “cozy” than “fierce” in banking, insurance, energy, construction and domestic air travel.
- Out of control price setting behaviour in the public sector – Any examination of the component parts of non-tradeable inflation will reveal that fees, charges and prices are consistently increased by more than 3.00% every year for many years by Government departments, Local Government and Government controlled sectors such as education and health. Imposed legislative and regulatory changes results in cost increases (mainly additional people being employed) being passed through into higher prices charged to households. There is no competition and there is no control. Local Government rates (10% plus increases coming into the September quarter’s CPI numbers) is the worst offender. Housing rents have been pushed up in recent years by the previous Government’s tax and tenancy policies.
Whilst belatedly identifying and highlighting these sources of high non-tradeable inflation (which are just not sensitive to interest rates) in their latest monetary policy statement, the RBNZ offered no suggested solution to rectify the problem. Neither do you see solutions being suggested by politicians or bank economists or business associations to the New Zealand economy’s most pressing problem. Surely, someone has to take ownership and make some bold and innovative changes here. Whilst there are no “eureka” solutions to the first category of root causes of domestic inflation, the second category needs some shock treatment of a Government imposed “price freeze” on their own Government departments, which in turn will incentivise/force them to became smarter and more efficient on their cost side to balance their books. It just needs political leadership and the growing of some gonads to make changes!
As we have previously stated, the RBNZ have not helped themselves to get inflation down to within the 1.00% to 3.00% target band. Under Governor Orr, they have refused to use another tool available to them in their monetary policy kit bag, and that is orchestrating a higher NZD currency value to force tradable inflation down to offset the non-tradeable inflation they have no control over. A stronger NZ dollar will only eventuate if you push NZ interest rates well above US interest rates. The RBNZ have not recognised that or done anything about it. If higher interest rates above 6.00% is just too painful for the economy, they could alternatively “jawbone” the NZ dollar upwards by stating that a higher NZD value would be desirable to push inflation lower. Governor Orr appears frightened of mentioning the NZ dollar value, previous Governors such as Don Brash and Alan Bollard would have played this card by now.
Crucial signpost for US inflation, interest rate and currency direction this week
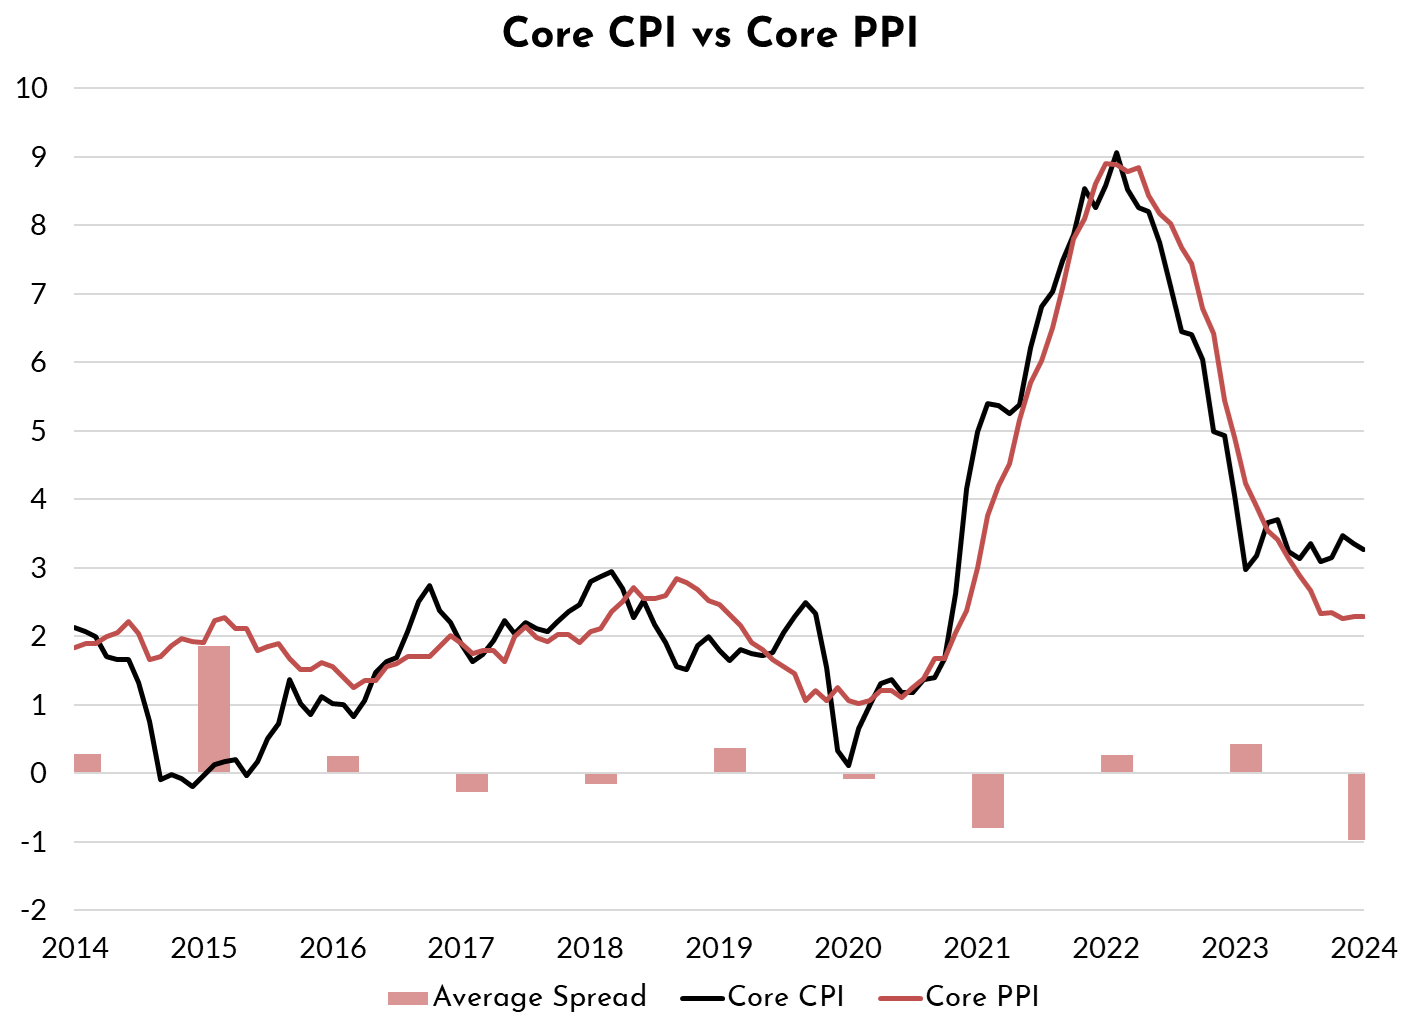
Consensus forecasts are for a 0.10% increase in the US PCE Price Index for the month of May when it is released this coming Friday night 28th of June. A lower 0.10% increase would break the sequence of higher 0.30% monthly increases recorded in February, March and April. A +0.10% change will reduce the annual PCE rate of inflation from 2.70% to 2.60%. The Fed members say they need more evidence and confidence that US inflation is tracking sustainably lower. If June and July monthly PCE increases are also low in the 0.10% arena, the annual PCE rate of inflation will not move down from 2.60%, as the May, June and July 2023 monthly increases were all less than +0.20%. However, if the Fed members observe the trend (and also take into account wholesale PPI prices already reduced to a 2.00% annual increases – refer chart below) and project forward that the August and September 2024 price increases will be a lot less than the 0.40% increases in August and September 2023, they will have a lot of certainty that the PCE annual inflation rate will be hitting the 2.00% target by 30 September. In other words, they are very close to achieving their inflation target over the next three months.
A Fed rate cut is ruled out for their 31 July meeting, however three successive 0.25% cuts cannot be rule out for their 18 September, 7 November and 18 December FOMC meetings. The US interest rate market is today only pricing-in one and a half cuts by year end, however that pricing can shift rather quickly if the inflation scenario painted above transfers into reality. The USD Dixy Index has shot back up to 105.48 on the recent negative Japanese and French developments. The stronger USD is not reflective of generally softer US economic data and the likely PCE inflation picture painted above.
The major risk to the weaker USD (hence higher NZD/USD rate) over coming months is the potential for global trade wars involving China against the US and Europe. Thankfully, China and the EU have agreed to hold-off on tariffs on electric vehicles for the meantime. A Trump victory in the US Presidential election would increase the risk, however there is no certainty about that.
Daily exchange rates
Select chart tabs
*Roger J Kerr is Executive Chairman of Barrington Treasury Services NZ Limited. He has written commentaries on the NZ dollar since 1981.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.