Summary of key points: -
- Another surprise from Adrian – where to from here?
- Higher USD and US bond yields set to reverse
Another surprise from Adrian – where to from here?
We all should have expected that RBNZ Governor Adrian Orr would deliver the unexpected at last week’s Monetary Policy Statement.
Governor Orr’s track-record and reputation of wrong-footing the markets and making a splash have been well documented in the past. It is hard to understand what it proves and contributes in terms of monetary policy management. The constant surprises from Orr that cause market interest rates and exchange rates to gyrate in response are arguably contrary to one of the principles of the RBNZ’s inflation target agreement with the Government – “maintain inflation stable and low without causing undue volatility in exchange rates and interest rates”. Unfortunately, the RBNZ fail to measure and report on this important aspect of their remit.
The RBNZ decision to call a halt to further interest rates increases is a bold call, however one that was always going to send the Kiwi dollar lower as it was polar opposite to the prior FX market positioning. The FX market was primed up for a 50% chance of a 0.50% interest rate hike with potentially more to come and what they received was a 0.25% increase and a message that there would be no more increases. The market reaction was swift and severe with the Kiwi dollar sold down more than two cents from 0.6275 prior to 0.6060 afterwards. Not helping the sentiment towards the NZ currency was ongoing US dollar strength against all currencies as the US Government debt ceiling saga created risk and uncertainty and therefore safe haven flows into the USD. Typically, the NZD/USD moves up or down by 1.5 to 2 cents in reaction to RBNZ surprises, however within a week the exchange rate normally returns to where it started before the RBNZ announcement.
Whether the NZD/USD exchange rate can hold above 0.6000 in the short-term and return to its previous 0.6150 to 0.6350 trading range will totally depend on USD direction over the next week in the lead up to the US debt ceiling deadline date, which has now been extended by their Treasury to 5 June. As progress is made by the US politicians to a compromise deal on spending and deficits, we are likely to see some unwinding of large, long USD positions built up in the FX markets over recent weeks as the debt ceiling crisis caused USD buying. The expected USD selling on profit-taking may well start before a deal is announced.
The RBNZ decision to pause on further interest rate increases raised more questions for market participants than it answered, the major concern being the sheer inconsistency in their economic outlook.
- What changed in the economy between the “hawkish” 0.50% OCR increase on 5 April 2023 until the “dovish 0.25% increase and done” on 24 May? In terms of inflation trends and outlook, nothing changed. It seems the RBNZ visited some companies and were told that “demand was softer.”
- What is behind their forecast of net migration reducing over the next 12 months and their statement that the impact of the current strong inwards migration on the economy is “uncertain”? The majority of bank economists increased their OCR terminal rate to 5.75% and 6.00% because of the continuing strong net migration numbers and the impact of that on inflation.
- After sending the Government a warning shot about increased spending being inflationary in April, the RBNZ acquiesced totally in May by stating that the spending does not increase in the medium term. However, the battle to bring inflation down is over the next 12 months and over that period Government spending does increase. The fiscal impulse is still inflationary over the next two years. Prior to the RBNZ decision, Finance Minister Grant Robertson said that he saw no reason for interest rates to go above 5.50% (which is highly unusual for a NZ Finance Minister). Questions over the RBNZ’s independence are rightly being asked.
- Is the RBNZ’s forecast of annual inflation plummeting from 6.10% in June 2023 to 3.70% by June 2024 based on a detailed projection of the component parts of domestic/non-tradable inflation, or is it just the inflation figure that falls out of their econometric model after they enter the GDP and unemployment variables? The stickiness and permanency of wage-push domestic inflation is well known. The “elephant in the room” with our inflation problem in New Zealand is constant price increases from the public sector and non-competitive parts of the economy. Current price trends are all upwards for insurance premiums, rents, local government rates and building costs. The annual non-tradable inflation rate increased in the March quarter and will likely move higher again when the June quarter inflation data is released on 14 July.
- Why are the RBNZ so confident that inflation peaked in the March quarter because that result was less than their own forecast? The only reason why the March quarter inflation was less than expected was an unanticipated larger fall in petrol prices, all other prices were higher than forecast. Global oil prices have since increased and the NZD/USD is lower, therefore transport/petrol prices will not be decreasing in the June quarter.
- Has the RBNZ accurately recognised the sources of inflation? The issue the RBNZ has with reducing the inflation rate is that the inflation is not coming from interest rate sensitive parts of the economy. Higher interest rates can dampen consumer demand and make saving more attractive than spending. However, the wage/price inflation spiral we have experienced stems from the supply side of the economy, particularly the previous labour shortages caused by Government policy.
There would seem to be a real risk that the RBNZ are forced to reverse their stance of not increasing interest rates any further. Economic growth over coming months would need to be stronger than their forecast. Certainly, export sector and tourism activity appears robust and the global economic downturn the RBNZ expect is appearing less likely. The next OCR review date is 12th July, just a week before the all-important June quarter CPI inflation figures on 19th July.
Another very good question to ask is why New Zealand only has quarterly inflation reporting when every other country has monthly figures? The markets are operating in a vacuum of up-to-date information on the economy.
Higher USD and US bond yields set to reverse
The strong US dollar gains on global forex markets over the last three weeks is not only due to the debt ceiling risk, but also hawkish rhetoric from some US Federal Reserve members that inflation threats are still high and US interest rates need to be increased further. The Fed’s next meeting on 14 June is headed for a right royal showdown of conflicting views as Chairman Jerome Powell is in the opposite camp, that substantially tighter credit conditions in the US negate the need for any further interest rate increases. Last Friday’s PCE inflation number for the month of April at +0.40% being marginally above +0.30% prior forecasts will be fuel for the hawks. The May CPI inflation data is released on Tuesday 13th June, the day before the 14th June Fed meeting. A monthly increase below the 0.30% consensus forecast will strengthen Powell’s position of pausing on further interest rate increases.
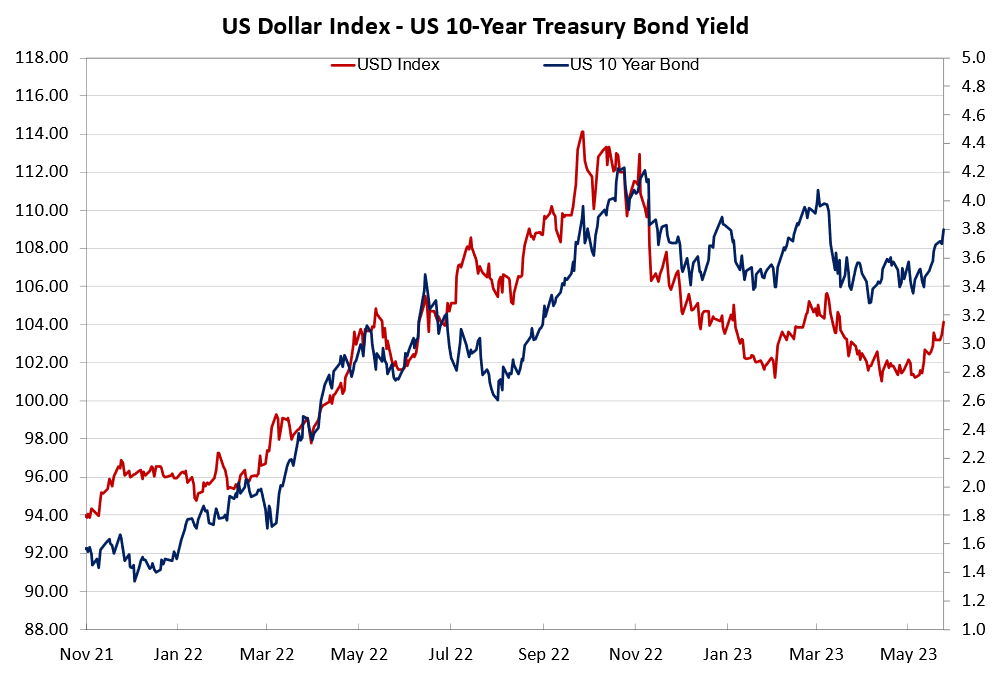
The USD Dixy Currency Index has followed US 10-year Treasury Bond yields higher over recent weeks in a very similar pattern to witnessed in February/March when inflation and jobs data was temporarily stronger than expected (refer chart below). A resolution to the debt ceiling crisis before 5 June and a pause from the Fed on 14 June stand to reverse both the USD and US interest rates sharply back downwards again. If that scenario unfolds as expected, the Kiwi dollar will have a good chance of recovering its lost ground.
Daily exchange rates
Select chart tabs
*Roger J Kerr is Executive Chairman of Barrington Treasury Services NZ Limited. He has written commentaries on the NZ dollar since 1981.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.