
In hindsight the Reserve Bank's Official Cash Rate (OCR) decision appears to have been a masterstroke. A touch of genius.
NO. I'm not talking about the OCR decision of last week!
I'm talking about the RBNZ's surprise 50 basis-points hike of the OCR in April, which blindsided financial markets and caused general bafflement, including - I must confess - for yours truly. But while we might not have all known at the time just what exactly the RBNZ was up to with that - clearly the RBNZ did.
At this point I'll give a big hat-tip to BNZ head of research Stephen Toplis, who made this comment prior to last week's OCR announcement: "There are some who believe the main reason the RBNZ went 50 at its last meeting, when most thought 25 was the most likely outcome, was because it had decided to minimise the chance that it would have to be aggressive post Budget so as not to become embroiled in the political process. This line of reasoning may have some merit," Toplis said.
Sometimes you just read something and the lightbulbs go off. This was one of those occasions. And for me this lightbulb moment became even more pronounced after last week's OCR decision and accompanying Monetary Policy Statement were released.
Remember that in the lead up to last week's decision the financial markets were in something of a lather and were pricing in a peak OCR of approaching 6%.
The mainstream media appeared ready and willing to offer up some filleted and seared Reserve Bank Governor on their evening menus as the expectation had it that the OCR would be heading for the moon and the Government's May 18 Budget would be the reason. The RBNZ was set up to be the villain of the piece in huge political arguments about the cost of living and the Government's willful contribution to that.
However, the RBNZ was not playing the game. The hitherto resolutely 'hawkish' RBNZ didn't exactly jump into 'dove' clothes overnight, but the hawk suit had suddenly lost a lot of feathers.
In its April OCR statement the RBNZ had expressed concern about the potential stimulatory impact of the then not-yet-released Budget. And it also expressed concern about the potential inflationary impact of a surge in migrants.
However, by the May OCR statement both the Budget and migration were seen as less problematic.
Were these two things perhaps less problematic because the RBNZ had already got the jump on them with the 50-point increase in April?
So, in May the RBNZ has done a 25 point OCR rise and holstered its guns. And the OCR is now in pause mode.
Why was the RBNZ able to do this? Because it had done the 50-point jump in April - ahead of the Budget and ahead of the potential firestorm of political arguments, thus neatly avoiding putting itself in the middle.
The RBNZ jealously guards its statutory independence from the Government. But that doesn't mean it isn't 'political' - with a small 'p' - as an organisation. It can be argued that just keeping oneself out of political arguments will at time require 'political' behaviour and statements. And I think the RBNZ has always done this.
Common sense surely suggested that the RBNZ would need to 'pause' at some point and have a look at what its massive tightening wave - a whole 525 basis points of OCR hike since October 2021 - was achieving. So a pause now is very justifiable. I actually thought the RBNZ should have paused before now anyway. Remember the OCR is a blunt instrument, which operates with a lot of what the economists like to call 'lag'. In other words it takes a while to see if it is working.
So, now we are in what the RBNZ describes as watch, worry and wait mode - just as it happens that the election is coming into view. That's worked out well.
At this point it is probably worth highlighting just exactly where the expectation comes from that the OCR is now on 'hold' for the foreseeable future.
It's in the style of things-RBNZ that the central bank won't say in as many words: "We are lifting the OCR another 25 points and then that's it." No. It doesn't need to - it lets its forecast table do that in true 'raised eyebrow' RBNZ style.
Below is an abridged version of that latest table. (The full table appears on page 57 of the latest MPS.)
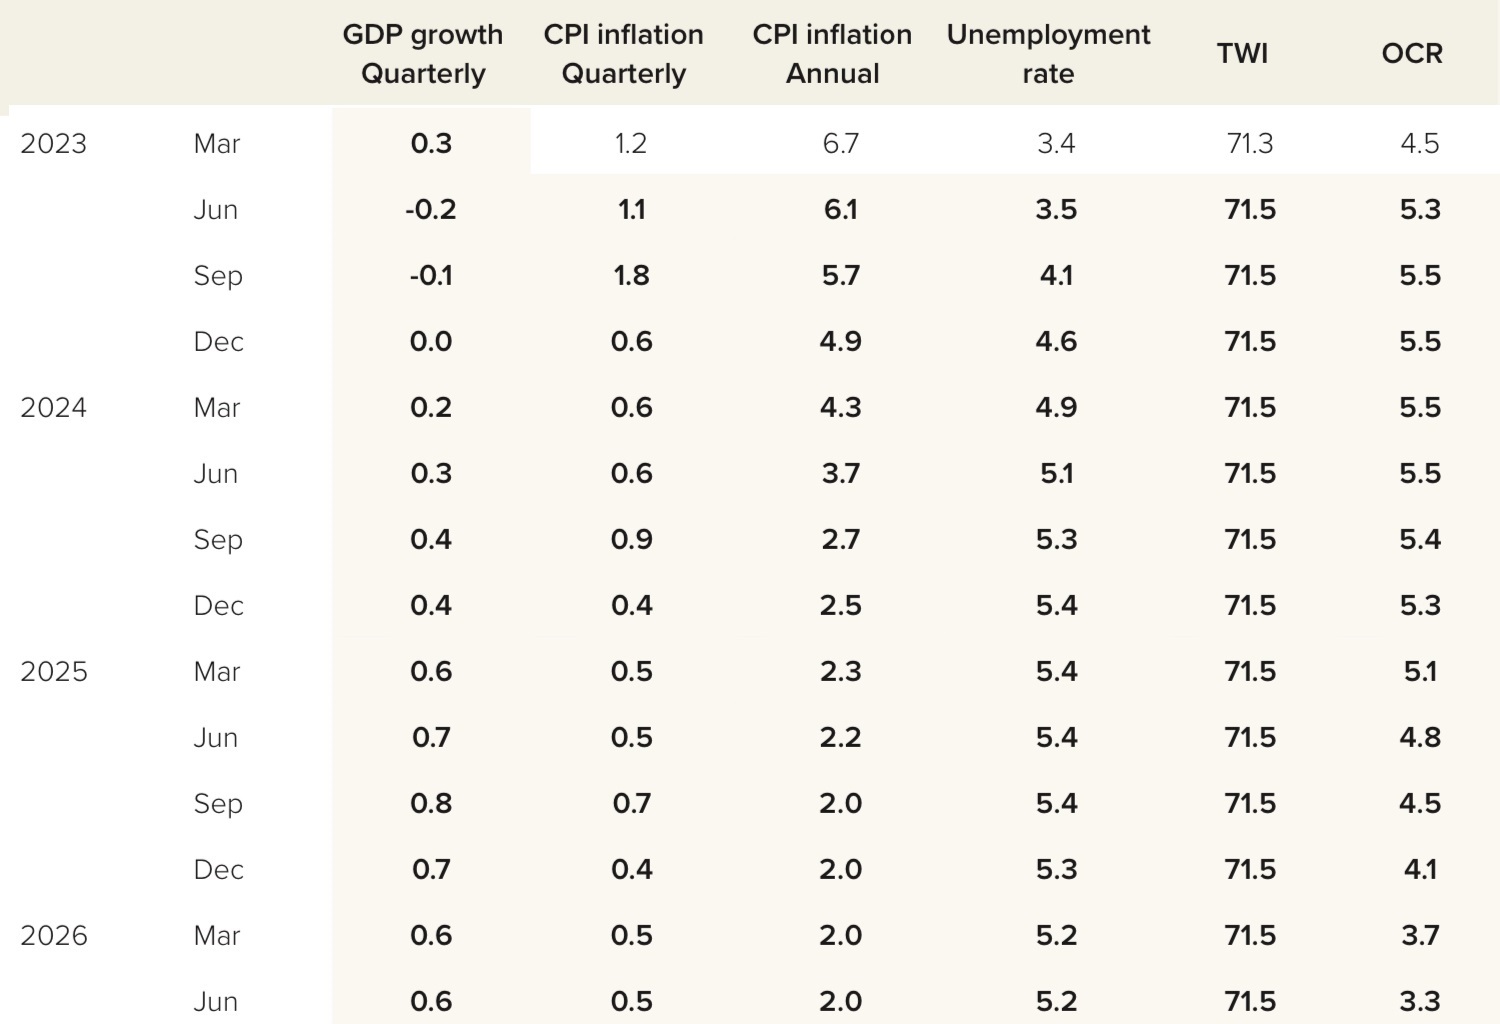
Okay, so if we look at the column on the far right, under 'OCR', we can see that the RBNZ is forecasting that the OCR will now stay at 5.5% till the second half of next year. This is the RBNZ's way of 'telling us' it has put the OCR on hold.
Does this mean that it most definitely will NOT move the OCR either up or down till the second half of next year?
Well, of course not. Not at all. That's the beauty of 'saying something' without actually saying it! The 'market' has now decided the OCR is on hold (because the RBNZ wants it to draw that conclusion) but the RBNZ can change its mind at any time. All the RBNZ has to say is that the data changed and that required a change of tack.
So, will the RBNZ change its mind?
Well, interestingly, among the economists Westpac thinks there will be another 25 point hike in August. ANZ says there will be one in November.
I reckon the RBNZ would only make a move in August if it really has to. I think it really intends the 'watch, worry and wait' phase to extend beyond October 14 (election day).
What events might force the RBNZ's hand? Or alternatively what might make it comfortable sitting tight? Let's have a quick look at some of the key dates on the economic calendar for the rest of the year.
As far as the RBNZ itself is concerned, it has three more OCR decisions to make before the election - on July 12, August 16 and October 4 - and then the last OCR review for the year is November 29.
The next key piece of economic data to be released is March quarter GDP on June 15. This could potentially be contentious - and as political as hell.
GDP shrank in the December quarter. If GDP has shrunk again in the March quarter then this will be two consecutive quarters of negative growth - meeting the technical description of a recession. People get pretty excited over the 'R' word and politicians will undoubtedly get very excited if we do indeed go into 'recession'.
On the other hand though, if GDP has just snuck into positive territory for the March quarter (as I suspect will be the case) then we won't be in recession and the earliest point we might technically go into recession is after the September quarter. But we won't have the September quarter figures released till December - well after the election has been decided.
So, there's a reasonable chance the politicians won't have a 'real' recession to play with in the election campaign, although there's a fair chance the June quarter GDP figures - to be released on September 21 - will be negative, so, I suppose they will be able to drum up a 'recession is nigh' narrative.
What about inflation? The next Consumers Price Index inflation release for the June quarter comes out on July 19 and will be the last inflation figure before the election (the September quarter figures come out on October 17).
Then there's labour market figures. The unemployment/wage figures for the June quarter come out on August 2 and then the next ones are not till after the election on November 2.
Looking at this list of data releases suggests to me that the only thing that might force the RBNZ to hike the OCR again before the election could be if that CPI figure on July 19 is a shocker. Somehow though, I doubt it will be.
It seems the road could be looking clear for the RBNZ till after the election as far as any more OCR moves might be concerned. What about after then?
Well, the ANZ economists as mentioned further up the article are forecasting an OCR hike in November. To me, this would have to be a real possibility. Much will likely depend on the housing market. If a National-led Government does prevail on October 14 and does indeed indicate swift reversal of Labour housing measures such as the removal of interest deductibility for investors, then we might confidently expect to see the housing market get another wind. As the ANZ economists have been saying for some time, the RBNZ would not likely be enthused about the prospect of the house market taking off again when the war against inflation is far from won.
So, the RBNZ lobbing another OCR hike in the immediate aftermath of the election would appear a distinct possibility.
But let's see. We are now in watch, worry and wait mode. Maybe the cumulative effects of all the hiking the RBNZ has already piled on us to date will prove to have been more than enough. We just don't know one way or the other yet.
Of course if the economy really does start to struggle more than the RBNZ currently believes it will, then it can start to reduce the OCR. But again, this would not be till after the election. And the RBNZ would have to be convinced inflation really is on the run.
*This article was first published in our email for paying subscribers. See here for more details and how to subscribe.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.