Summary of key points: -
- RBNZ revealed as a large NZ dollar seller
- Financial markets await Federal Reserve interest rate decision
RBNZ revealed as a large NZ dollar seller
An innocuous entry in a table on the Reserve Bank of New Zealand’s (“RBNZ”) website in late August has provided a belated explanation as to why the Kiwi dollar reversed sharply from its appreciation to 0.6400 in mid-July.
In a transaction across the local FX market to increase their currency intervention reserves capacity, the RBNZ purchased US dollars and sold NZD4 billion. Evidence of a large, one-off FX market transaction of this nature was not detected at the time in late July as it appeared that the NZD/USD exchange rate was merely following the AUD/USD rate downwards, as it normally does. A very stable NZD/AUD cross-rate at the time indicated that there was no independent and separate NZD selling occurring. It has now transpired that the RBNZ was a massive seller of Kiwi dollars in a compressed period of time and the Aussie dollar was actually following the NZD lower!
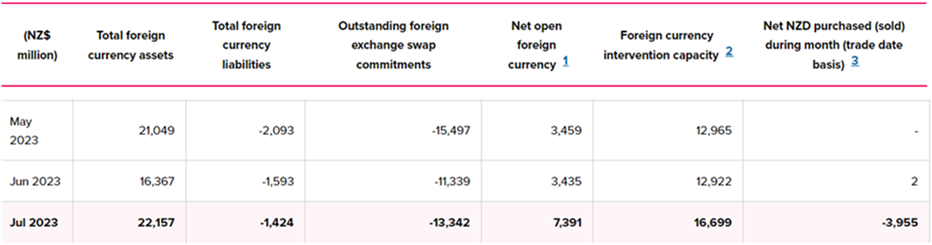
The table below from the RBNZ’s website confirms the selling of NZD4 billion in the month of July and the resultant increase in the foreign currency intervention capacity from NZD12.9 billion to NZD16.7 billion (last two columns). The table is updated monthly, so in two weeks’ time we will be able to observe whether the RBNZ purchased any more USD’s over the month of August. (See earlier article on this issue here.)
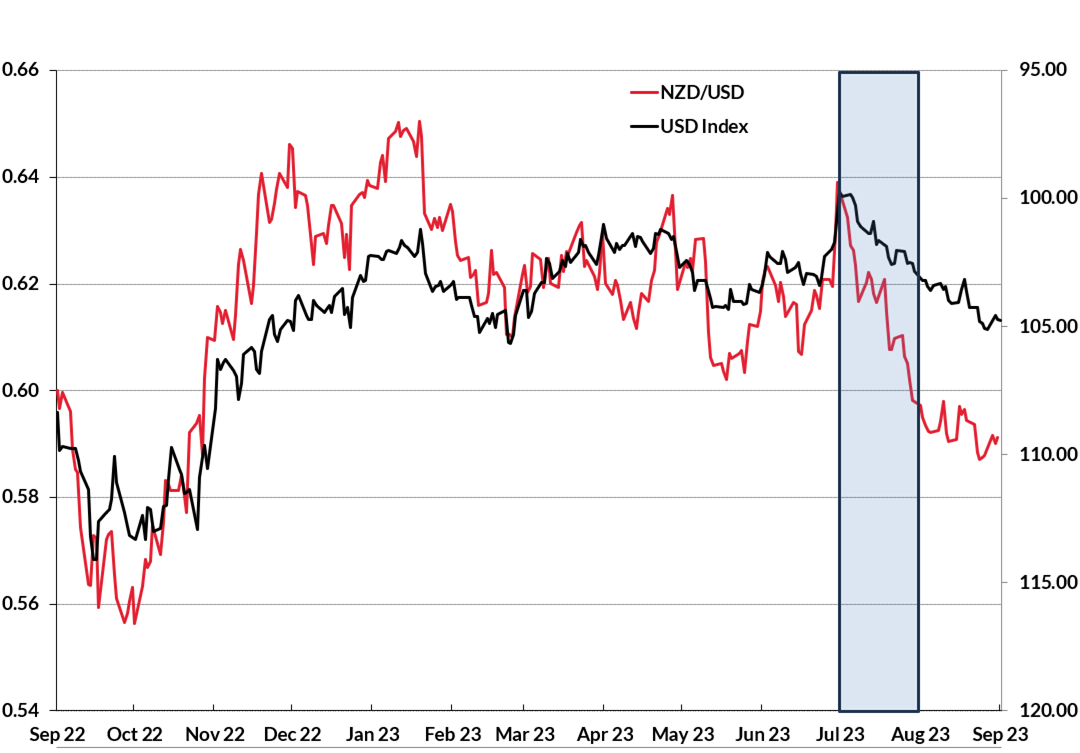
As the chart below confirms, the Kiwi dollar was certainly hit hard by a big seller which weakened the NZD/USD rate a lot further than what general USD appreciation against all currencies at the time would have impacted on the NZD/USD rate. From mid-July to the end of July the NZD/USD exchange rate depreciated 4.70% from 0.6400 to 0.6100. Over the same two-week period, the USD appreciated only 2.50% on the USD Index.
The RBNZ’s intention to increase their USD-denominated reserves for FX market intervention purposes was disclosed to the market back in January 2023, with the RBNZ Board Chair confirming that the reserves would be increased by an undisclosed amount from the NZD12 billion amount which had been unchanged since 2007. The increase in the size of the economy and the increased volumes traded in the NZD FX market justified the increased USD reserves. Fair enough. The amount and timing of the USD purchases would not be disclosed by the RBNZ as it was considered “market sensitive” information.
It is very rare for the RBNZ to intervene directly in the FX markets to influence the value of the NZ dollar. They last intervened in 2007 and they would only do so again in “exceptional circumstances to maintain financial stability and ensure essential transactions can continue to occur”. The RBNZ’s Monetary Policy Committee has the power to “intervene in the exchange rate when the NZ dollar has moved to exceptionally low or high levels that cannot be justified by economic fundamentals”.
There is no problem with the RBNZ increasing their US dollar war chest of reserves for intervention purposes if it was ever needed.
The problem is with their bizarre execution of the FX transaction to get the funds from NZ into US dollars.
There are several pertinent questions that need to be asked as why the RBNZ made the decision to suddenly dump NZD4 billion on the FX market over a short two-week period. The NZD4 billion the RBNZ sold accounted for nearly 10% of all trades in the NZD/USD FX market over that time period. A big seller with that amount, on the margin, is always going to shift the Kiwi dollar a good few cents lower.
- The RBNZ clearly had the authority to increase the USD reserve in January 2023, so why didn’t they start to buy, say NZD200 million per month, over a prolonged 20-month time frame so as to sift the deal into the market and not impact the value of the NZ dollar?
- The Government increasing the RBNZ’s capital by $500 million during July appears to have been the catalyst to trigger the rather naïve buy USD/sell NZD4 billion FX transaction.
- The RBNZ use to have FX dealers who regularly maintained a dialogue on FX market conditions and outlook with local/offshore bank participants, hedge funds and currency investors from Australia, Asia, Europe and the US. They have probably replaced those FX dealing jobs with climate change analysts, as it appears some RBNZ mandarin, unaware of the FX market impact, has pushed a button to immediately sell NZD4 billion.
- Just why the RBNZ would allow itself to slam the NZ dollar value down by three cents, which increases imported inflation, when they are attempting to reduce inflation and a higher NZ dollar value helps to do that. It beggars belief that they would be so ill-advised on the consequences of what they were doing. A clumsy “own goal” if there ever was one!
- Why have they left the USD intervention reserve amount unchanged for 16 years, then suddenly increase it by 33% in the space of two weeks? Why isn’t there an automatic adjustment mechanism to progressively increase the amount annually, based on the size of the economy and FX market trading volumes?
As a foreign exchange advisor, our advice to the RBNZ on how to increase their USD reserves would be to have a pre-approved policy and strategy that authorised progressive buying of USD’s over a long period when the NZD/USD was trading nearer to the top of its cyclical range (not close to the bottom of its range as it is now in the low 0.6000’s). Adding USD reserve at the bottom of the cycle sets them up to book large “marked-to-market” FX revaluation losses on the USD assets when the NZD subsequently appreciates. Given the size of their revaluation losses already booked on the NZ Government Bonds they hold from the Covid-era money-printing, maybe the potential FX losses are not that material to them!
Importers, exporters and local fund managers with ongoing FX exposures should expect that their own central bank would handle such large FX transactions with a bit more consideration and finesse. Using a bank intermediary to discretely set up the amounts and timing each month for when Fonterra are mechanically selling USD/buying NZD to match the RBNZ on the other side transacting the opposite, would satisfy both parties’ objectives without moving the NZD/USD market price at all!
Financial markets await Federal Reserve interest rate decision
The US dollar is trading back to its six-month highs of 105 on the Dixy Index ahead of the Federal Reserve meeting this Wednesday 20th September (Thursday morning NZT). It would be a surprise if the Fed increased interest rates further, however it will be a “hawkish pause” with a message that further increases may be needed if the economic data (inflation and jobs) start to move up again. Last month’s headline inflation rate did increase due to oil/gasoline prices increasing, however the core inflation measure, which the Fed concentrate on, reduced on an annual basis from 4.70% to 4.30%. The recent rapid increase in crude oil prices from US$70/b to US$90/b (WTI) due to supply cuts may prove to be temporary as the markets re-assess global demand at the higher levels.
The markets will be looking for any subtle change in wording in the Fed’s statement and how Chair Powell handles the media questions. The Fed should be much more comfortable to signal an end to the monetary tightening cycle as the US labour market has softened over recent months and the risk of wage increases threatening inflation have certainly abated. However, they always like to keep their options open for the future, so they will not be signalling an emphatic “no more interest rate increases” that the RBNZ, the Bank of England and the ECB have now done.
It looks like the FX markets may have bought the USD in the lead up to the statement, however if the Fed are not as hawkish in their message as the markets are expecting, we should see a USD pullback that would allow the NZD/USD rate to recover above 0.6000.
The other determinant of NZD/USD rate movements is the Yuan currency value and Chinese economic data. The risk environment is improving on that front with a stabilisation in the latest Chinese economic data (retail sales and industrial production) and the Yuan has stopped depreciating above the 7.30 level to the USD. The global funds that wanted to disinvest from China have now done so, therefore some recovery in the USD/CNY rate to 7.00 seems more likely than further Yuan depreciation.
Daily exchange rates
Select chart tabs
*Roger J Kerr is Executive Chairman of Barrington Treasury Services NZ Limited. He has written commentaries on the NZ dollar since 1981.
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.