
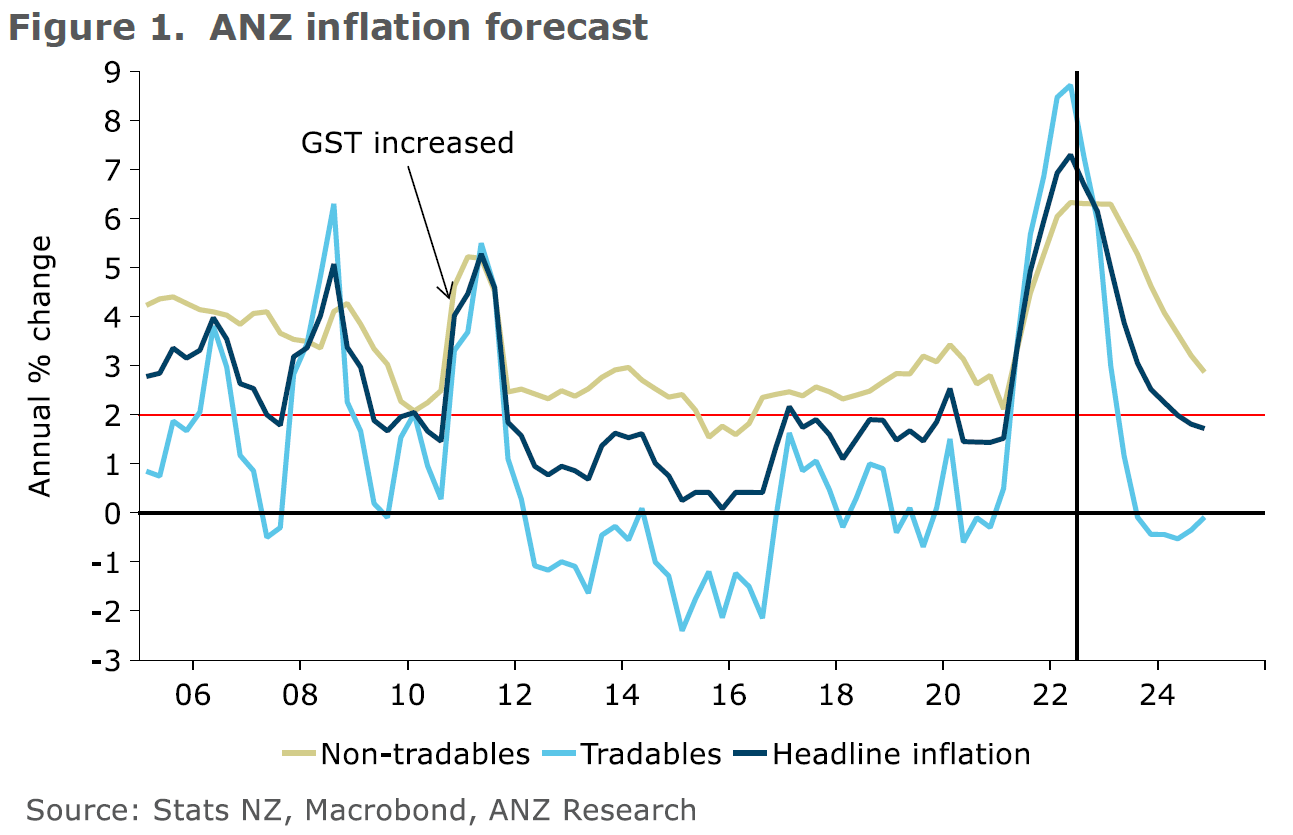
Economists at the country's largest bank are predicting that inflation will be back to the targeted 2% level by mid-2024, but they see "a long and difficult battle" for the Reserve Bank (RBNZ) against domestic inflation pressures.
In an NZ Insight publication ANZ economist Finn Robinson and chief economist Sharon Zollner say "surging wage growth" and ongoing local cost pressures will see NZ-generated inflation "hold up around current highs" till early next year before gradually easing. This publication is the second part of a detailed crunch of the inflation picture by the ANZ economists, with the first published earlier in the week.
The RBNZ has been aggressively hiking interest rates since October last year to counter inflation that has been running very hot, reaching 7.3% by the June quarter of this year. The ANZ economists believe that was the peak. The Official Cash Rate has been hiked by the RBNZ to 3.0% so far and the ANZ economists see this peaking at 4.0% by the end of this year - although they do see risks it will have to go higher.
Wholesale interest rate markets are currently pricing in a 4.25% OCR by the middle of next year, with some leaning now even toward a 4.50% peak.
While forecasting a peak OCR of 4.0%, Robinson and Zollner say "risks are firmly tilted" towards more hikes taking the OCR above 4% needing to be delivered to bring inflation down swiftly enough.
"There’s certainly not much wriggle room on that front. Even in our central forecast, inflation would have been above the 2% midpoint of the RBNZ’s target band for three years. We see risks around the outlook for both domestic (non-tradable) and global (tradable) components of inflation."
The economists say the key is to distinguish between the short and medium term.
"In the very near term, we fully expect inflation to ease, and quickly, particularly thanks to factors like rapidly falling oil prices. But over the medium-term, we see significant risks that inflation will remain too high for too long, which would necessitate further OCR hikes in order to bring inflation back to target within an acceptable timeframe."
They say that "front and centre" on the domestic inflation front is the possibility that rapidly accelerating labour costs (absent a commensurate increase in productivity) could see domestic inflation pressures come in stronger and more persistent than forecast.
"We currently anticipate that annual growth in private sector productivity-adjusted labour costs will peak at 4.4% in the first quarter of 2023 (versus 3.4% in Q2 2022). But wage pressures have surprised recently with their strength. Domestic labour demand remains insatiable, and with the Australian labour market likely to add further heat over the next year, upside surprises feel likelier than downside ones."
This highlights, the economists say, the "double-edged sword" that is sharply rising wages.
"It sounds like great news for households, and it’s no doubt a relief for workers, particularly those on lower incomes, who have been watching inflation eat away at their real purchasing power. But for the RBNZ, strong wage growth means that household demand is more resilient to the aggressive interest rate hikes that they have delivered – ie that more OCR action could be required to slow spending sufficiently to bring inflation down."
Robinson and Zollner say that as surging inflation gets factored into wage and price-setting behaviour, it raises the risk that a 4% OCR is no longer as much of a brake on the economy as previously thought.
"In other words, high inflation expectations and wage growth mean the neutral OCR could currently be creeping higher (the neutral OCR is the level of the OCR that is neither contractionary nor expansionary for the economy). In coalface terms, people’s idea of what a 'reasonable' mortgage rate is might be gradually lifting again, just as it gradually fell as inflation and nominal interest rates trended lower over years and decades.
"The RBNZ’s latest estimate of the neutral OCR is 2%, but they have already said that they are revisiting their models, and some members of the Monetary Policy Committee have given a range of 2-3% as their sense for where neutral is.
"It’s a big deal, as changes in the neutral OCR go 1:1 into the required OCR. If the neutral OCR is 3% rather than 2%, then an OCR closer to 5% rather than 4%would be needed to deliver the monetary tightening required to bring inflation back to 2% within an acceptable timeframe, all else equal. Sounds high, but so is inflation. And it’s still well-below the 8.25% OCR peak seen before the GFC (although the housing market was still in full bubble mode at that point, whereas currently house prices are falling)."
On a global perspective, the economists believe that "one-off spikes" in inflation look likely to become more common.
"While Covid appears to be in retreat as a global disruptor (touch wood), geopolitical tensions continue to raise the risk of ongoing commodity price surges, or a retrenchment of global trade. And the ongoing costs of adverse weather conditions continue to mount as climate change rolls inexorably forward. All of these factors mean the era of New Zealand importing global deflation through our import prices is probably behind us.
"All in all, it’s an inflation soup out there, both domestically and internationally. We’ve seen a perfect storm of supply-side impacts through COVID-19 and the supply chain chaos it has unleashed, combined with what turned out to be overly powerful fiscal and monetary stimulus (given how unexpectedly resilient economies turned out to be over the past few years). While we are forecasting that a 4% OCR will be enough to achieve a return to 2% inflation over the next two years, there are clearly significant risks that interest rates will need to go higher to engineer a timely return to target."
In summing up the situation, Robinson and Zollner say it’s not all one-way traffic for interest rates, but the balance of risks remains firmly tilted towards more hikes being needed than less.
"While headline inflation numbers look like they may have peaked in several countries, including New Zealand, that’s not sufficient. Central banks need to ensure inflation gets all the way back to their targets, and in a reasonable timeframe (ie within a couple of years).
"If the process is too slow, neutral interest rates will rise significantly, and central banks could find themselves on a treadmill of ever-higher rates just to stay still in terms of the real level of tightening they are delivering."
We welcome your comments below. If you are not already registered, please register to comment
Remember we welcome robust, respectful and insightful debate. We don't welcome abusive or defamatory comments and will de-register those repeatedly making such comments. Our current comment policy is here.